
Wealthfront (WLTH) Home Lending Story Raises A Bargain Or Value Trap Question
Wealthfront (WLTH) drew fresh attention after its latest share price of $10.89, with recent trading showing mixed short term moves and a weaker year to date performance that investors are reassessing.
Recent trading paints a mixed picture for Wealthfront. The 7 day share price return of 5.01%, 30 day gain of 13.08% and 90 day rise of 16.47% point to improving momentum, while the year to date share price return remains down 17.62%.
Scan how Wealthfront's recent swings compare with other rebound candidates using the curated 27 high quality undervalued stocks, which couples share price weakness with stronger fundamentals.
Wealthfront now trades below both analyst targets and an estimated fair value, despite the recent bounce. Is that discount compensation for real risks, or has caution gone too far?
Most Popular Narrative: 12% Undervalued
On the most followed narrative, Wealthfront's fair value sits at $12.33 compared with the latest $10.89 close. This puts that recent rebound into a wider earnings and margin story rather than just a short term bounce.
Home Lending targets a pool highlighted by US$2.5b in wires sent to escrow and title companies in 2025 and is backed by expanded licensing and a larger credit facility. This can increase interest and fee income and deepen client relationships that support long term earnings.
See why 1 investors see Wealthfront as 12% undervalued.
Result: Fair Value of $12.33 (UNDERVALUED)
Still, Wealthfront leans heavily on a relatively young, referral driven client base and on newer products like Home Lending, where slower uptake could challenge that undervaluation story.
Find out about the key risks to this Wealthfront narrative.
Another Take On Wealthfront Valuation
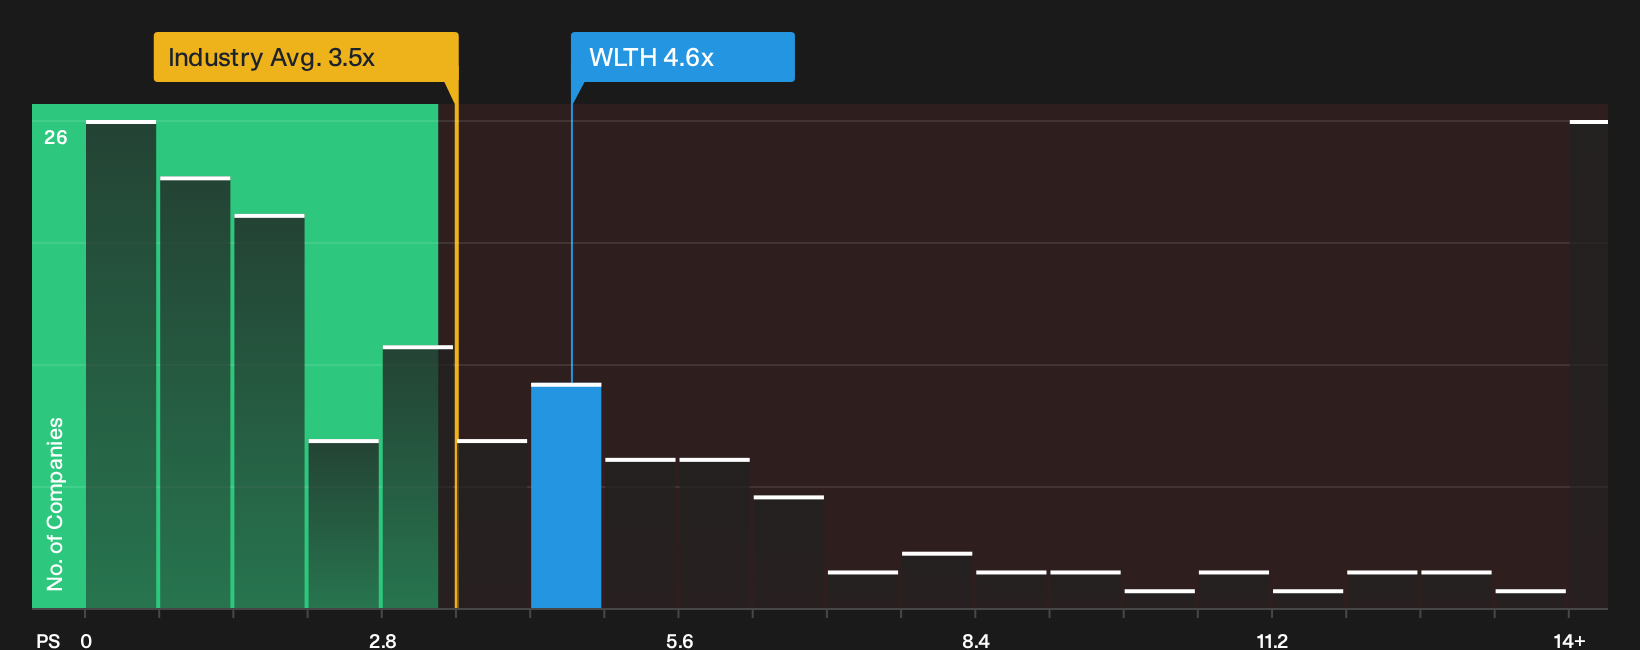
On simple sales multiples, Wealthfront looks expensive. The P/S ratio sits at 4.6x compared with 3.5x for the wider US Capital Markets group and a fair ratio of 2.4x that the market could move toward, which points to real valuation risk if sentiment cools.
That contrasts with the earlier fair value work suggesting Wealthfront trades about 29.6% below an estimated worth. The key question is whether investors lean more on richer peers or on a market that might re rate the stock closer to that fair ratio over time.
For a closer look at how the current pricing compares with those benchmarks, and what the gap could mean for potential future upside or downside, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Wealthfront is clearly split, so move quickly from reading to testing the numbers yourself and pressure test the valuation case. To see what investors are already optimistic about, review the 3 key rewards.
Looking for more investment ideas beyond Wealthfront?
Do not stop with one stock. Use this window of time to line up a watchlist of opportunities that fit the way you like to invest.
- Target potential mispricings by scanning companies that combine weaker recent share prices with healthier fundamentals through the 27 high quality undervalued stocks.
- Strengthen portfolio resilience by focusing on businesses with cleaner finances using the list of solid balance sheet and fundamentals (25 results).
- Hunt for overlooked potential by checking the 20 high quality undiscovered gems before attention and pricing move ahead of you.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com