
Learn Why The Bull Case For North Atlantic Energies (ENXTPA:NAE) Could Change Following Smaller Half Year Loss
- North Atlantic Energies released half year 2026 results, reporting sales of €5,883.7 million, revenue of €5,892.2 million and a net loss of €30.3 million compared with a €84.7 million loss a year earlier.
- The sharp reduction in loss per share from €6.59 to €2.36 suggests that cost control or mix improvements had a greater impact than the modest change in top line figures.
- The next step is to consider how North Atlantic Energies' much smaller half year loss could influence the broader investment narrative for the business.
What Is North Atlantic Energies' Investment Narrative?
For North Atlantic Energies to make sense in a portfolio, an investor needs to believe the refining and fuel distribution platform can convert today’s relatively steady sales into durable profitability. The half year 2026 results, with revenue of €5,892.2 million and a net loss of €30.3 million, point to tighter cost control but not yet to a self funding model. In the short term, the key levers are operational efficiency in the refineries, disciplined maintenance capital spending, and how well the Esso branded retail and wholesale networks can hold volumes and pricing.
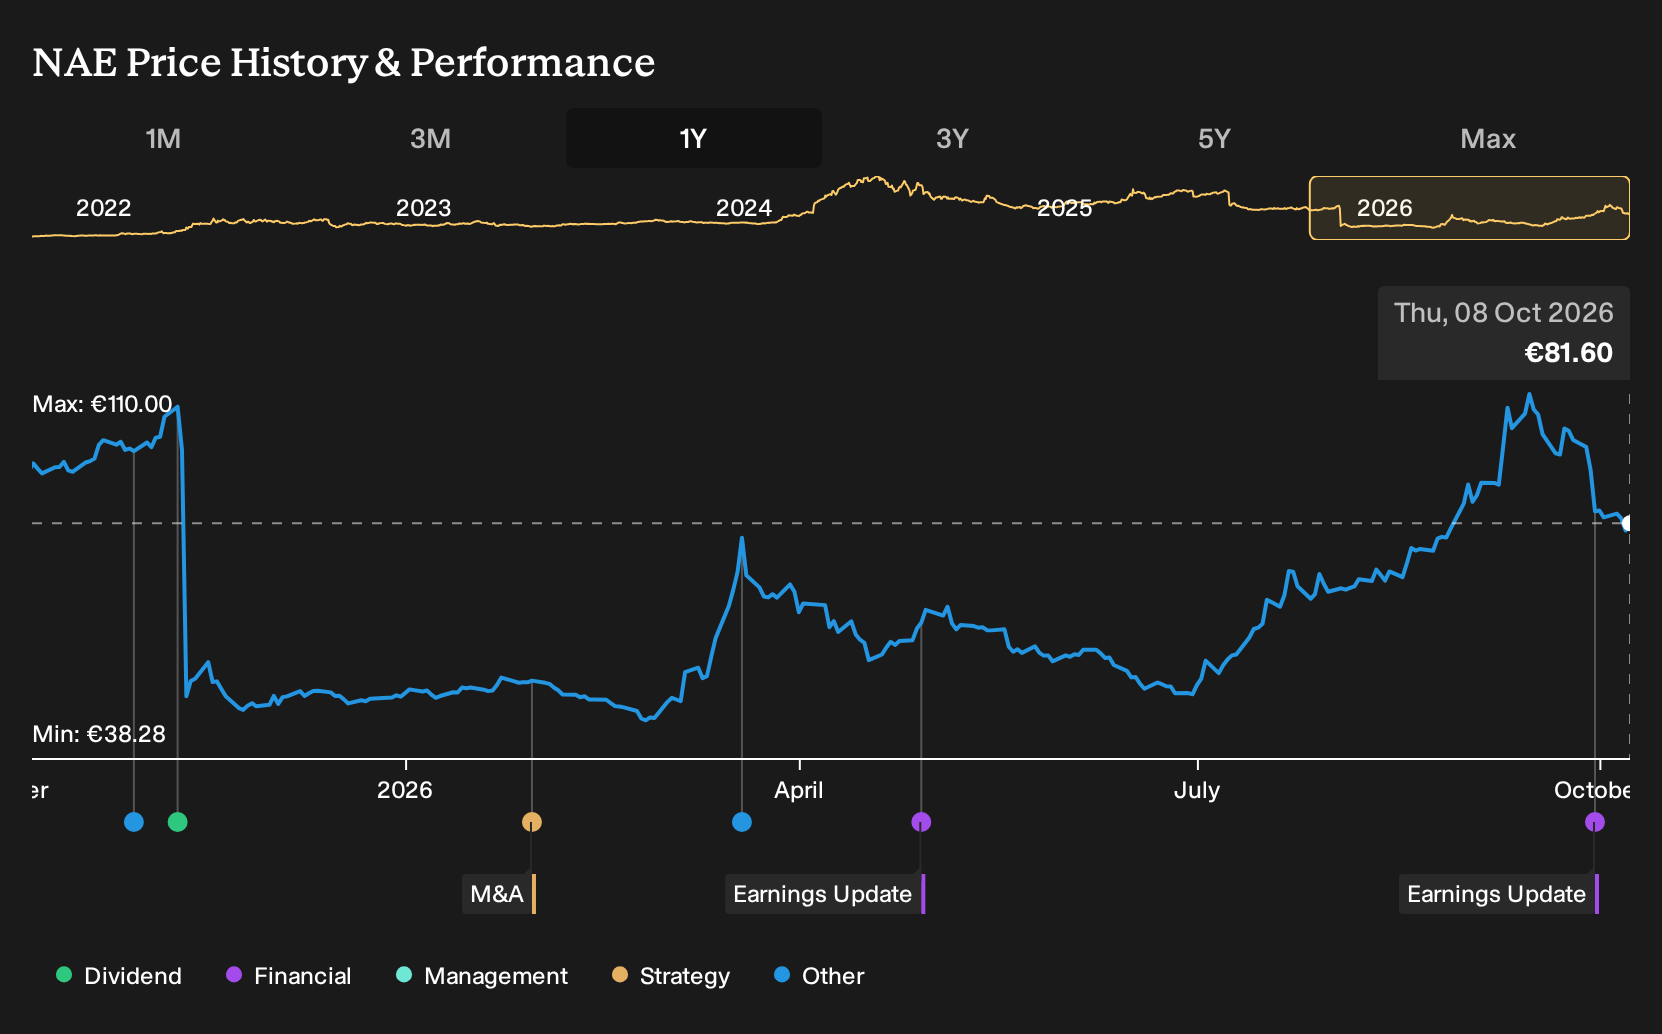
Earnings quality remains a sticking point. The business is still loss making, carries debt that is not well covered by operating cash flow, and pays a dividend that screens as poorly covered. Share price swings and a relatively new, less independent board add another layer of uncertainty. The latest reduction in loss supports the narrative of improving discipline, yet it does not on its own resolve these broader pressure points.
Even so, the comfort some investors might draw from the smaller loss can fade quickly once they focus on ...
There's only one way to know the right time to buy, sell or hold North Atlantic Energies. Head to Simply Wall St's company report for the latest analysis of North Atlantic Energies's Fair Value.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your North Atlantic Energies research is our analysis highlighting 1 key reward and 4 important warning signs that could impact your investment decision.
- See our latest analysis for North Atlantic Energies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate North Atlantic Energies' overall financial health at a glance.
Looking For More Investment Ideas Beyond North Atlantic Energies?
If North Atlantic Energies has prompted you to reassess where risk and reward line up in your portfolio, it can help to scan a wider field of potential opportunities using the Simply Wall St Screener.
- For investors who want quality at a reasonable entry point, review a focused set of 180 high quality undervalued stocks that pair stronger fundamentals with more modest valuations.
- If balance sheet strength matters most to you, filter for companies on our list of solid balance sheet and fundamentals (206 results) and see which businesses carry less financial strain.
- Income focused investors can hunt for potential cash return ideas by screening among our 227 dividend fortresses that combine higher yields with fundamental data in one place.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com