
ExxonMobil Holdings (XOM) Shares Climbed, What Is Behind The Move?
A Gulf tanker attack and hurricane-related outages in the Gulf of Mexico squeezed oil supply, lifting crude prices and pushing ExxonMobil Holdings (XOM) up about 3% in the latest session.
For investors watching ExxonMobil Holdings over more than a single headline, the pattern is clear. The stock has enjoyed a strong run, with a 90 day share price return of 21.33% feeding into a year to date share price gain of 37.38%. Meanwhile, the 1 year total shareholder return of 53.56% and 5 year total shareholder return of 223.84% point to momentum that has been building rather than fading.
Spot similar energy momentum by scanning our hand-picked 27 high quality undervalued stocks that, like ExxonMobil Holdings after the latest supply shock, are already reacting to tight crude markets.After a 3% jump and solid returns over multiple timeframes, ExxonMobil Holdings now trades at a double digit discount to one fair value estimate and at a smaller gap to analyst targets. Is that caution or opportunity?
Most Popular Narrative: 1% Undervalued
ExxonMobil Holdings closed at $168.50, sitting just below a narrative fair value of $170.91 that leans heavily on disciplined project execution and cash generation rather than a one off oil price spike.
Strong production growth from high return assets in Guyana and the Permian Basin remains central, with upstream volumes outside the Middle East at the highest level in more than two decades and the Permian at over 1.8 million oil equivalent barrels per day, which supports future revenue and earnings per barrel.
Guyana has already recovered about US$55b of investment and operating costs nearly two years earlier than anticipated, and the desaturation of this cost bank is expected to roughly double free cash flow between 2025 and 2030 versus 2025 levels, which feeds into future earnings and cash generation.
See why 346 investors see ExxonMobil Holdings as 1% undervalued.
Result: Fair Value of $170.91 (UNDERVALUED)
Still, the ExxonMobil Holdings story can change quickly if long term oil demand weakens faster than expected or if low carbon projects struggle to scale into meaningful earnings.
Find out about the key risks to this ExxonMobil Holdings narrative.
Another View: ExxonMobil Holdings Through The Earnings Lens
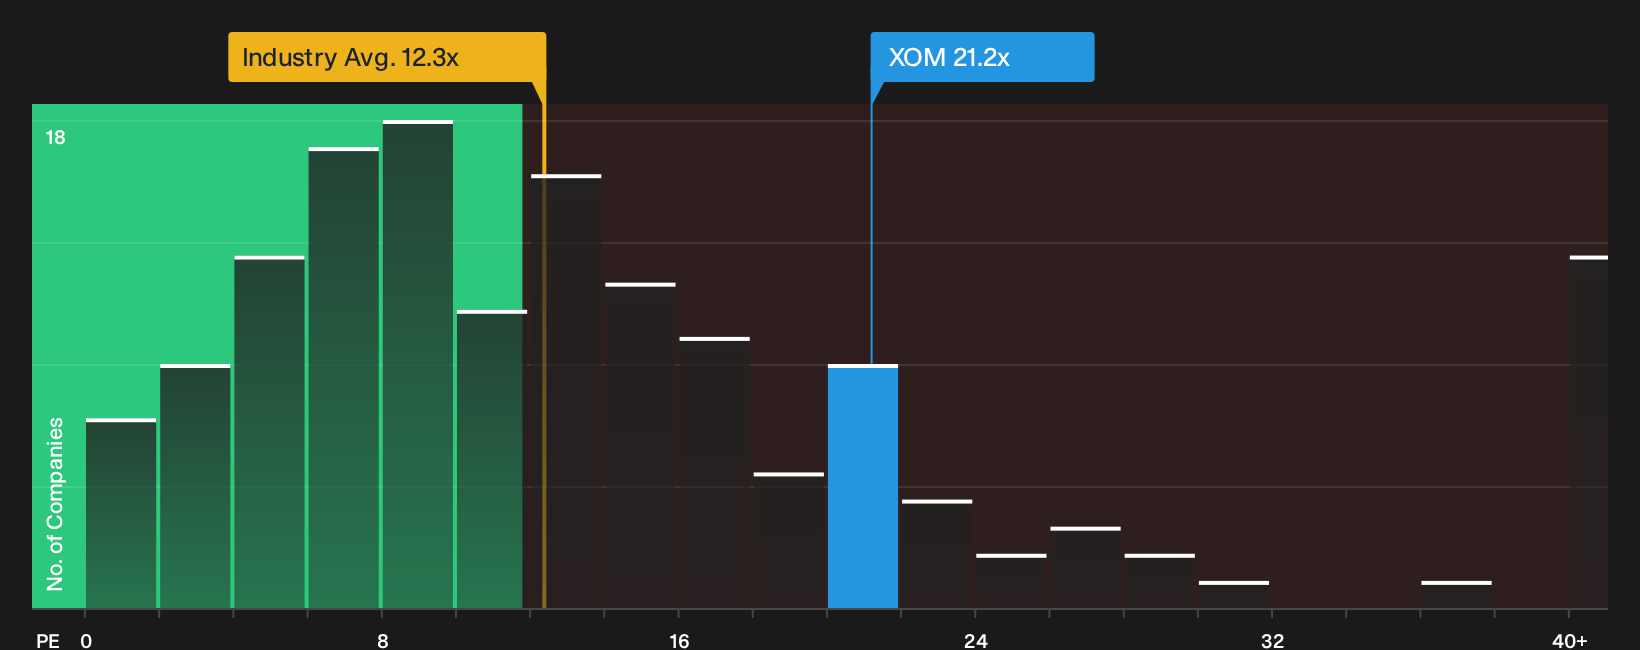
The earlier narrative framed ExxonMobil Holdings as slightly undervalued versus a fair value estimate. The earnings multiple tells a different story. At a P/E of 21.2x, the stock trades well above the US Oil and Gas industry at 12.3x and above the peer average at 17.6x, while only modestly below a fair ratio of 23.9x. That gap suggests investors are already paying a premium for ExxonMobil Holdings, with only a small buffer if sentiment toward sector earnings cools.
For anyone weighing that premium against quality and scale, it helps to see how the numbers stack up side by side in our valuation breakdown, including the fair ratio and peer comparisons, in See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and valuation tension around ExxonMobil Holdings feels finely balanced, move quickly from headline to hard numbers and test the story against your own framework using the 4 key rewards.
Looking for more ExxonMobil Holdings style investment ideas?
Do not stop with ExxonMobil Holdings. Use the Simply Wall St screener to spot fresh opportunities, compare setups, and pressure test what belongs in your watchlist next.
- Target resilient compounding potential by scanning a 8 dividend fortresses that can help anchor your portfolio with consistent income while you assess price swings elsewhere.
- Hunt for quality at a markdown using the 20 high quality undiscovered gems and see which businesses quietly combine strong fundamentals with underappreciated market attention.
- Dial down portfolio risk by filtering through a 31 resilient stocks with low risk scores so you are not relying on just one stock or story to carry your returns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com