
Credit Acceptance (CACC) Faces A Valuation Test After Latest Workplace Award
Credit Acceptance (CACC) just picked up its 12th consecutive Best Workplaces award in financial services, a culture signal that raises fresh questions about how this people focus connects to the current share price.
Recent trading has been choppy for Credit Acceptance, with the share price up 1.93% over the last day and 6.03% across the past week, but down 8.58% over 30 days and 13.28% over 90 days. The year-to-date share price return of 19.58% compares with a 1-year total shareholder return of 10.13%, suggesting that earlier momentum has cooled, while fresh workplace awards keep the story focused on execution and perceived risk rather than short-term sentiment.
Scan beyond Credit Acceptance and compare this workplace-driven story with 31 resilient stocks with low risk scores, which pairs resilient balance sheets with steadier share price profiles.
Bulls point to Credit Acceptance’s strong workplace record and its recent 19.58% year-to-date gain. Bears focus on the 13.28% 90-day decline and perceived risk. The key question is which side the current valuation signals appear to support next.
Most Popular Narrative: 15% Undervalued
Credit Acceptance last closed at $542.82, while the most followed narrative anchors fair value at $636.67. The current price sits below that storyline and puts the focus on whether the earnings path and legal headwinds can sustain that gap.
Recent moves to embed AI across pricing, underwriting, servicing, collections and sales workflows, including a roughly 5x quarter on quarter increase in AI call center volumes and new AI driven dealer tools, create room for better credit decisions and operating efficiency that can support net margins and earnings.
See why 3 investors see Credit Acceptance as 15% undervalued.
Result: Fair Value of $636.67 (UNDERVALUED)
Still, the multistate settlement terms, along with ongoing legal and reputational pressure, could reshape how Credit Acceptance prices loans, accesses funding and grows its dealer relationships.
Find out about the key risks to this Credit Acceptance narrative.
Another View: Credit Acceptance Through A Cash Flow Lens
There is a different message coming from our DCF model. While the popular narrative points to Credit Acceptance trading below a $636.67 fair value, the SWS DCF model estimates the future cash flow value at $339.48. The current $542.82 price sits well above that mark and points to an overvalued reading instead. Which version of “value” do you trust more, the story tied to earnings or the one built from cash flows?
Look into how the SWS DCF model arrives at its fair value. Look into how the SWS DCF model arrives at its fair value.
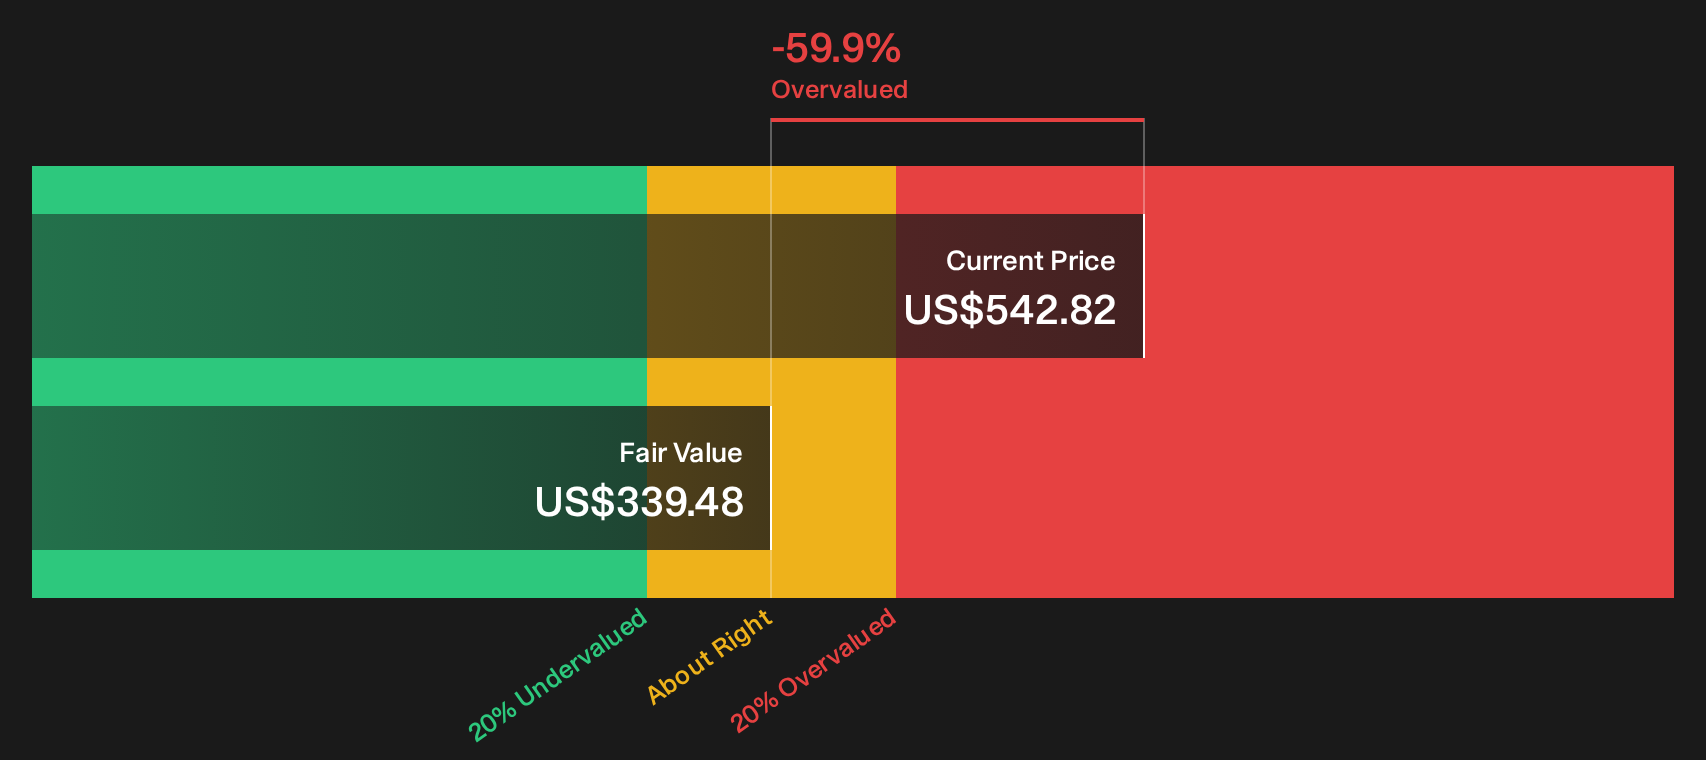
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Credit Acceptance for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Credit Acceptance so far. To move quickly and assess the balance of concerns and potential upside for yourself, start with 3 key rewards and 2 important warning signs.
Looking for more Credit Acceptance style investment ideas?
Ready to widen your opportunity set beyond Credit Acceptance and quickly compare fresh ideas that fit clear, data backed themes built from the same toolkit.
- Target resilient compounding potential by scanning companies that still trade below their assessed worth through the 27 high quality undervalued stocks.
- Prioritise income today by reviewing businesses with stronger yields and payout profiles using the 8 dividend fortresses.
- Strengthen your downside protection by focusing on companies with sturdier finances via the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com