
Is JBT Marel (JBTM) Cheap On Its Automation Growth Story?
Recent share performance and what it might signal
JBT Marel (JBTM) has quietly slipped over recent months, with the share price down about 9% over the past month and 23% over the past 3 months, and roughly 25% lower over the past year.
That slide sits alongside a 1-year total shareholder return that is down 25.1%, while the 3-year total shareholder return is slightly positive. This suggests JBT Marel’s recent share price pressure reflects a cooler view on near term prospects rather than a broken long term story.
Scan beyond JBT Marel and identify other industrial players that are under pressure but show improving fundamentals using our curated list of list of solid balance sheet and fundamentals (25 results).
JBT Marel appears to be a solid industrial platform on paper, yet the share price slide raises a sharper question. Are investors now being offered a high quality business at a fair valuation, or simply a cheaper ticket to the same risks?
Most Popular Narrative: 37% Undervalued
JBT Marel's most followed valuation storyline pegs fair value at about $167 per share, well above the recent $105.36 close. This puts the spotlight on what would need to go right for that gap to close.
The ongoing global increase in protein consumption and demand for food safety/traceability is driving sustained investment in automation and integrated processing solutions, supporting a robust order backlog (notably in poultry and meat), which is likely to provide multi-year revenue growth.
Labor shortages and rising labor costs across food processing are accelerating capital expenditure on automation and yield-enhancing equipment, an area where JBT Marel is seeing strong demand and is poised to capture greater market share, underpinning future topline growth.
See why 3 investors see JBT Marel as 37% undervalued.
Result: Fair Value of $167.06 (UNDERVALUED)
Still, JBT Marel’s story can change quickly if merger integration drags on or if tariff and supply chain pressures start to bite harder than analysts model.
Find out about the key risks to this JBT Marel narrative.
Another View: What JBT Marel’s P/E Is Telling You
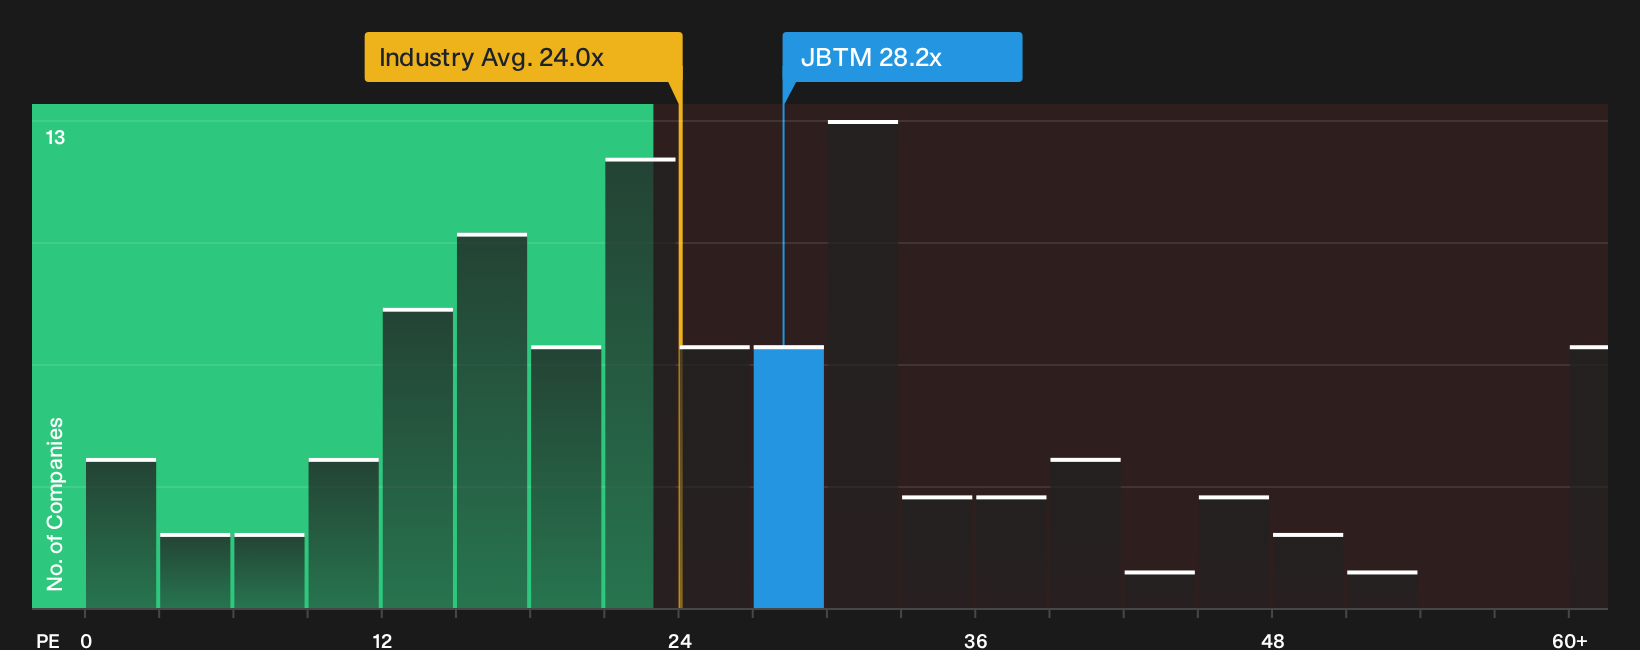
The analyst narrative leans on a DCF style path to $167, yet the current P/E tells a cooler story. JBT Marel trades around 28.2x earnings, above the US Machinery sector on 24.3x, even though its own fair ratio is pegged at 43.8x.
That mix of richer pricing than the wider industry but cheaper than its fair ratio points to a simple trade off. Investors are paying up versus peers for JBT Marel today, while the fair ratio suggests the multiple could move higher if the story plays out. Which side of that gap do you trust more right now?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone on JBT Marel leaves you undecided, it may be helpful to quickly review the full risk and reward picture for yourself with 3 key rewards and 1 important warning sign.
Looking for more JBT Marel sized investment ideas?
Do not stop with JBT Marel. Use this as a springboard to hunt for other opportunities that fit your style before the next round of results reshapes the field.
- Target potential mispricing across the market and shortlist candidates that blend quality with value through our curated 27 high quality undervalued stocks.
- Build a steadier income stream by focusing on companies with stronger payout profiles using the hand picked 8 dividend fortresses.
- Dial down portfolio stress by concentrating on businesses with more resilient profiles identified in the focused 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com