
What Imperial Oil (TSX:IMO)'s CCS Partnership Means For Shareholders
- Imperial Oil, alongside Canadian Natural Resources, Suncor Energy, Cenovus Energy and ConocoPhillips Canada, has agreed to advance the Pathways Carbon Capture and Storage project, a shared system that targets capture of about 6 million tonnes of CO2 annually by 2035 and a potential 16 million tonnes per year by 2045, subject to future binding agreements and approvals.
- In the same period, Imperial Oil was described as a value-focused operator with a P/E of 11.04 and a Value Score of B. Combined with its role in a large CCS buildout, this highlights how the business is trying to link long term oilsands production plans with lower emissions infrastructure.
- The next area of attention will be how Imperial Oil's CCS partnership could influence the investment narrative that focuses on value and earnings momentum.
Scan how Imperial Oil's CCS push fits alongside other value-focused energy players by reviewing the hand-picked 7 high quality undervalued stocks in the sector and beyond.
What Is Imperial Oil's Investment Narrative?
To own Imperial Oil, you have to believe in a long lived Canadian integrated producer that can keep turning a large upstream and downstream footprint into steady cash, even if revenue and earnings are expected to drift lower by around 1% a year over the next three years. The Pathways CCS MOU fits that belief as a potential license to keep capital intensive oil sands operations running while addressing emissions, although it is still conditional and does not yet change near term production or pricing realities.
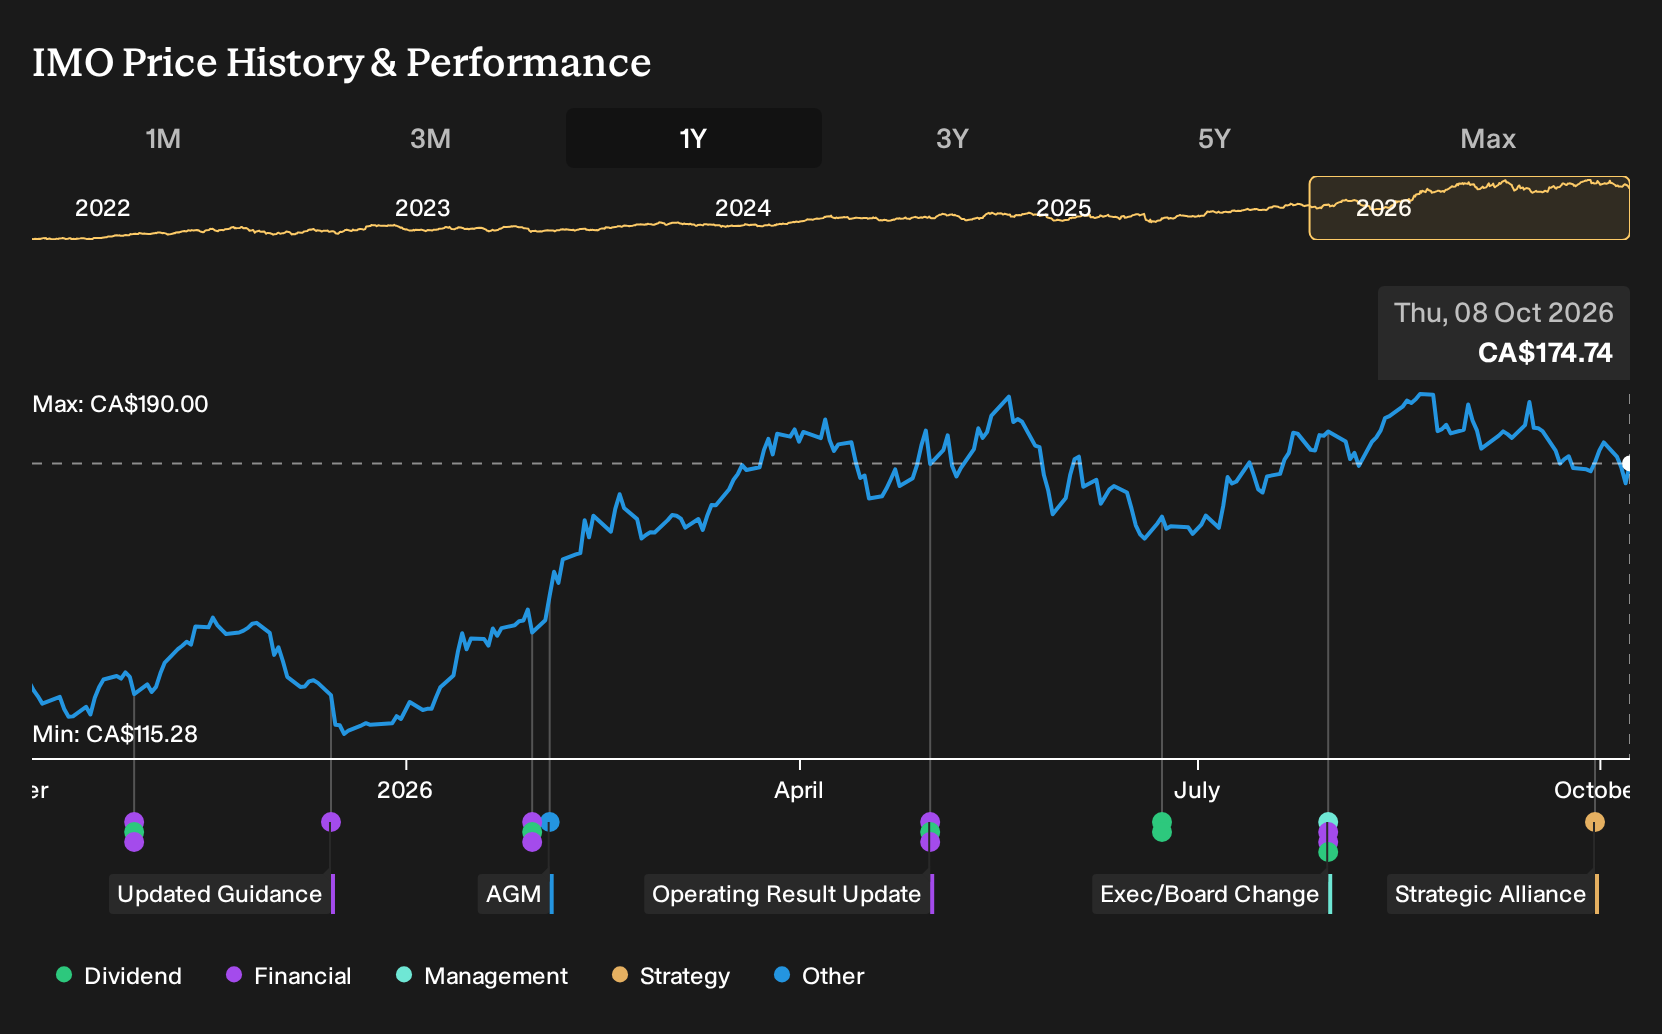
Short term, the key swing factors stay familiar: refining and marketing margins, execution on heavy maintenance and project timing, and discipline on big ticket spending matter more to near term earnings than a CCS project that is still years from a final investment decision. With Imperial Oil trading on a P/E of 11.04, offering a 1.99% dividend and flagged as trading well below one estimate of future cash flow value, the tension between a value story and forecasts of modest earnings decline is what really shapes the risk reward trade off right now.
Even so, there is a less obvious pressure point in the Imperial Oil story that only becomes clear when you look at ...
There's only one way to know the right time to buy, sell or hold Imperial Oil. Head to Simply Wall St's company report for the latest analysis of Imperial Oil's Fair Value.
Exploring Other Perspectives
One alternate view treats the Pathways CCS project as a potential earnings accelerator for Imperial Oil. The most optimistic analysts were already modeling roughly 11% annual revenue growth and earnings of about CA$5.7b by August 2029 before this news. Those expectations could shift meaningfully; compare that upbeat scenario with your own assumptions.
Explore 3 other Imperial Oil fair value estimates, including one that suggests as much as 71% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Imperial Oil research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Imperial Oil. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Imperial Oil's overall financial health at a glance.
Looking For More Investment Ideas Beyond Imperial Oil?
If you want to pressure test your view on Imperial Oil and broaden your watchlist at the same time, use the Simply Wall St Screener to see how other businesses stack up on value, income, and balance sheet strength.
- For investors who want quality at a discount, start with a curated set of 7 high quality undervalued stocks that pair fundamentals with pricing support.
- If reliable income is your focus, scan a pool of 3 dividend fortresses that combine higher yields with detailed payout data.
- For capital preservation and resilience, filter companies through a 8 resilient stocks with low risk scores designed to highlight steadier balance sheets and lower risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com