
Is Paladin Energy (ASX:PDN) Undervalued Following Its Uranium Conference Update?
Conference spotlight and recent share performance
Paladin Energy (ASX:PDN) stepped into the spotlight on 7 October at the Global Uranium Conference 2026 in Adelaide, with Managing Director and CEO Paul Hemburrow outlining the uranium focused portfolio.
The presentation follows a weak month for the stock, with the share price down about 28% over that period and lower over the past 3 months. This naturally raises questions about how investors are weighing the company’s uranium assets.
Over the past year, Paladin Energy has seen its share price slip, with a 1-year total shareholder return down 5.1% and a steeper fall in recent weeks. This hints at fading near term momentum as investors reassess uranium sector risks and future project execution.
Scan uranium-exposed peers under pressure and see which ones still show up on our hand picked list of 16 nuclear energy infrastructure stocks.
For Paladin Energy, a 28% slide in a month can either hint at cracks in the uranium story or simply mark a swing in mood. The valuation numbers now on the table need a closer look.
Most Popular Narrative: 39% Undervalued
Against the last close at A$8.39, the most followed Paladin Energy narrative points to a fair value of A$13.65 using a 7.18% discount rate, which frames the recent share slide as only part of the story.
The addition of the high-quality Patterson Lake South (PLS) project, targeted for first production in 2031 and benefiting from compelling project economics and a globally strategic location, provides Paladin with a clear pathway to long-term production growth, contributing to both asset value and future top-line expansion.
See why 83 investors see Paladin Energy as 39% undervalued.
Result: Fair Value of A$13.65 (UNDERVALUED)
Still, the bullish Paladin Energy narrative rests on some fragile beams, including long PLS permitting timelines and the chance of higher capital costs cutting into future returns.
Find out about the key risks to this Paladin Energy narrative.
Another view on Paladin Energy’s valuation
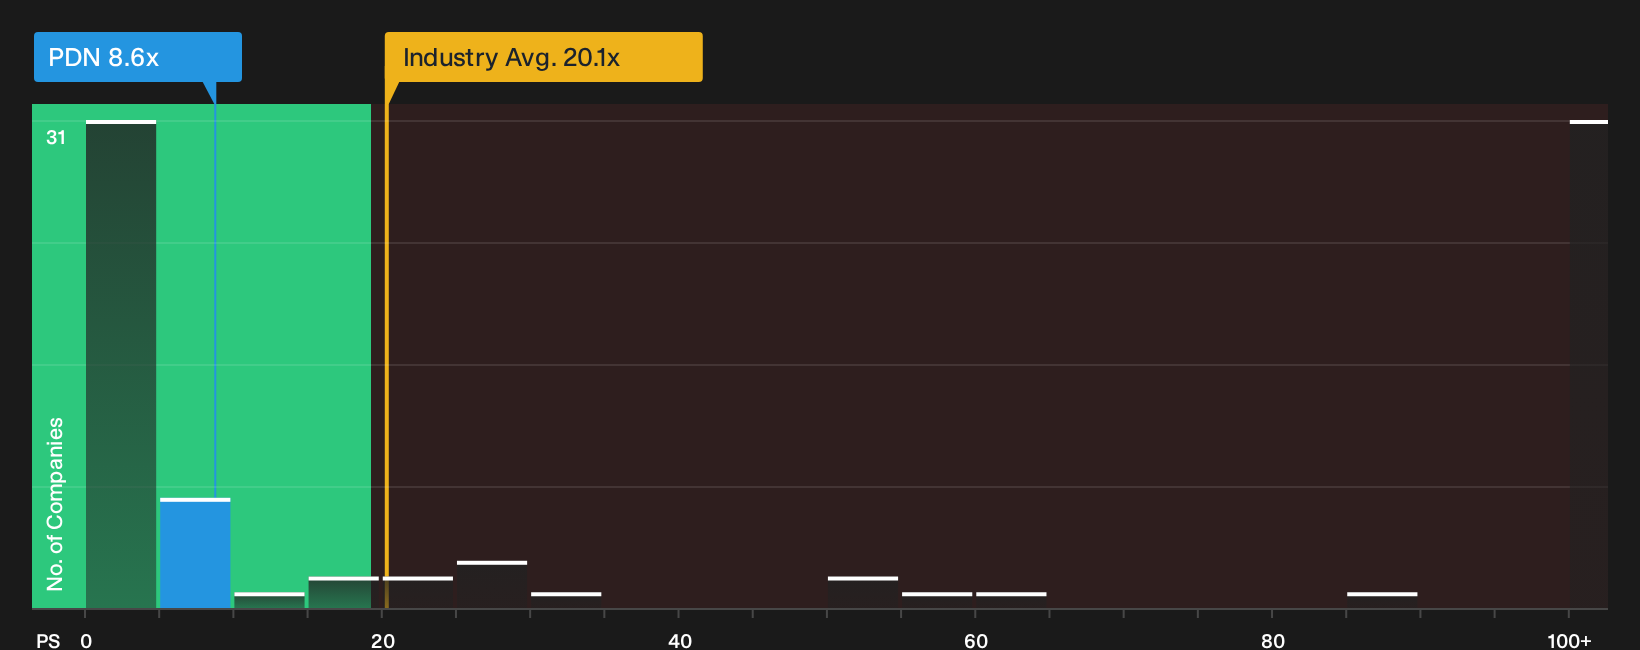
Analysts see upside for Paladin Energy using future earnings and a fair value of A$13.65, yet the current P/S ratio of 8.6x paints a tougher picture. That multiple is above the stock’s own fair ratio of 3.6x and sits below the Australian Oil and Gas industry at 20.1x. For investors, that mix of rich pricing versus fair ratio, but cheaper than the wider sector, raises a simple question: How much valuation risk are you really comfortable owning here?
To pressure test those expectations against hard numbers, take a look at the detailed valuation breakdown in See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the mixed mood around Paladin Energy leaves you torn between caution and curiosity, act promptly, review the available data, and decide for yourself with 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Paladin Energy?
Do not stop your research with Paladin Energy. Cast the net wider and use structured stock lists to spot opportunities that match your investing style.
- Target steady compounding potential by reviewing a 7 resilient stocks with low risk scores that focuses on businesses with more resilient profiles and lower risk scores.
- Hunt for mispriced potential by scanning a 15 high quality undiscovered gems that highlights under-the-radar companies with stronger fundamentals.
- Prioritise financial strength by working through a list of solid balance sheet and fundamentals (12 results) that filters for robust balance sheets and healthier fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com