
Is Argan (AGX) Trading At A Premium After JP Morgan's Call?
Argan has seen its share price climb at an exceptional pace over recent years, which puts a bright spotlight on whether the current US$398.66 level is properly supported by its earnings power. With that kind of run already on the board, the key issue for you is how much of the business performance story is already reflected in the valuation.
- Over the past 5 years the stock has delivered a very large gain, which raises the question of how closely the share price still tracks the underlying earnings profile.
- JP Morgan recently maintained its Overweight rating on Argan while trimming its price target, which signals that expectations for the engineering and construction group's future profitability and cash generation still play a central role in how the market is thinking about the stock.
- There is a second opinion on Argan worth weighing. See what analysts think Argan's shares could be worth.
The issue now is whether Argan's recent share price level is justified by the earnings the business is generating today and is expected to produce in the future.
If you want a better feel for how Argan compares on this kind of earnings driven story, compare it to companies in the 27 high quality undervalued stocks
Is Argan Getting Expensive on Earnings?
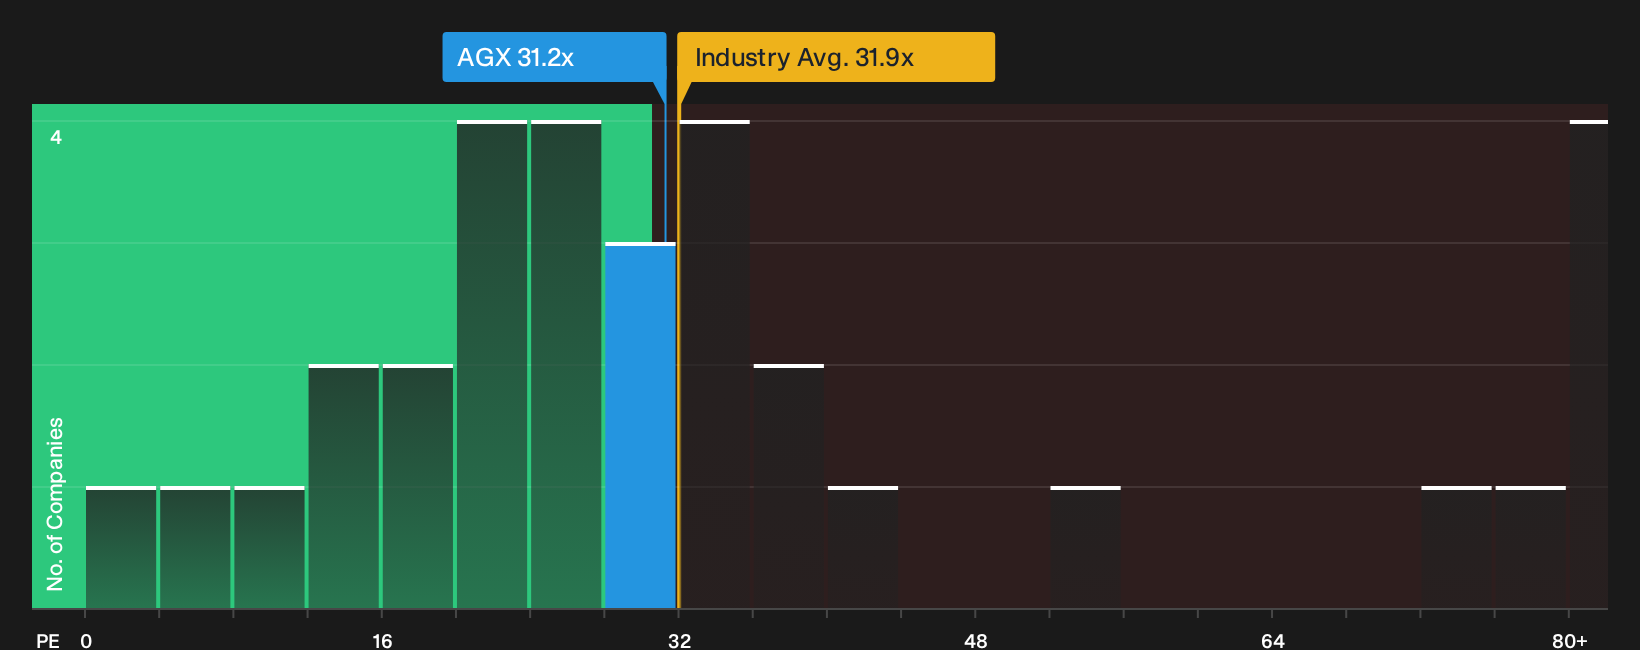
The P/E ratio suits Argan because earnings sit at the centre of how investors are framing the story here. On this lens, the stock trades on a P/E of 31.2x, which is very close to both the Construction industry average of 31.9x and the peer group mark of 32.0x, so the share price is broadly aligned with how similar businesses are being valued on current profits.
The fair value model suggests a lower P/E would be more consistent with Argan's mix of profitability, growth assumptions and risk, so on this framework the shares screen overvalued. Despite JP Morgan's recent Overweight rating helping to lift sentiment, the current multiple still prices Argan at a premium to what this tailored benchmark implies. Explore the numbers behind Argan's P/E valuation.
The Argan Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where the P/E debate for Argan leaves off, by spelling out which expectations for growth, margins and earnings would need to hold for the stock to be worth materially more or less than it is today on the market. Rather than relying on a single multiple or one output from a model, each scenario lays out the assumptions driving its fair value so you can compare those inputs with Argan's reported results over time.
Community views on Argan split between those who see long power demand supporting more upside and those who think crew limits and contract risk cap the opportunity.
Bull case: 30% undervalued
"Record backlog and continued project wins across gas, renewables, water treatment, and recycling plants provide multi-year revenue visibility..."
Discover why this Narrative puts Argan at 30% undervalued.
Bear case: 46% overvalued
"Several bearish analysts point to a ceiling on available crews at Argan, viewed as a structural cap on how much work the company can realistically take on..."
Explore why this Narrative puts Argan at 46% overvalued.
One more big question for Argan that this valuation has not answered
Price multiples and scenario debates only tell part of the story, because the next piece is how professional analysts currently sketch Argan's profit profile a few years from now. Explore where analysts expect Argan to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com