
Has Sunrun (RUN) Fallen Far Enough To Sit Below Fair Value?
Sunrun shares have retreated sharply in recent years, which puts fresh focus on whether the current valuation properly lines up with the earnings power of the residential solar business. With the stock now far below earlier levels, the key issue is how much of Sunrun's profit potential is already reflected in the price.
- Over the past 5 years, Sunrun's share price has fallen 84.6%, which raises the question of how the market is weighing its ability to turn its installed base and new customers into durable earnings.
- The company relies heavily on long dated customer contracts and financing structures, which can support revenue visibility but also makes the timing and quality of reported earnings central to how investors judge the stock.
- There is a second opinion on Sunrun worth weighing. See what analysts think Sunrun's shares could be worth.
The issue now is whether today's Sunrun share price is justified by the earnings it is generating and is expected to produce.
If you are weighing Sunrun's earnings story against alternatives, it can help to compare it with other companies using the same theme by scanning 43 power grid technology and infrastructure stocks.
Is Sunrun a Bargain on Earnings?
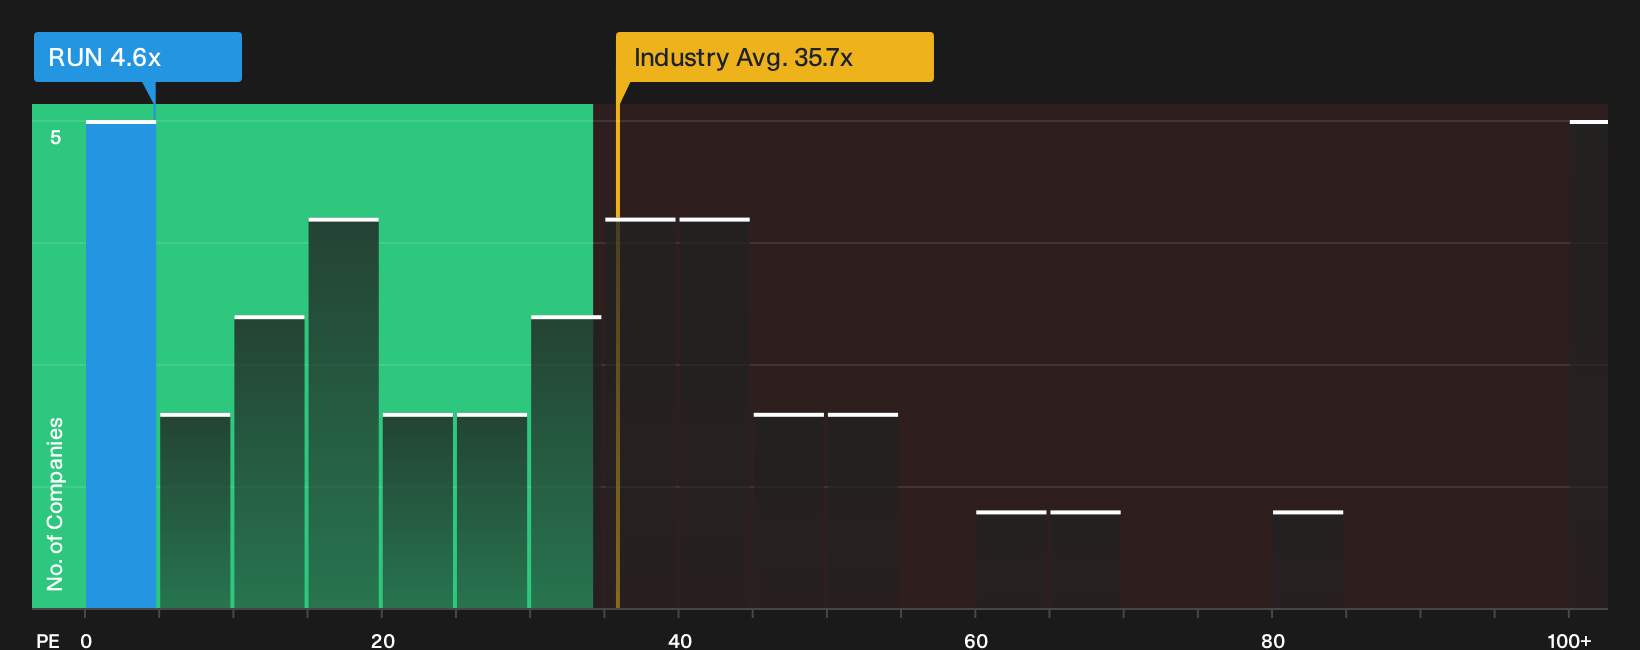
The P/E ratio is a useful lens for Sunrun because investors often focus on earnings when judging companies with long term contracts. On this measure, the stock trades on a P/E of 4.6x, which is far below the Electrical industry average of 35.7x and also well under the wider peer group on about 41.3x. That gap indicates the market is attaching a much lower earnings multiple to Sunrun than to comparable businesses.
The fair value framework, which looks at factors such as growth profile, profitability, scale and risk, points to a higher P/E than where Sunrun trades today. That leaves the current 4.6x multiple at a discount to what this model would suggest, although the headline number still needs to be weighed against the quality, stability and accounting of the earnings that generate it. Explore the numbers behind Sunrun's P/E valuation.
The Sunrun Narrative: What Would Justify Today's Price?
Narratives on Sunrun's Community page pick up where the valuation puzzle leaves off and spell out which paths for future growth, margins and earnings would need to play out for the stock to be worth materially more or materially less than it is today. Each scenario links a fair value estimate to a specific storyline about Sunrun's possible catalysts and key risks so you can track over time which version seems closest to reality.
One of the top community narratives on Sunrun: 60% undervalued
"Sunrun embodies the tension at the heart of the energy transition, massive long-term demand constrained by short-term financial realities..."
Discover why this Narrative puts Sunrun at 60% undervalued.
Sunrun’s share price is only one piece of the decision
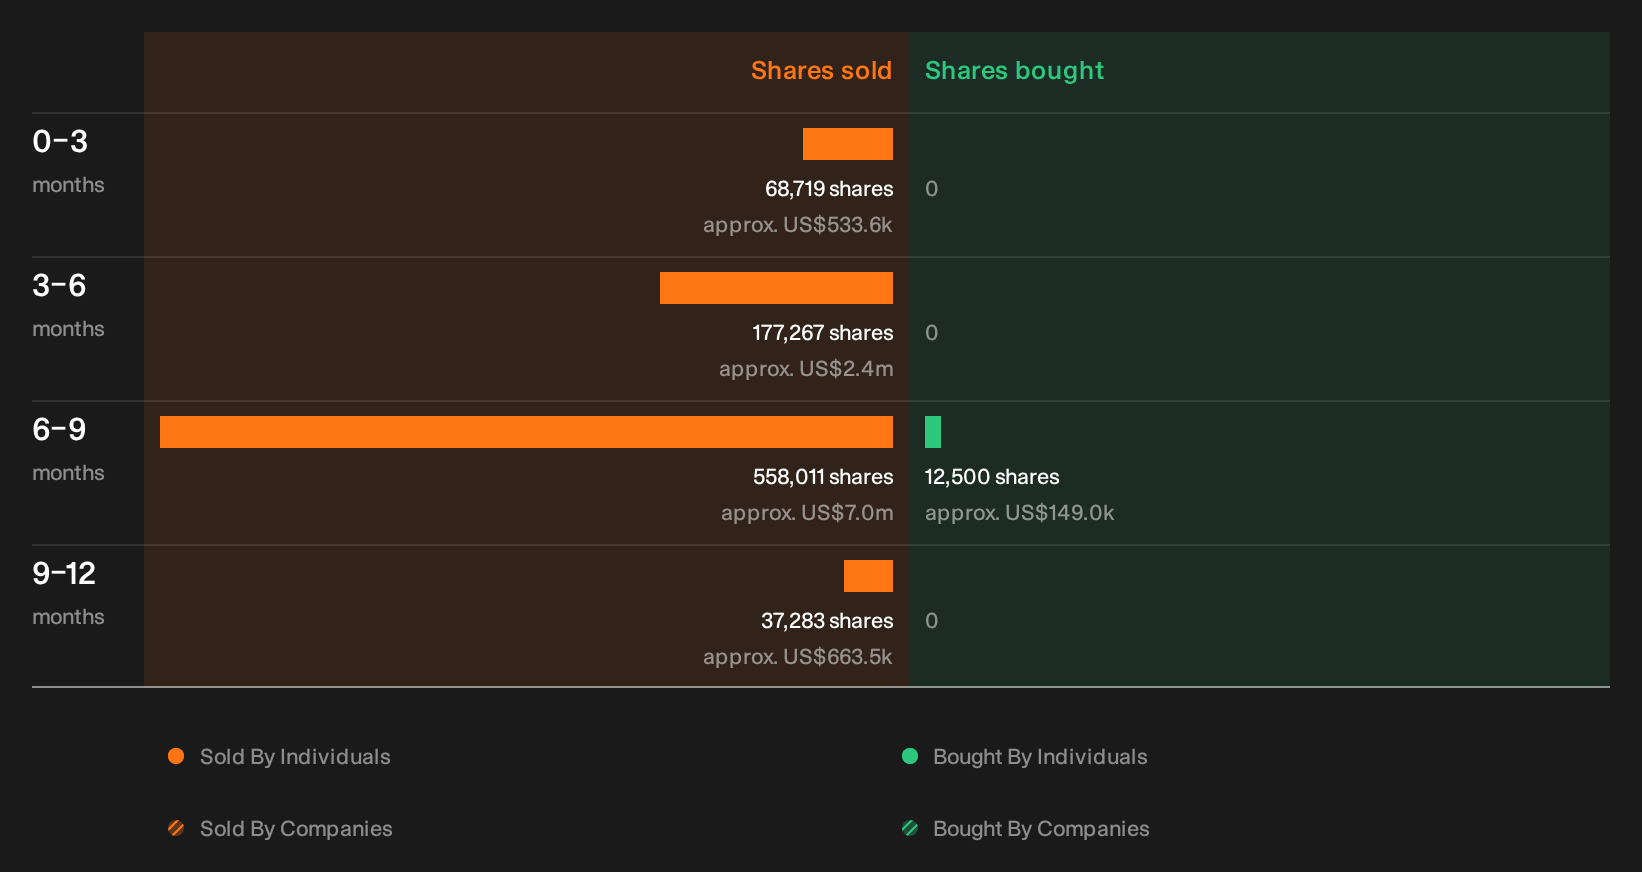
Valuation tells you what the market is willing to pay, but it does not explain what Sunrun’s own executives have been doing with their holdings. Recent trading by key insiders is the next thing to check. See the recent insider selling flagged for Sunrun.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com