
IPG Photonics (IPGP) Stock Looks Expensive Given Its Current Earnings Profile
IPG Photonics has seen its share price struggle over the longer term, which puts a spotlight on whether today's valuation is still supported by the earnings the business generates. For anyone tracking the stock, the real puzzle is how that earnings picture lines up with where the market is currently pricing the company.
- Over the past 5 years, IPG Photonics has fallen 52.2%, which puts pressure on the case that its current earnings profile can support a higher long term payoff.
- The business model is heavily tied to monetising its laser technologies, so future returns may depend on how efficiently those products translate into sustainable profit margins and cash generation.
- The analysts covering IPG Photonics have run their own numbers. See what analysts think IPG Photonics's shares could be worth.
For investors, the debate is whether the present share price can be justified by IPG Photonics' current and expected earnings power.
If you want to test the same earnings question beyond IPG Photonics, you can compare it with a wider field of companies using our screener of 27 high quality undervalued stocks.
Is IPG Photonics Getting Expensive on Earnings?
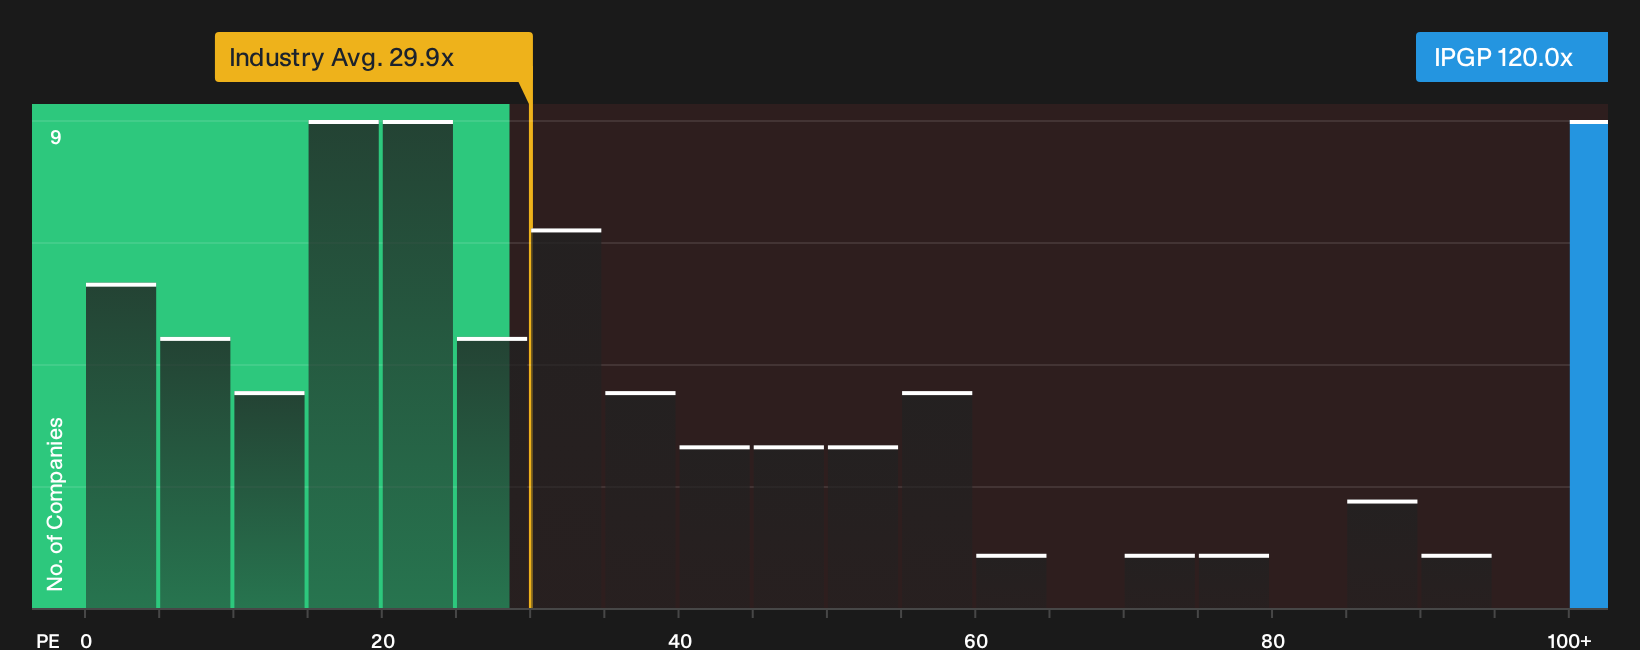
The P/E ratio fits IPG Photonics because its earnings are a primary way investors frame what they are paying for each dollar of profit. On this lens, the stock trades on about 120.0x earnings, which is much higher than the Electronic industry average of roughly 29.9x and also well above the peer group near 35.1x. That kind of gap signals the market is attaching a rich price tag to the current earnings base.
A tailored fair P/E multiple that blends IPG Photonics' growth profile, profitability, size and risk sits below where the shares currently trade, so on this framework the stock screens as overvalued. For anyone considering the ticker, the key judgement is whether the quality and resilience of its earnings stream genuinely merit paying such a premium over sector norms and peers. Explore the numbers behind IPG Photonics's P/E valuation.
The IPG Photonics Narrative: What Would Justify Today's Price?
Narratives for IPG Photonics on Simply Wall St's Community page pick up where the P/E puzzle leaves off, by spelling out which paths for growth, margins and earnings would need to play out for the share price to look meaningfully higher or lower than today. Instead of a single ratio or model giving one tidy number, Narratives lay out the future that number rests on so you can watch over time whether those conditions actually occur.
One of the top community narratives on IPG Photonics: 37% undervalued
"New growth initiatives in medical, semiconductor, and micromachining end-markets are gaining early traction, diversifying revenue streams and supporting higher margins over time…"
Discover why this Narrative puts IPG Photonics at 37% undervalued.
One last IPG Photonics check before you move on
Price tags and earnings only tell part of the IPG Photonics story, because our broader review has also surfaced potential pressure points that deserve a closer look before drawing your own conclusion. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com