
Is New World Development (SEHK:17) Undervalued After Its Full Year HK$26.16b Loss?
New World Development (SEHK:17) has drawn fresh attention after reporting a full year net loss of HK$26.16b, alongside lower sales and a deeper basic loss per share from continuing operations.
New World Development’s latest figures land after a rough stretch for the stock, with the latest HK$5.335 share price sitting against a 30 day share price return down 13.81% and a 1 year total shareholder return down 33.97%. This points to fading momentum as investors reassess both earnings risk and balance sheet flexibility following the 11 SKIES termination, the Victoria Dockside refinancing and the planned overhaul of its articles of association.
Compare New World Development’s reset with other property players under pressure and see which ones screen as potential rebounds in the 178 high quality undervalued stocks.
Bulls see New World Development as a beaten down asset play after a sharp sell off. Bears highlight deep losses and project exits. Which side does the current valuation evidence line up with next?
Most Popular Narrative: 21% Undervalued
On the most widely followed view, New World Development screens below its estimated fair value of HK$6.77, compared with the HK$5.34 last close, which puts the focus squarely on whether the balance sheet and earnings profile can support that gap.
The analysts have a consensus price target of HK$6.77 for New World Development based on their expectations of its future earnings growth, profit margins and other risk factors. In order for you to agree with the analysts, you would need to believe that by 2029, revenues will be HK$25.3 billion, earnings will come to HK$2.6 billion, and it would be trading on a PE ratio of 19.8x, assuming you use a discount rate of 13.0%.
See why 4 investors see New World Development as 21% undervalued.
Result: Fair Value of HK$6.77 (UNDERVALUED)
Still, if the Chinese property market strengthens and New World Development maintains robust K11 occupancy, this pessimistic narrative could unravel more quickly than many expect.
Find out about the key risks to this New World Development narrative.
Another View: Discounted Cash Flow Says Overvalued
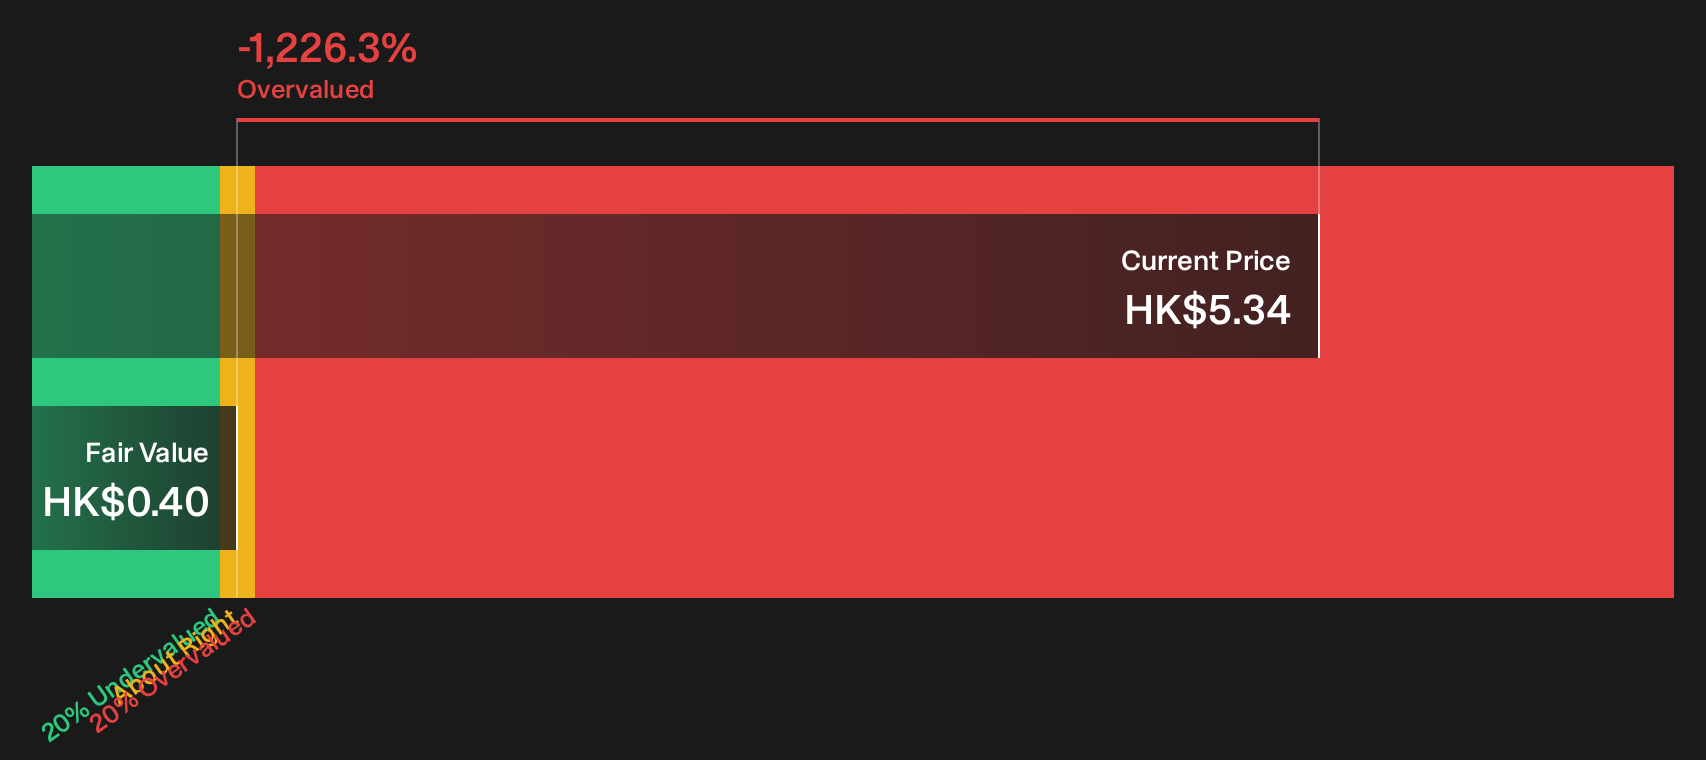
On the flip side of the fair value narrative, the SWS DCF model points to a very different conclusion for New World Development. At a HK$5.34 share price, the stock sits well above an estimated future cash flow value of around HK$0.40, which frames the shares as expensive rather than cheap.
This sort of gap suggests a practical question for any holder. Are you more comfortable leaning on analyst earnings assumptions and multiples, or on a cash flow model that paints far less room for error?
For readers who want to see how the moving parts of cash flows, discount rate and terminal value fit together, Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out New World Development for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 178 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages from New World Development’s valuation, losses and asset base mean sentiment is split, so move quickly and test the numbers yourself against the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond New World Development?
If New World Development has you rethinking your portfolio, use this moment. Fresh opportunities rarely wait around for investors who stay on the sidelines.
- Target resilient cash generators by reviewing companies on the list of solid balance sheet and fundamentals (206 results) that pair sturdier finances with clearer funding flexibility.
- Hunt for mispriced potential and scan the 619 high quality undiscovered gems where quieter stories may offer cleaner entry points than crowded large caps.
- Dial down portfolio stress and focus on stability using the 226 resilient stocks with low risk scores to filter businesses with more measured risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com