
TransMedics Group (TMDX) Stock Looks Like A Bargain As Its 183% Run Continues
TransMedics Group has given long term holders a strong ride over the past few years, yet the recent pullback raises a sharper question about what today's share price really asks you to pay for its earnings power. With the stock closing at US$79.00, the issue now is whether that level lines up with what the business is currently generating and expected to generate in profit terms.
- Over the past 5 years the stock has gained 183.3%, which puts a lot of weight on the idea that TransMedics' earnings profile can justify that kind of value creation.
- The business model depends on turning highly specialised organ care technology and related services into consistent profit, which can have a big impact on how investors think about the sustainability and quality of its earnings base.
- The analysts covering TransMedics Group have run their own numbers. See what analysts think TransMedics Group's shares could be worth.
The stock's next move may depend on whether TransMedics' current earnings level supports a share price of US$79.00 or asks investors to stretch their expectations.
If you want a broader context for TransMedics Group's recent swings, compare its earnings driven profile with companies in the same bracket using the 27 high quality undervalued stocks
Is TransMedics Group a Bargain on Earnings?
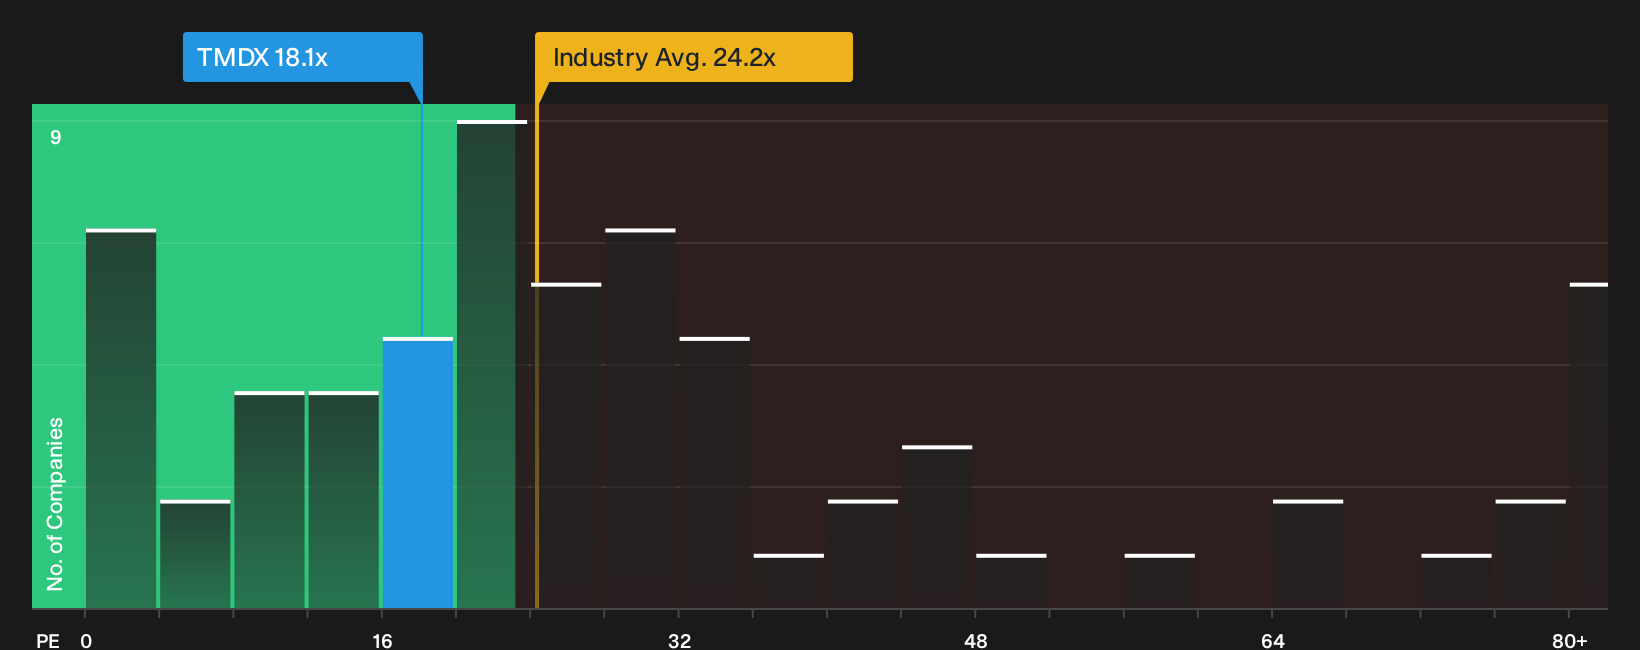
The P/E ratio suits TransMedics Group because profit ultimately drives what shareholders can take out of the business. On this yardstick, the stock trades on roughly 18.1x earnings, which sits below the wider medical equipment industry average of about 24.2x and also below the peer group level near 25.7x. For a reader, that indicates the market is currently paying a lower price for each dollar of TransMedics Group earnings than it is for many comparable healthcare equipment companies.
The Fair Ratio here reflects what a tailored P/E might look like once factors such as growth profile, margins, size and risk are blended into a single benchmark. TransMedics Group now changes hands at a multiple that sits under that customised yardstick, which points to a valuation that does not fully match the earnings profile implied by that framework. Those relative gaps do not settle the whole story around quality, execution or future capital needs, but they flag a starting point that appears more like a discount than a premium on current reported profits. Explore the numbers behind TransMedics Group's P/E valuation.
The TransMedics Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle for TransMedics Group leaves off by spelling out which combinations of future growth, profitability and earnings strength would need to hold for the stock to trade meaningfully higher or lower than today. Each one sets out a fair value as a specific, testable view on TransMedics Group's business so you can watch how that thesis matures over time on the Community page.
The TransMedics Group community is split between those who see a service heavy transplant platform that the market undervalues and those who think rising fixed costs already bake in too much optimism.
Bull case: 19% undervalued
"Development of a recurring, service-driven model is advancing as service revenue reached about US$79 million in Q2 2026 and TransMedics Logistics contributed roughly US$41 million while covering 86% of NOP air missions…"
Discover why this Narrative puts TransMedics Group at 19% undervalued.
Bear case: 22% overvalued
"While TransMedics Group is investing heavily in OCS Kidney, the roughly $14 million quarterly step up tied to kidney, next generation OCS and clinical programs risks proving structurally high if kidney utilization or pricing does not scale as assumed…"
Explore why this Narrative puts TransMedics Group at 22% overvalued.
One more TransMedics Group clue that lives outside today's multiples
Analyst models give a separate lens on where earnings and cash generation might head over the next few years, which lets you compare current pricing with how professionals frame the road ahead. Explore where analysts expect TransMedics Group to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com