
Trex Company (TREX) Gains Fresh Attention Following Earnings Upgrades And Its Undervalued Narrative
Trex Company (TREX) has returned to the spotlight after analysts raised their earnings consensus over the past two months, aligning that change with positive expectations for revenue and profit expansion this year.
Recent price action reflects that shift in sentiment. The share price is at US$44.44 after a 1-day share price return of 1.41% and a 7-day share price return of 2.16%, even though the 1-year total shareholder return has declined 15.34%. This signals near-term momentum for Trex Company, set against a weaker multi-year track record.
Scan how Trex Company compares with other construction and materials stocks showing earnings momentum by reviewing the hand picked 27 high quality undervalued stocks aligned with stronger fundamentals.
The recent bounce in Trex Company, alongside a share price that trails both intrinsic value estimates and analyst targets, raises a simple question: Is the real clearing price closer to the current quote or the projected range of fair values?
Most Popular Narrative: 19% Undervalued
Trex Company is trading at $44.44 against a widely followed narrative fair value of $54.67, which frames the current price as meaningfully below that longer term view of earnings power built on capacity, product breadth and free cash flow.
The buildout and ramp of the Little Rock facility, designed as Trex's lowest cost and most automated plant with modular lines and advanced recycling technology that can handle dirtier waste streams, is expected to support up to about US$1.8 to US$2.0 billion of core product revenue capacity and can influence future gross margin and EBITDA margin as utilization improves.
See why 6 investors see Trex Company as 19% undervalued.
Result: Fair Value of $54.67 (UNDERVALUED)
Still, the Trex Company story can come under pressure if the Little Rock ramp drags on margins or if higher SG&A spending absorbs more of each sales dollar.
Find out about the key risks to this Trex Company narrative.
Another View On Trex Company’s Valuation
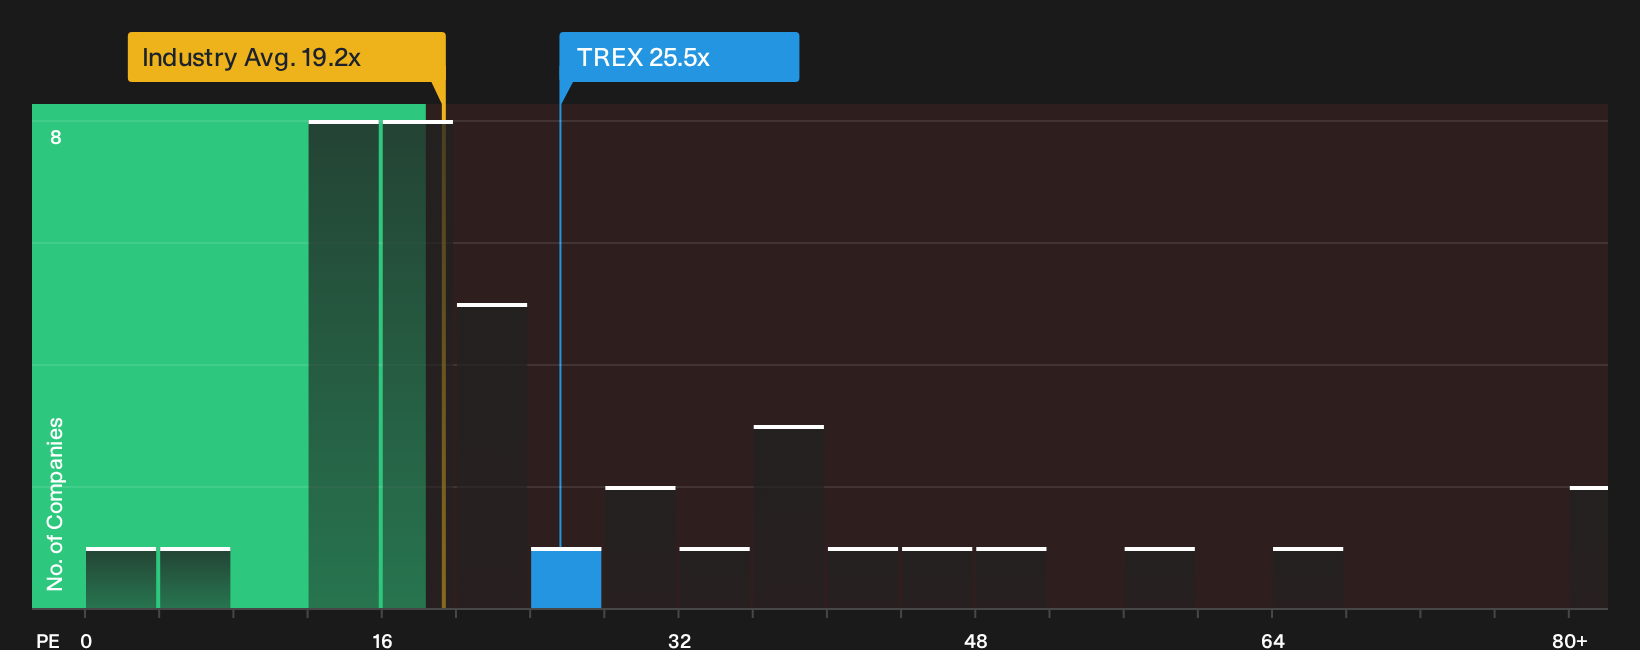
The first narrative leans on earnings power and analyst fair value, yet Trex Company trades on a P/E of 25.5x versus 19.2x for the US Building industry and a 21.8x fair ratio. That gap implies investors are already paying up, so is the perceived undervaluation really as generous as it looks?
To see how this pricing stacks up against peers and where the market P/E could shift over time, review the valuation breakdown built from this approach, including the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Optimistic about Trex Company after reading this, or still on the fence? Act while the data is fresh in your mind and weigh the 3 key rewards.
Looking for more investment ideas beyond Trex Company?
Consider looking beyond Trex Company alone. Broadening your watchlist can give you more options before the next set of opportunities changes.
- Explore potential opportunities by scanning a curated pool of mispriced quality businesses through the 27 high quality undervalued stocks.
- Strengthen your income stream by focusing on companies with robust payouts and resilience using the 8 dividend fortresses.
- Manage your downside risk by concentrating on companies with resilient finances via the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com