
Should AI Claims Expansion Require Action From WEX (WEX) Investors?
- WEX recently expanded its AI powered claims tool, automating a large volume of health benefit claims with high reported accuracy and aiming to tighten the operational backbone of its benefits platform.
- The broader roll out of this AI claims engine highlights how WEX is using automation to support efficiency, protect earnings durability and assess whether its current P/E near the industry average still aligns with underlying cash generation.
- This article will examine how WEX's investment narrative compares with this AI led claims expansion that targets faster, more accurate health benefit processing.
WEX Investment Narrative Recap
To back WEX as a shareholder, you need to be comfortable with a payments and benefits business that leans heavily on software, data and AI tools to keep earnings quality and cash generation aligned. The expanded AI claims engine fits that story, since it targets cleaner processing economics, which can support reported margins and help address concerns about high non cash earnings.
In the very near term, the key swing factor is whether WEX turns this automation into stable Benefits profitability, while Corporate Payments and Mobility keep pulling their weight despite fuel mix shifts and competition. The main risk is that rivals pressure fees in high growth AP and embedded payments, which could cap margin gains even if volumes hold up.
The latest AI powered claims expansion connects directly to earlier product work. WEX has highlighted an engine handling over 600,000 FSA claims at about 95% accuracy. What matters operationally is whether scaling that across more benefits flows reduces manual handling costs and error rates in a way that shows up in segment margins rather than just in marketing decks.
If this rollout lands well, it can sit alongside other cited catalysts such as SecureFuel and direct AP as proof points that WEX can use software driven services, not just volume growth, to support earnings. If it stumbles, investors will likely pay closer attention to existing risks around regulatory scrutiny, data security and reliance on a few large partner relationships for Mobility and Benefits revenue.
What The Current Consensus Implies For WEX
Analysts are effectively tying WEX's AI heavy benefits push to a broader set of expectations around growth, profitability and how much investors are willing to pay for those earnings. The current set of forecasts assumes revenue expands by 3.3% each year for the next three years, that profit margins lift from 12.6% to 16.9%, and that by 2029 the business earns US$519.6 million compared with US$350.7 million today. That move in profit would mean earnings rising by about US$168.9 million over the period, with the stock trading on a P/E of 16.2x those 2029 profits versus 16.4x today and below the 16.6x multiple cited for the broader US diversified financial peer group.
On the cash flow side, these projections assume the share count slowly shrinks by 0.6% a year over the next three years, helped by management directing more of its reported US$696 million to 700 million of adjusted free cash flow over the past 12 months into buybacks under a US$1b authorization. For investors tracking how WEX's AI powered claims engine and other software heavy offerings translate into per share outcomes, that declining share base matters because it can support earnings per share even if top line growth stays around the guided organic range instead of breaking meaningfully higher.
Those earnings and margin views are then plugged into a discounted cash flow style framework using an 8.82% discount rate in the Simply Wall St work, along with an assumed 16.2x P/E on the 2029 earnings estimate. All of that needs to line up for the current analyst price target to make sense on their numbers, which is why any material shortfall in revenue delivery, margin expansion or AI driven efficiency from areas such as the claims tool could push investors to rethink how much they are prepared to pay for WEX's future cash generation.
WEX's narrative projects US$3.1b in revenue and US$519.6 million in earnings by 2029, tied to revenue growing 3.3% per year and an earnings increase of about US$168.9 million from US$350.7 million today.
Uncover why WEX's fair value indicates a 12% potential upside to its current price that could narrow quickly.
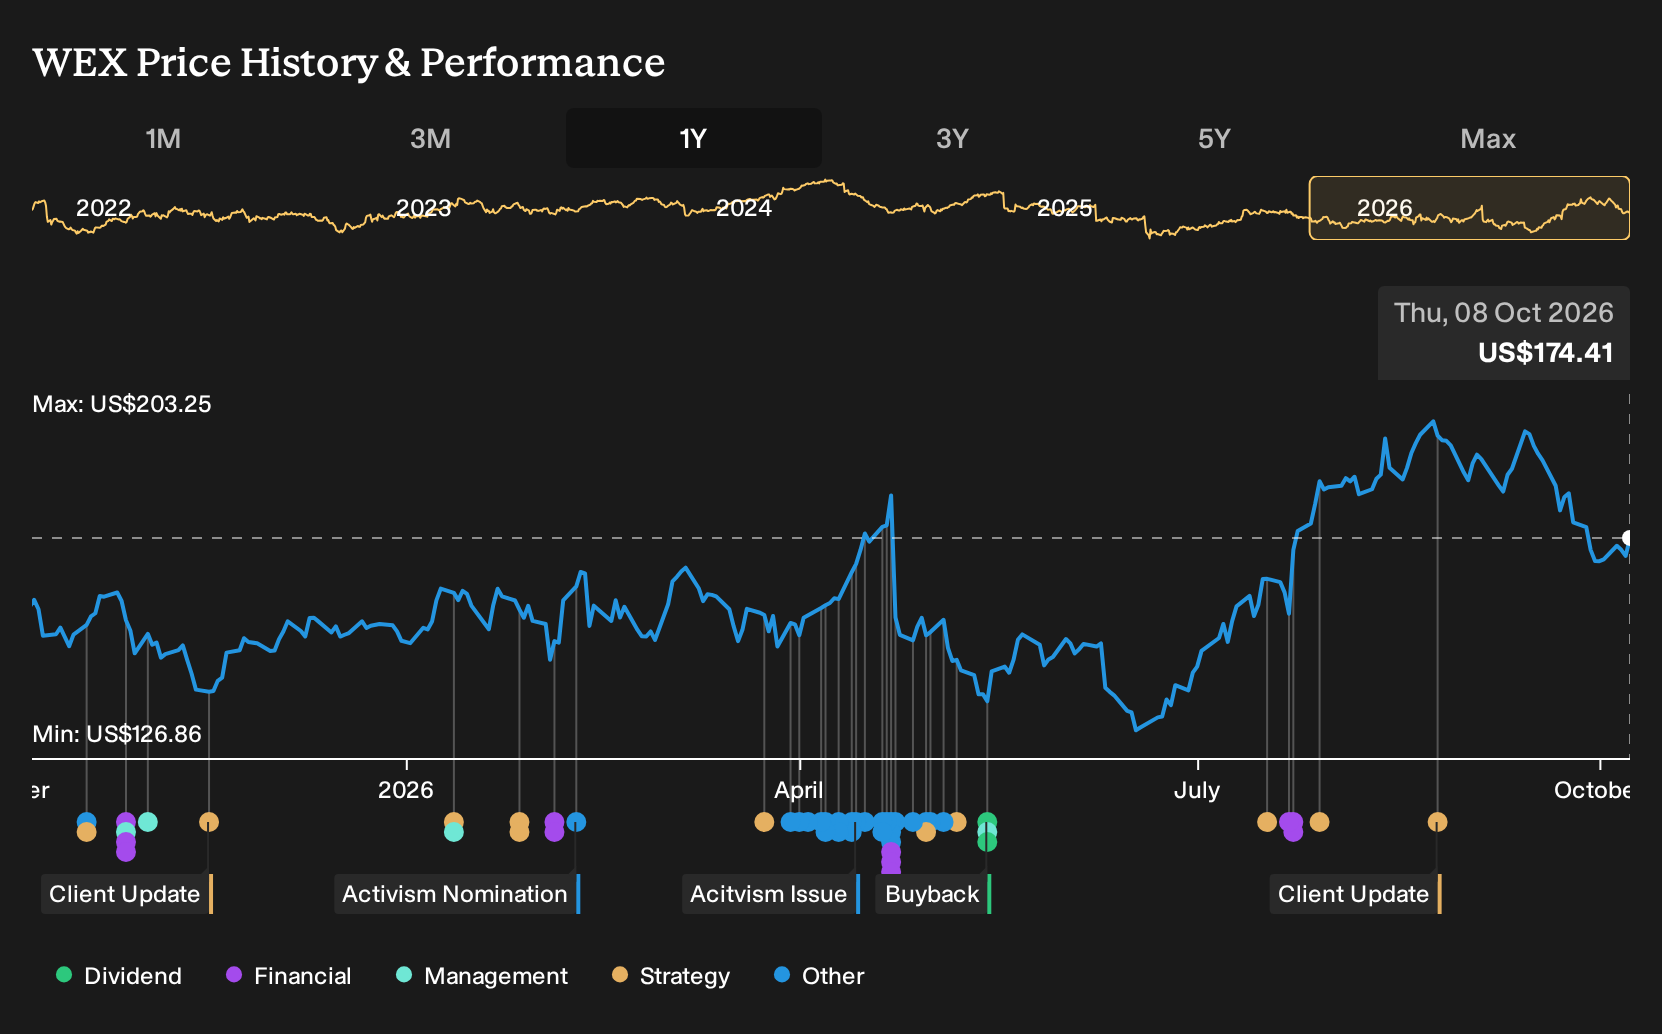
Exploring Other Perspectives
Pessimistic analysts focus on a different pressure point for WEX. They worry the slower embedded payments pipeline limits what AI tools and new claims automation can do for overall earnings. Before this news, the lowest forecasts pointed to about US$3.0b in 2029 revenue and US$478.0 million in earnings. That is already a more cautious story than the baseline. It shows how opinions can spread widely, and why you may want to compare both sets of expectations as this fresh AI rollout feeds into updated models.
Explore 3 other WEX fair value estimates, including one that suggests it could be worth just $195.36.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your WEX research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for WEX. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate WEX's overall financial health at a glance.
Looking For More Ideas Beyond WEX?
If you want to stress test your view on WEX against other possibilities, it helps to scan a broader universe of companies with clear financial traits. The Simply Wall St Screener lets you filter by balance sheet strength, income reliability and valuation so you can build a watchlist that actually reflects your own risk tolerance rather than just the current headline story.
- If capital protection is your priority, start with sturdier businesses by reviewing a list of solid balance sheet and fundamentals (25 results) that can help anchor a more conservative portfolio mix.
- If steadier income streams appeal more than headline growth, weigh up companies known for reliability by checking out a curated set of 8 dividend fortresses that may suit a cash flow focused approach.
- If you want a wider hunting ground for potential mispricing, scan a 20 high quality undiscovered gems and see which profiles line up with the factors you already like in WEX.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com