
American States Water (AWR) Faces A Valuation Test As Dividend Focus Returns
American States Water (AWR) is back in focus after fresh attention on its dividend profile, including a 2.68% yield and a five-year pattern of regular increases tied to earnings expectations.
American States Water’s share price has eased over the past month, with a 30-day share price return of a 7.72% decline and a 90-day return of a 3.17% decline. Yet year to date the share price is up 13.24%, and the 1-year total shareholder return of 14.74% points to momentum that has built over a longer stretch as investors weigh that earnings outlook and dividend profile.
Scan beyond American States Water to see how it stacks up against 8 dividend fortresses for income-focused portfolios anchored on yield and consistency.
After that mix of recent weakness and longer term gains, the real tension for American States Water holders is simple. Does the current valuation still leave enough upside for new buyers to be compensated for the risk being taken?
Most Popular Narrative: 2.6% Undervalued
On Simply Wall St's most followed narrative, American States Water screens as slightly undervalued, with a fair value of $84 against a last close of $81.83. That small gap is where the whole story about regulated returns, CPUC rules and dividend commitments has to do the heavy lifting.
The company is set to benefit from new customer growth and long-term recurring revenues as it expands service in newly planned California communities such as San Juan Oaks and Sutter Pointe, which are expected to add thousands of future connections and support higher regulated utility revenue over time.
See why 16 investors see American States Water as 3% undervalued.
Result: Fair Value of $84 (UNDERVALUED)
Still, the story around American States Water can change quickly if a California drought or usage swings affect consumption, or if dividend cash demands strain free cash flow.
Find out about the key risks to this American States Water narrative.
Another View: What Multiples Say About American States Water
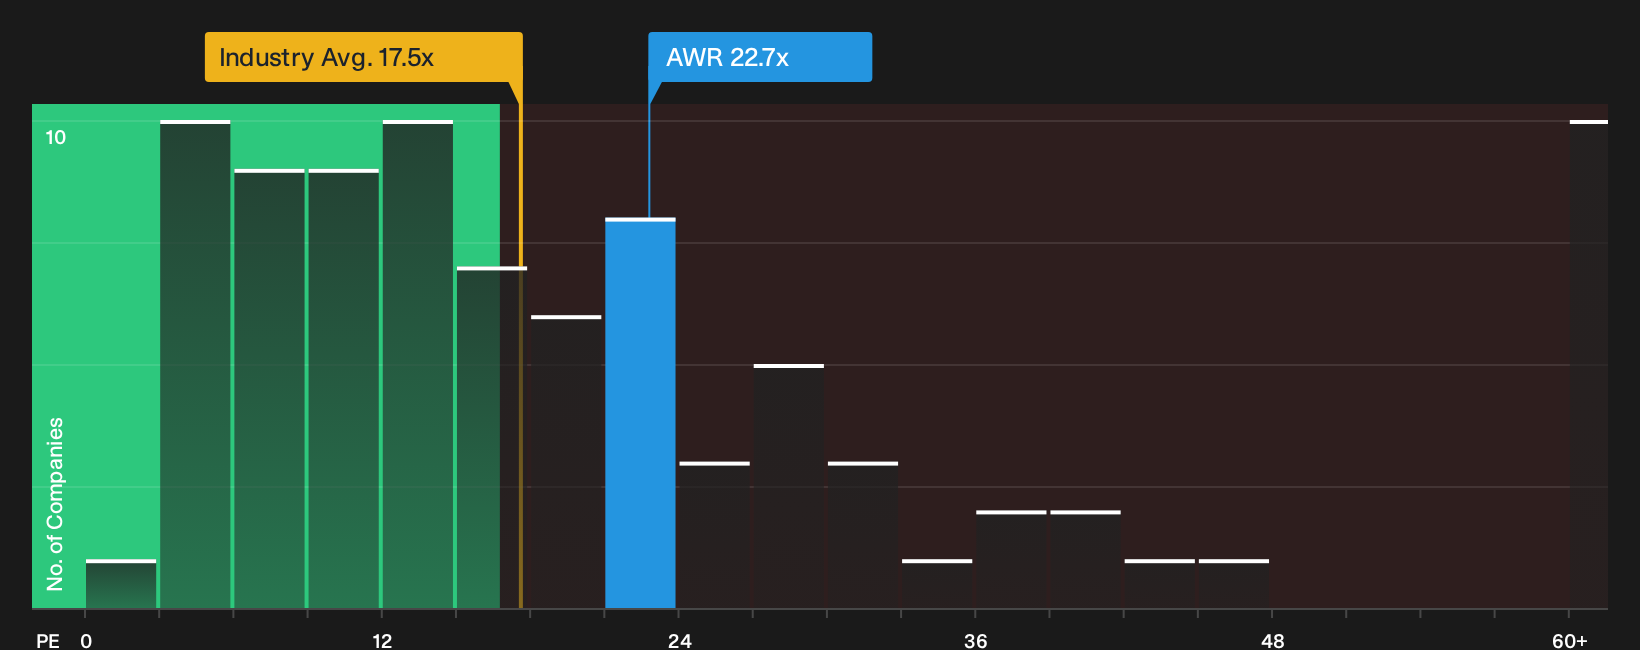
There is a different read on American States Water when you look at simple pricing ratios instead of fair value estimates. The stock trades on a P/E of 22.7x, which is higher than the global Water Utilities sector at 17.7x and above peers at 21.1x. It also sits above a fair ratio of 17.1x, which is where the P/E could drift if sentiment cools. That gap points to less margin for error if growth or regulation disappoints, so how comfortable are you paying that kind of premium for a regulated utility?
Before leaning too heavily on any one metric, it is worth seeing how that P/E premium, peer comparison and fair ratio fit into a fuller valuation breakdown, including cash flows and asset base, through the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on American States Water is mixed, with solid dividend appeal but clear questions around valuation and risk. Act quickly by reviewing both sides of the story for yourself through the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond American States Water?
If American States Water has you thinking harder about income, value and resilience, do not stop here. Use these focused stock ideas to sharpen your watchlist now.
- Target reliable income streams by scanning companies that feature in the 8 dividend fortresses and compare how their payouts and fundamentals line up with your goals.
- Hunt for quality at a sensible price by reviewing the 27 high quality undervalued stocks and see which businesses currently trade below their assessed worth with solid fundamentals.
- Protect your downside by filtering for financial strength through the list of solid balance sheet and fundamentals (25 results) so you are not caught holding fragile balance sheets when conditions change.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com