
Why Lindblad Expeditions Holdings (LIND) Is Back In The Spotlight
Recent Share Performance Puts Lindblad Expeditions Holdings In Focus
Lindblad Expeditions Holdings (LIND) is back on investor radar after a strong recent run, with the stock up about 34% over the past month and roughly 146% year to date.
That surge has arrived alongside annual revenue of about $830.6 million, a reported net loss of $20.3 million and a market value close to $2.3b, raising fresh questions about how the business is currently being valued.
The recent share price climb, with a 30 day share price return of 33.86% and year to date share price return of 146.12%, points to building momentum around Lindblad Expeditions Holdings as investors reassess its growth potential and risk profile in relation to the current valuation and long term total shareholder returns.
Scan beyond Lindblad Expeditions Holdings and see how other travel and experience operators with strong momentum stack up in the 20 high quality undiscovered gems.
Lindblad Expeditions Holdings now trades around the analyst price target after a sharp climb and still reports a loss. Does the balance of risk and potential reward from here justify fresh money going in?
Most Popular Narrative: 20% Undervalued
Lindblad Expeditions Holdings last closed at $35.54, while the most followed narrative pegs fair value around $35.60, using a 9.16% discount rate to weigh future cash flows and risks. The same storyline frames the recent price surge against a thesis that hinges on execution in experiential travel and improving profitability.
Ongoing growth in demand for experiential, adventure, and multigenerational travel highlighted by strong bookings, expanded youth/family programs, and the Disney partnership signals a secular tailwind that should drive future revenue growth and expanded occupancy rates.
Rising consumer focus on sustainability and responsible tourism, with Lindblad highlighting new sustainable initiatives (including vehicle fleet electrification and an upcoming ESG report), positions the brand to benefit from price premiums, customer loyalty, and higher net yields as environmentally conscious travel expands.
See why 5 investors see Lindblad Expeditions Holdings as 0% undervalued.
Result: Fair Value of $35.60 (UNDERVALUED)
Still, the Lindblad Expeditions Holdings story depends on affluent travelers remaining engaged and on royalty and compliance costs not eroding the path to stronger margins.
Find out about the key risks to this Lindblad Expeditions Holdings narrative.
Another View: Multiples Point To Richer Pricing For Lindblad Expeditions Holdings
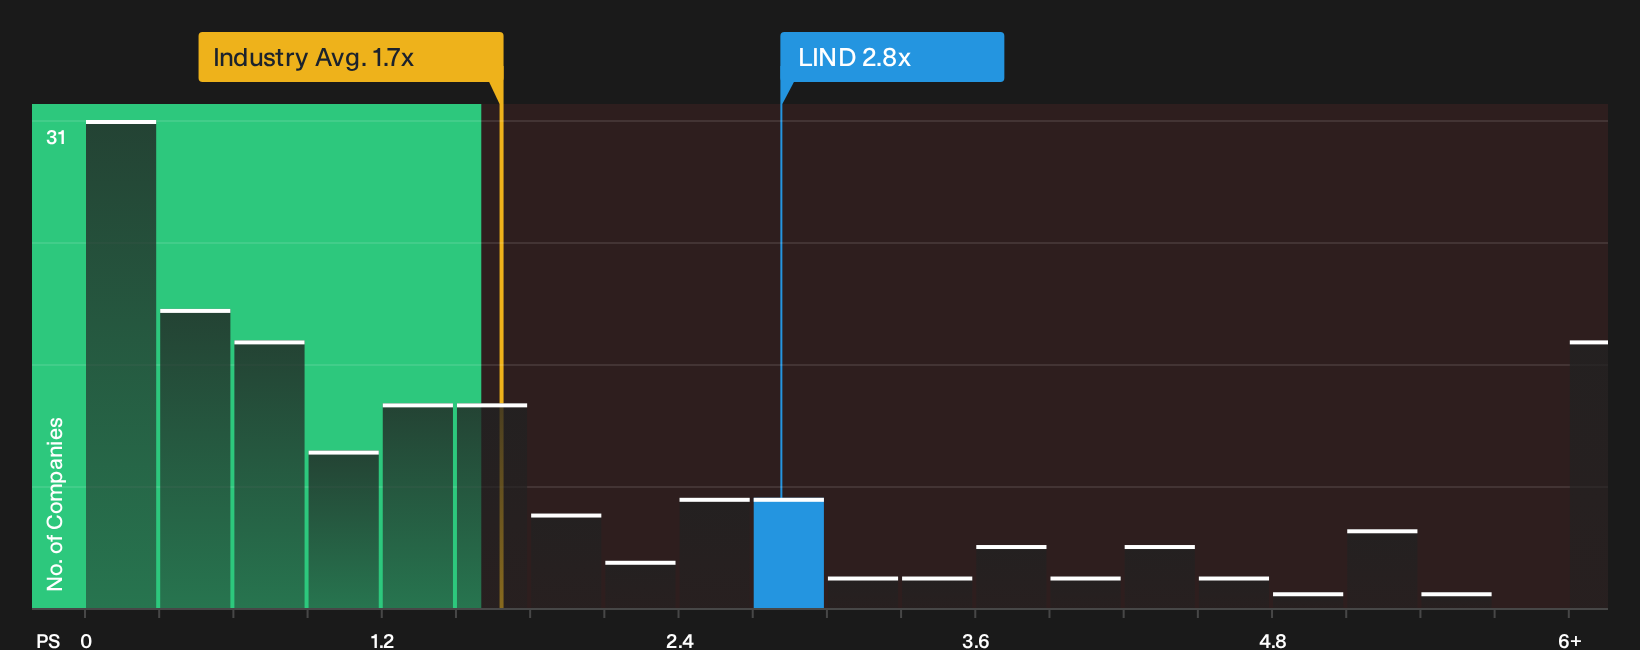
The fair value narrative paints Lindblad Expeditions Holdings as around 18% undervalued, yet the market is already asking a premium on sales. A P/S of 2.8x versus 1.6x for the US Hospitality group and a fair ratio of 1.2x suggests investors are paying up heavily for the story. Is that premium comfort or stretch for you as a shareholder?
To see how that gap in valuation multiples could shift, and what the numbers imply for both risk and potential upside, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed signals around Lindblad Expeditions Holdings leave you torn, that is exactly the point. To weigh the concerns against the upside case, review the 2 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Lindblad Expeditions Holdings?
If you stop your research with Lindblad Expeditions Holdings, you risk missing other opportunities with different risk profiles, income potential, and balance sheet strength across the market.
- Target potential turnaround stories with room to surprise by scanning the 10 elite penny stocks with strong financials that already show stronger financial footing than many expect.
- Focus on value by reviewing the 27 high quality undervalued stocks that combine solid fundamentals with prices that remain below what many investors might consider reasonable.
- Prioritise resilience and capital protection by checking the list of solid balance sheet and fundamentals (25 results) that pair financial strength with room for future optionality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com