
Will Returning Permian Volumes Change Targa Resources Stock Narrative
- Targa Resources is expected to post firm second half results, with management activity focused on higher Permian Basin volumes and the return of previously curtailed Waha linked throughput as extra takeaway capacity becomes available.
- The normalization of natural gas marketing after earlier market dislocations, combined with growing Permian infrastructure utilization, is drawing renewed analyst attention to how efficiently Targa Resources converts system volumes into cash flow.
- This article explores how Targa Resources’ investment narrative is shaped by expectations for stronger Permian volumes and returning curtailed throughput.
Scan other Permian linked plays that could benefit from similar volume and infrastructure themes by zeroing in on 43 power grid technology and infrastructure stocks alongside Targa Resources.
Targa Resources Investment Narrative Recap
Owning Targa Resources means buying into a build out story in the Permian and on the Gulf Coast, where more inlet volumes, fractionation capacity and LPG export capability are already in place or under construction. The latest update around firm second half expectations, helped by stronger Permian volumes and returning Waha linked throughput, speaks directly to that volume led narrative.
The key near term swing factor is how smoothly those additional molecules move through the Targa Resources system into fee based cash generation as natural gas marketing conditions normalize. The main operational risk is that heavy growth capex and a high debt load intersect with any slowdown in producer activity or fee pressure if infrastructure across the basin and coast proves overbuilt.
Recent commentary around higher Permian volumes and the return of curtailed Waha related throughput matters most when set against the longer list of growth projects already underway. New gas plants such as Copperhead, Yeti, Roadrunner and East Driver, together with the Speedway NGL system and LPG export expansion toward about 19 million barrels per month by late 2027, all rely on consistent feedstock.
For you as a shareholder or potential investor, the key question is how efficiently Targa Resources turns that growing physical footprint and record 7.2 billion cubic feet per day of Permian inlet volumes into durable cash flows while servicing elevated growth capex. Execution on Trains 12 and 13, the Delaware Express pipeline ramp and highly contracted LPG exports are closely linked to that outcome and to how much financial flexibility is available for dividends and buybacks if conditions tighten.
Targa Resources’ current analyst narrative points to revenues of US$29.5b and earnings of US$3.5b by 2029, built on assumed annual revenue growth of 20.8% and an earnings step up of about US$1.2b from US$2.3b today to that 2029 consensus figure.
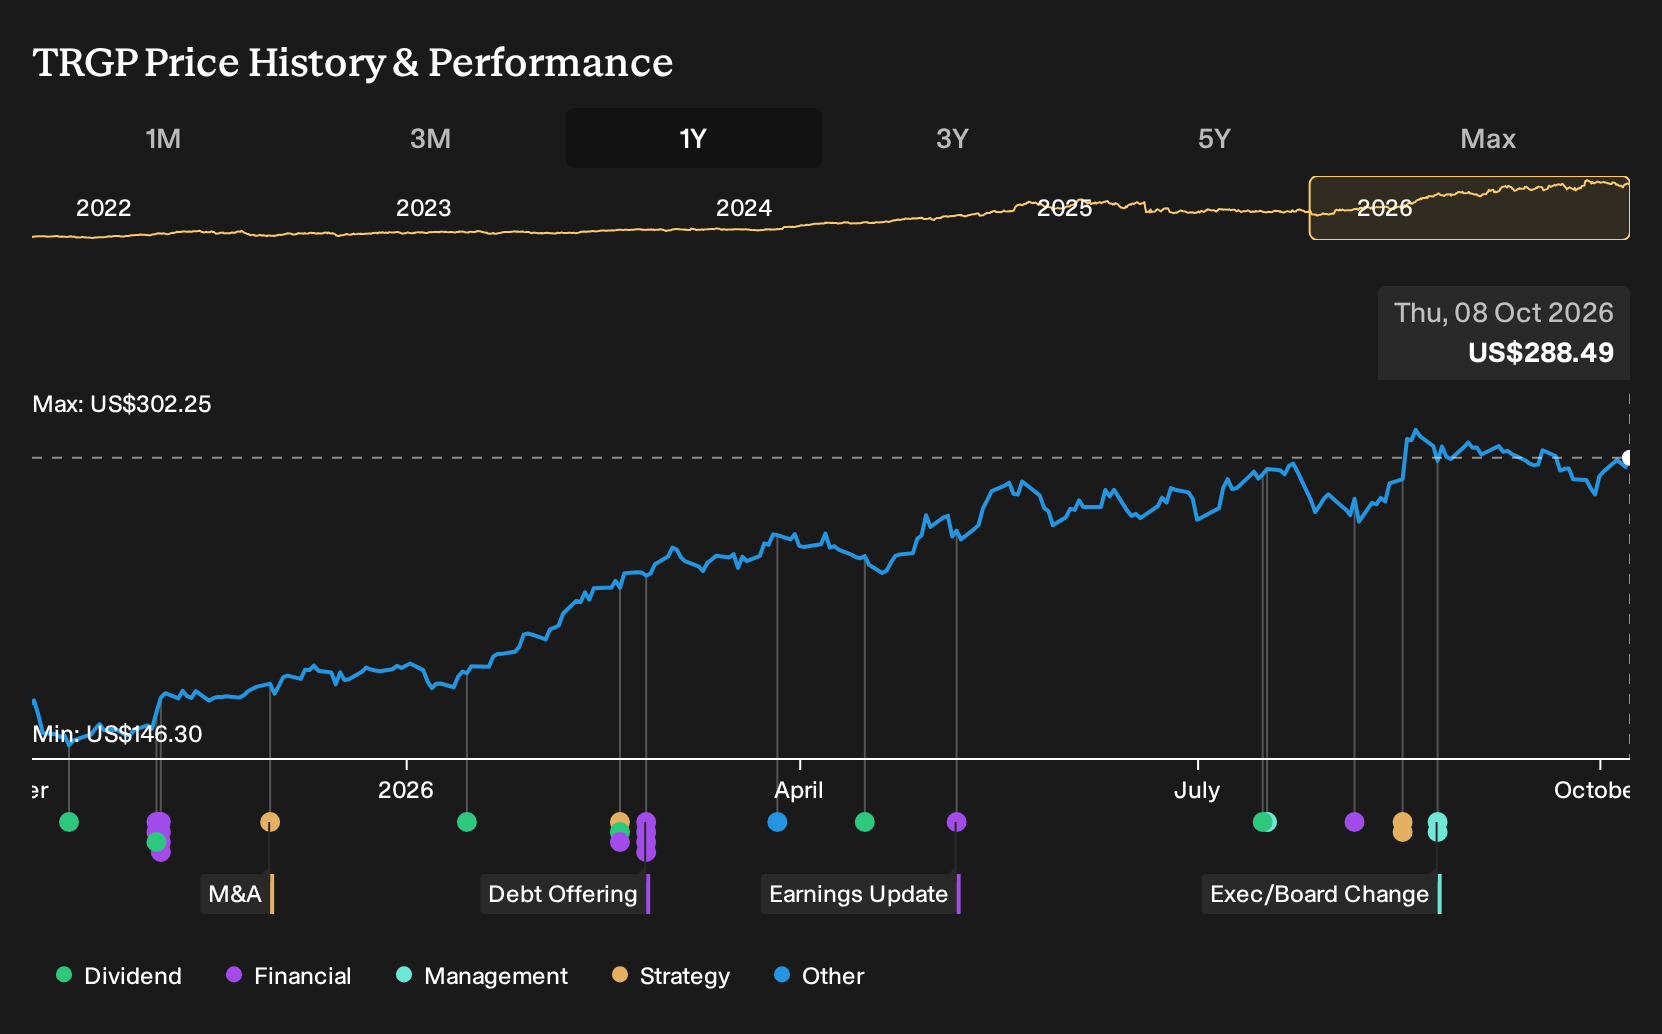
Uncover why Targa Resources' fair value indicates a 13% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$228 to US$544 per share, so some retail investors see Targa Resources as deeply undervalued while others price in a much richer future. Those views sit beside real risks around possible overbuild, heavy capex and the timing of any free cash flow uplift. Opinions clearly diverge; use this as a prompt to explore several contrasting viewpoints before you decide how Targa Resources fits your own portfolio plan.
Explore 2 other Targa Resources fair value estimates, including one that suggests as much as 89% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Targa Resources research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Targa Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Targa Resources' overall financial health at a glance.
Looking For More Investment Ideas Beyond Targa Resources?
If you want to stress test your thesis on Targa Resources and see how it stacks up against other potential opportunities, it helps to scan a broader field of companies that share similar quality or income traits.
- If capital preservation sits high on your list, start by reviewing a basket of 31 resilient stocks with low risk scores that score well on resilience and risk controls.
- For readers focused on dependable income, compare Targa Resources with a curated group of 8 dividend fortresses that pair higher yields with an emphasis on durability.
- If you are hunting for underfollowed opportunities with strong fundamentals, widen your research to a targeted set of 20 high quality undiscovered gems that may not yet be widely owned.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com