
TC Energy (TSX:TRP) Advances Coastal GasLink Phase 2, Is The Undervaluation Case Convincing?
TC Energy (TSX:TRP) just cleared a major hurdle, with Coastal GasLink Phase 2 moving ahead after LNG Canada’s positive final investment decision, nearly doubling pipeline capacity to serve long term LNG demand.
Recent trading suggests investors are reassessing TC Energy’s risk and growth mix, with the share price up 1.62% in the last session and 2.34% over the past week, even after a 10.50% decline over 90 days and an 11.07% year to date share price gain. The longer view looks very different, with a 20.32% one year total shareholder return and a roughly 13x gain over three years, which indicates that the Coastal GasLink Phase 2 decision is landing on top of already strong long term wealth creation rather than attempting to reverse a structurally weak story.
Scan for other pipeline and energy infrastructure plays that are showing similar momentum and execution by jumping into the hand picked 43 power grid technology and infrastructure stocks alongside TC Energy.
Bulls see Coastal GasLink Phase 2 locking in long haul cash flows. Bears focus on project risk and execution history. Which side does TC Energy’s current valuation actually support?
Most Popular Narrative: 15% Undervalued
TC Energy last closed at CA$85.36 while the most followed narrative pegs fair value at CA$100.77, which frames the LNG and pipeline expansion story as already priced below what that narrative views as justified.
Investors may be overestimating TC Energy's long-term revenue and EBITDA growth by assuming that the current surge in North American natural gas demand, driven by LNG export growth, coal-to-gas conversions, data center buildouts, and electrification, will persist at elevated rates, despite mounting global pressures for renewables and potential demand destruction for fossil fuels over the long run. Market optimism around new project announcements and sanctioned capacity additions may be ignoring structural risks from stricter climate policies and possible future carbon pricing, which could increase regulatory costs and compress net margins for pipeline operators like TC Energy.
See why 68 investors see TC Energy as 15% undervalued.
Result: Fair Value of CA$100.77 (UNDERVALUED)
Still, tighter climate policy or weaker long term gas demand could pressure TC Energy’s contract renewals and project returns, which would challenge the argument that the stock is undervalued.
Find out about the key risks to this TC Energy narrative.
Another View: TC Energy Through A Cash Flow Lens
Analyst targets suggest TC Energy trades below a CA$100.77 fair value, yet our DCF model presents a very different picture. On that framework, the future cash flow value sits at CA$33.04 per share, which implies the current CA$85.36 price appears expensive rather than cheap.
This split between a higher P/E based target and a much lower cash flow estimate raises a practical question for you. Are you more comfortable relying on earnings multiples that can move with sentiment, or a stricter cash flow test that leaves less room for optimism about long term project economics and financing costs?
Look into how the SWS DCF model arrives at its fair value.
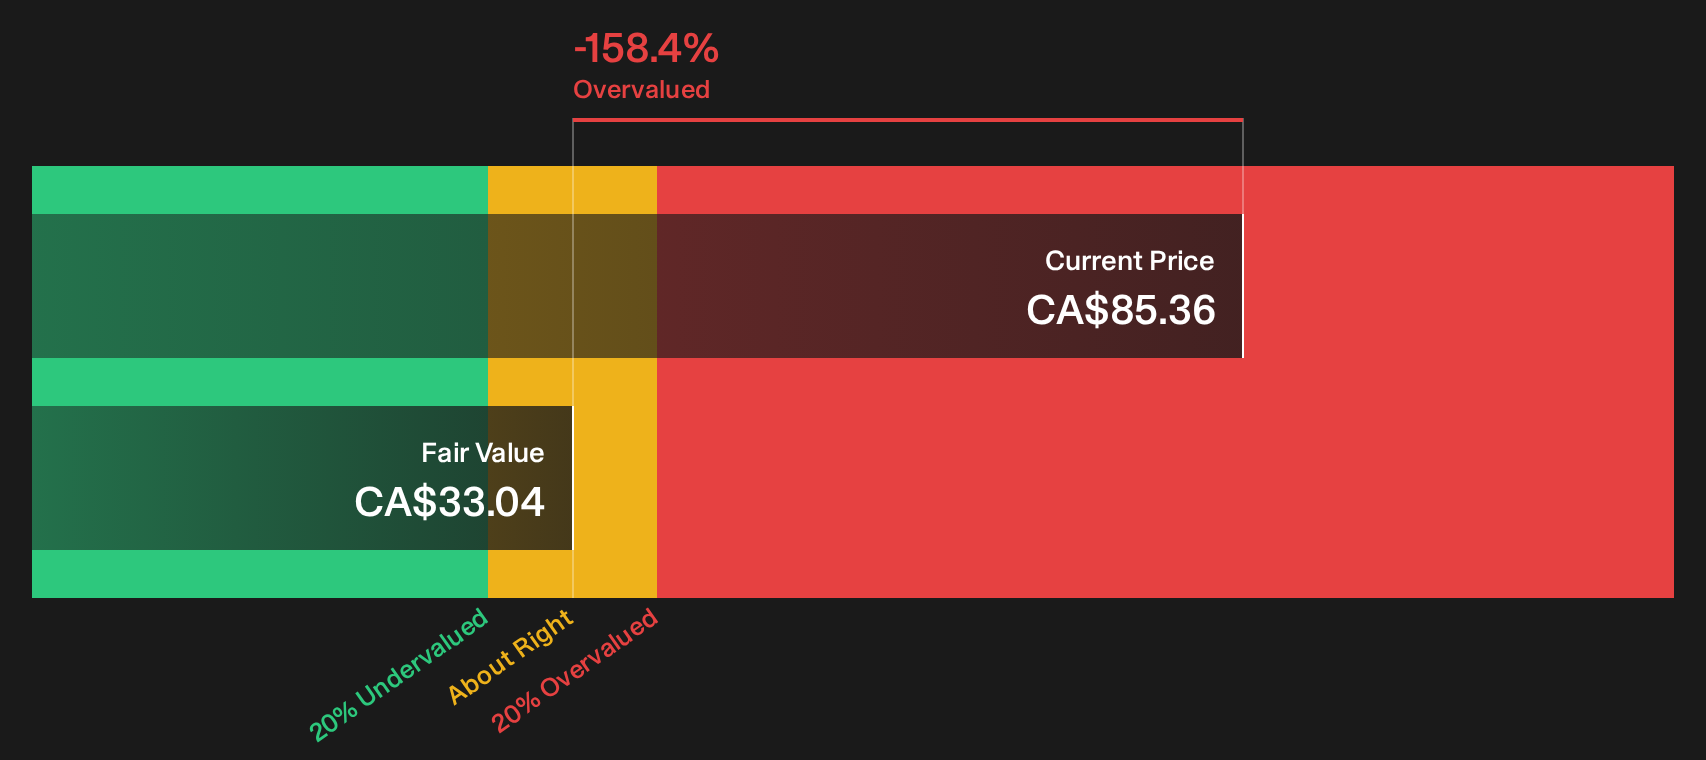
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out TC Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 7 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed views on TC Energy so far. Step into the data while sentiment is split and build your own call using the full picture in the 1 key reward and 2 important warning signs.
Looking for more TC Energy style investment ideas?
TC Energy is just one piece of your portfolio puzzle, so broaden your opportunity set now and let objective numbers guide where you commit fresh capital next.
- Target potential mispricing by scanning companies that combine solid fundamentals with attractive valuations using the 7 high quality undervalued stocks.
- Build a steadier income stream by focusing on businesses that aim to pair higher yields with resilient operations through the 3 dividend fortresses.
- Dial down portfolio stress by concentrating on businesses that carry stronger balance sheets and healthier fundamentals in the list of solid balance sheet and fundamentals (7 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com