
Guidewire Software (GWRE) Following Dan Brown Appointment And AI Push Is The Stock Undervalued
Guidewire Software (GWRE) just reshaped its product leadership, appointing Dan Brown as Chief Product Officer with a clear focus on embedding AI across its insurance software platform and cloud applications.
Recent moves around AI and cloud come as Guidewire Software’s share price has climbed 21.1% over the past 90 days, even though the year to date share price return is down 12.2% and the 1 year total shareholder return has declined 30.3%. However, the 3 year total shareholder return of 82.4% points to longer term momentum that has not fully carried through the past year.
Scan how Guidewire Software’s AI push compares with other insurers' tech suppliers by reviewing the hand picked 92 AI infrastructure stocks now shaping core systems and data pipelines across the sector.
For Guidewire Software, this sharp 90 day rebound against a weaker 1 year track record raises a simple tension: Is price catching up to the business, or is sentiment running ahead of fundamentals before valuation work begins?
Most Popular Narrative: 22% Undervalued
Guidewire Software’s most followed narrative pegs fair value at $210.86 versus the last close at $164.78. This frames the current AI and cloud story as still leaving meaningful upside according to those model assumptions.
The industry's transition to cloud-based systems, particularly in the property and casualty insurance sector, is steadily accelerating, which should facilitate future revenue growth as more customers migrate to the Guidewire Cloud Platform.
The burgeoning cloud ecosystem, with over 26,000 Guidewire-focused practitioners and more than 500 applications in the Guidewire Marketplace, supports broader platform adoption and could bolster ARR and service revenue.
See why 11 investors see Guidewire Software as 22% undervalued.
Result: Fair Value of $210.86 (UNDERVALUED)
Still, if large cloud deals slip between quarters or foreign exchange swings reduce reported ARR, the Guidewire Software story could look less secure very quickly.
Find out about the key risks to this Guidewire Software narrative.
Another Way To Look At Guidewire Software’s Valuation
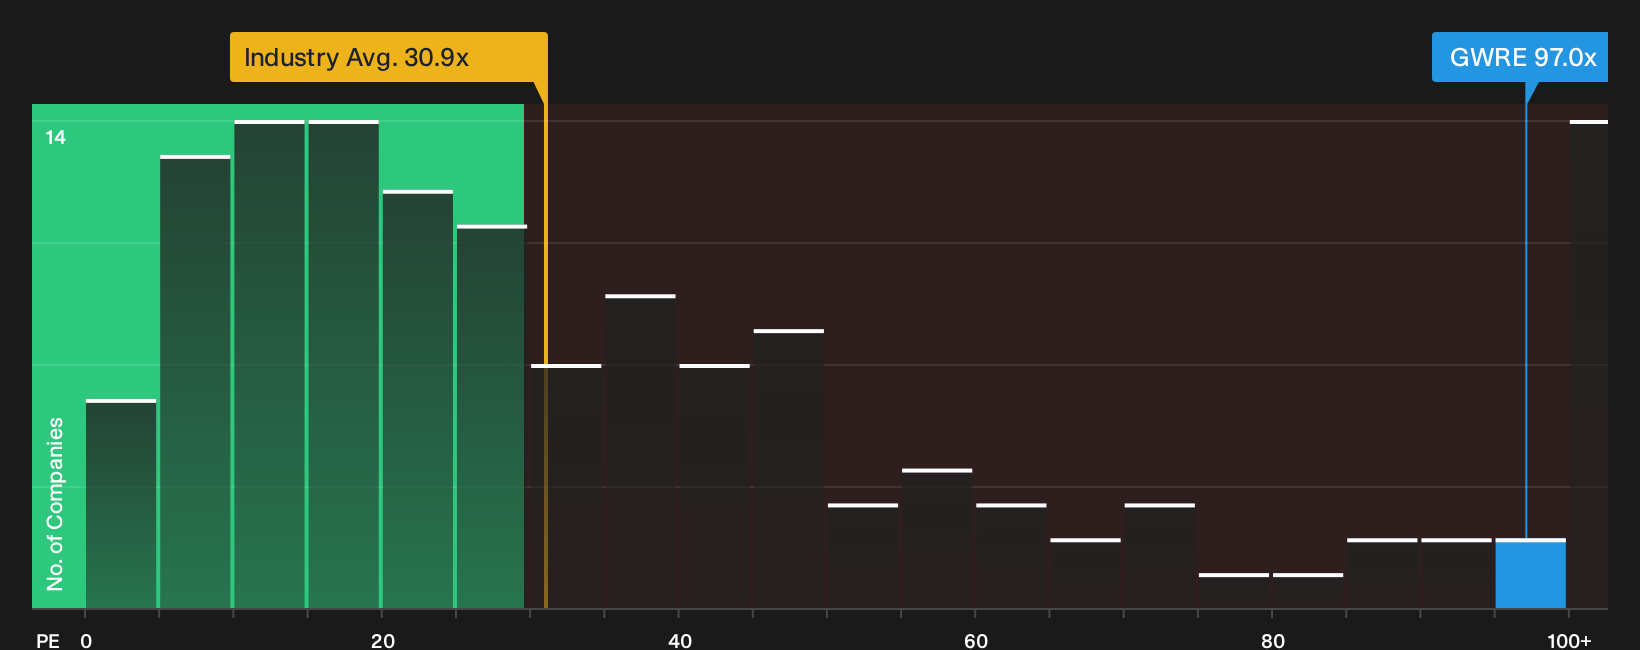
The story around Guidewire Software’s fair value changes once earnings multiples are brought into the picture. The stock trades on a P/E of 97x, compared with 44.9x for peers and 30.4x for the wider US Software group, while the fair ratio sits at 38.9x. That gap suggests valuation risk if expectations cool.
To see how those earnings-based signals stack up against the rest of the sector, and where the market could shift if sentiment changes, take a closer look at our valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the Guidewire Software story so far seems to balance both promise and risk, consider acting promptly and evaluating the trade off for yourself using 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Guidewire Software?
Guidewire Software may be on your radar now, but the next opportunity could be sitting in a completely different corner of the market.
- Target steadier compounding by scanning 31 resilient stocks with low risk scores that aim to keep portfolio swings in check while still leaving room for upside.
- Spot potential mispricings early by reviewing the 20 high quality undiscovered gems that combine solid fundamentals with less crowd attention.
- Strengthen your downside protection by focusing on the list of solid balance sheet and fundamentals (25 results) so weaker financial foundations do not quietly drag on your returns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com