
Why Salzgitter Rose Even Though Sales Fell
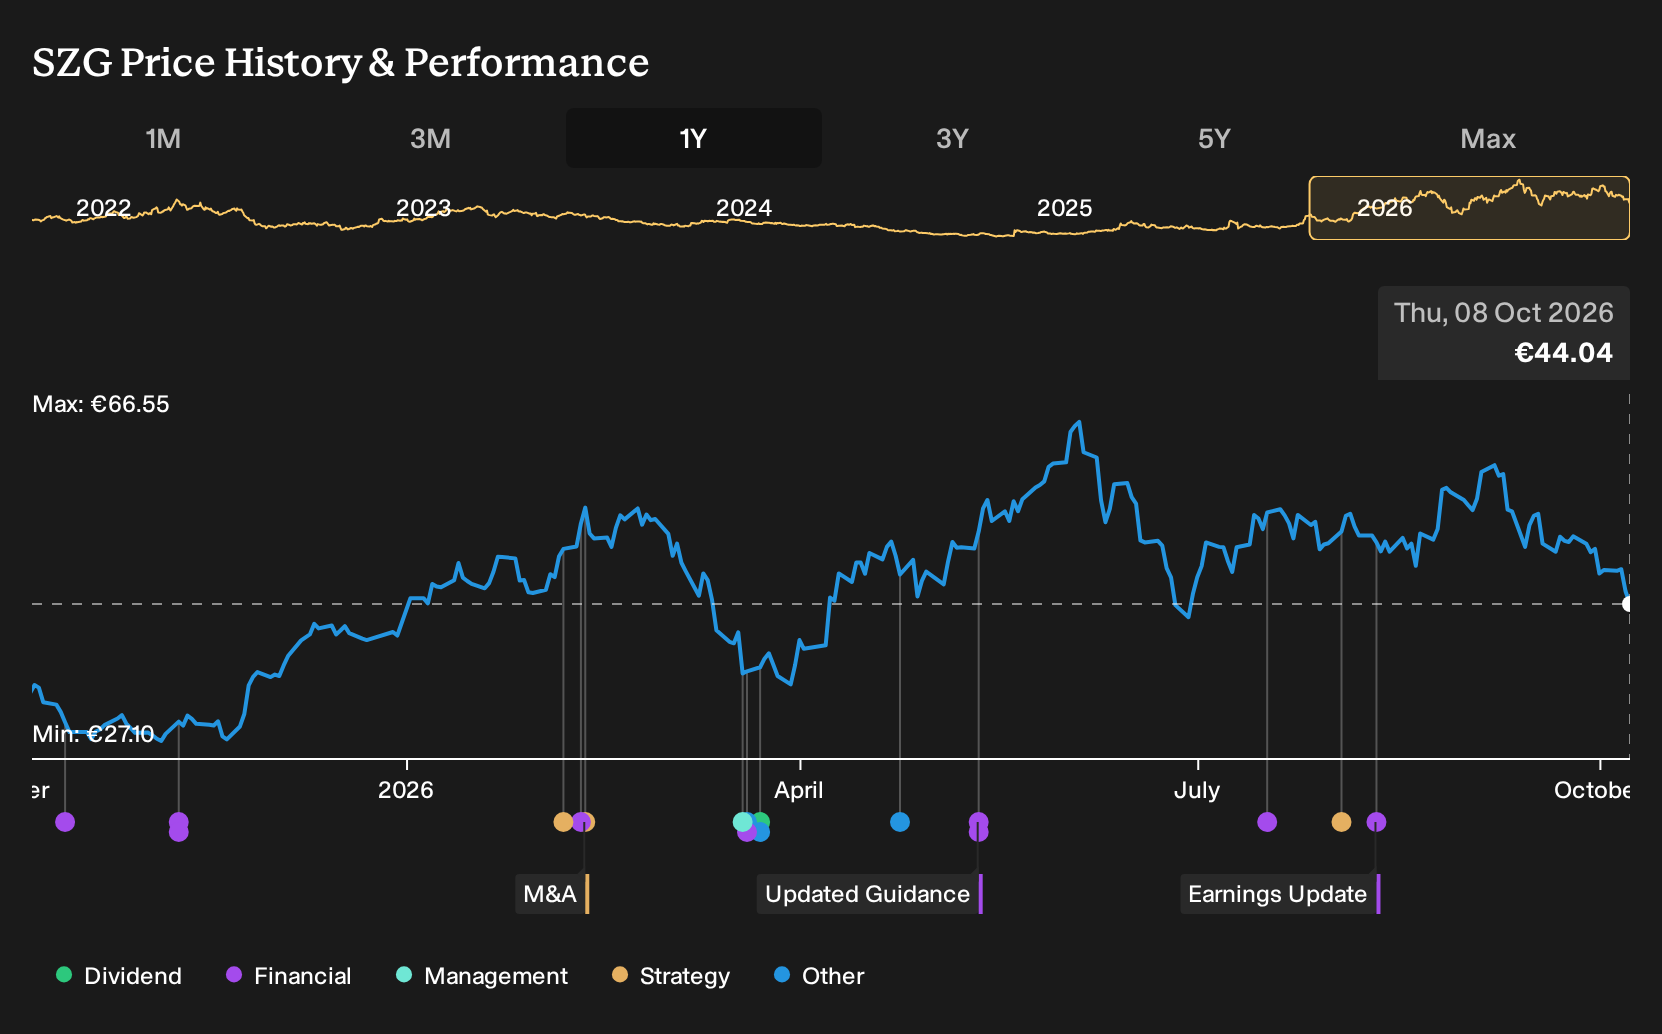
Salzgitter’s latest contract to source green hydrogen from EWE turned a long‑planned decarbonization vision into a specific fuel supply commitment for its mills. For Salzgitter shareholders, the return over the past year was 31.1%, including dividends. If you were weighing a buy on 8 October 2025, you had to decide whether green steel partnerships, EU measures and mixed earnings justified that risk. Which parts of that story really needed to be true for this outcome to make sense?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Salzgitter has already moved. Pinpoint other ways to investigate the theme among 16 top copper producer stocks.
The Argument Salzgitter Investors Were Really Having
The shares cost €34.02 at the start of the period, so anyone looking at Salzgitter had to choose which future felt more believable.
The bullish Narrative put Fair Value at €40.03. It leaned on green steel demand, EU trade measures and the idea that revenue could grow 3.5% a year, with profit margins rising from a loss to 4.6%, supported by a future P/E assumption of 5.2x.
The more cautious Narrative saw Fair Value at €23.24. It accepted EU carbon rules and infrastructure spending as supports, yet focused on risks from record steel imports and cost volatility, with earnings only recovering to €218.8 million on a 6.6x P/E assumption.
What The Evidence Did To The Salzgitter Argument
Salzgitter’s contract with EWE for green hydrogen and its hybrid solar plus battery PPA supported the greener, higher margin path in both Narratives. Later Q2 2026 figures showed revenue slipping from €2,335.2m to €2,242.8m while the loss narrowed from €55.1m to €40m and net margin improved from -2.4% to -1.8%. The evidence cut both ways.
The lesson is simple. When a story leans on margin repair, keep checking whether losses shrink and net margin moves toward break-even, even if sales tread water.
What Salzgitter’s 31% Run Still Leaves You Paying For
Salzgitter now trades at €44.04 after a 31.1% gain over the past year, while the selected Narrative’s Fair Value still sits above that level on its own assumptions. The argument leans on tighter EU steel imports, higher pricing power and a shift toward greener and less cyclical activities.
If you buy at today’s price, you are treating a stronger role in EU trade policy, green steel exports and higher margin technology revenue as underappreciated rather than fully reflected.
"Accelerating EU trade measures, defense certifications, and infrastructure partnerships position Salzgitter for outsized growth, higher margins, and structural outperformance against peers. Expanding global demand for green steel and technology transformation diversify revenues, enhance resilience, and support sustainable long-term margin improvement."
One Narrative disagrees with today's price. → See where this Narrative says Salzgitter should trade
Find Your Own Contrarian Opportunity
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 35% below our estimate - shifts contract manufacturing capacity toward cost-efficient animal health formulations and services.
- Company 2 - 25% below our estimate - integrates acquired engineering teams while standardizing bids for energy and infrastructure projects.
- Company 3 - 23% below our estimate - supplies tailored semiconductor and networking components that support demanding, data-heavy digital workloads.
Those are three of them. See all 178 potentially undervalued companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com