
Li Auto (LI), What Is Behind The Fresh Attention?
Li Auto (NasdaqGS:LI) just released its latest delivery update, reporting 31,817 vehicles handed over in September and 1,833,651 units year to date, giving investors fresh data on how the business is progressing.
The latest delivery figures come amid a weak price backdrop, with Li Auto’s share price down 12.5% over the past month and 36.8% year to date. This has contributed to a 1-year total shareholder return that has declined 53.8% as sentiment has cooled despite steady operational updates.
Scan how Li Auto’s recent pullback compares with other Car & Truck makers by reviewing the hand picked 27 high quality undervalued stocks that combine solid finances with discounted prices.
Bulls see Li Auto’s delivery scale and annual revenue of CN¥104.8b as the anchor, while bears point to the recent share price slump and ongoing losses. Which story does the valuation actually support next?
Most Popular Narrative: 30% Undervalued
Li Auto’s widely followed narrative pegs fair value at about $15.66, compared with the last close of $10.90, so the stock screens as materially discounted on that framework.
The analysts have a consensus price target of $15.66 for Li Auto based on their expectations of its future earnings growth, profit margins and other risk factors. In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be CN¥161.2 billion, earnings will come to CN¥5.9 billion, and it would be trading on a PE ratio of 23.1x, assuming you use a discount rate of 12.0%.
See why 79 investors see Li Auto as 30% undervalued.
Result: Fair Value of $15.66 (UNDERVALUED)
Still, heavy R&D and capital spending, alongside fierce competition in China’s NEV market, could pressure Li Auto’s margins and challenge the bullish recovery story.
Find out about the key risks to this Li Auto narrative.
Another View: What Li Auto’s Sales Multiple Signals
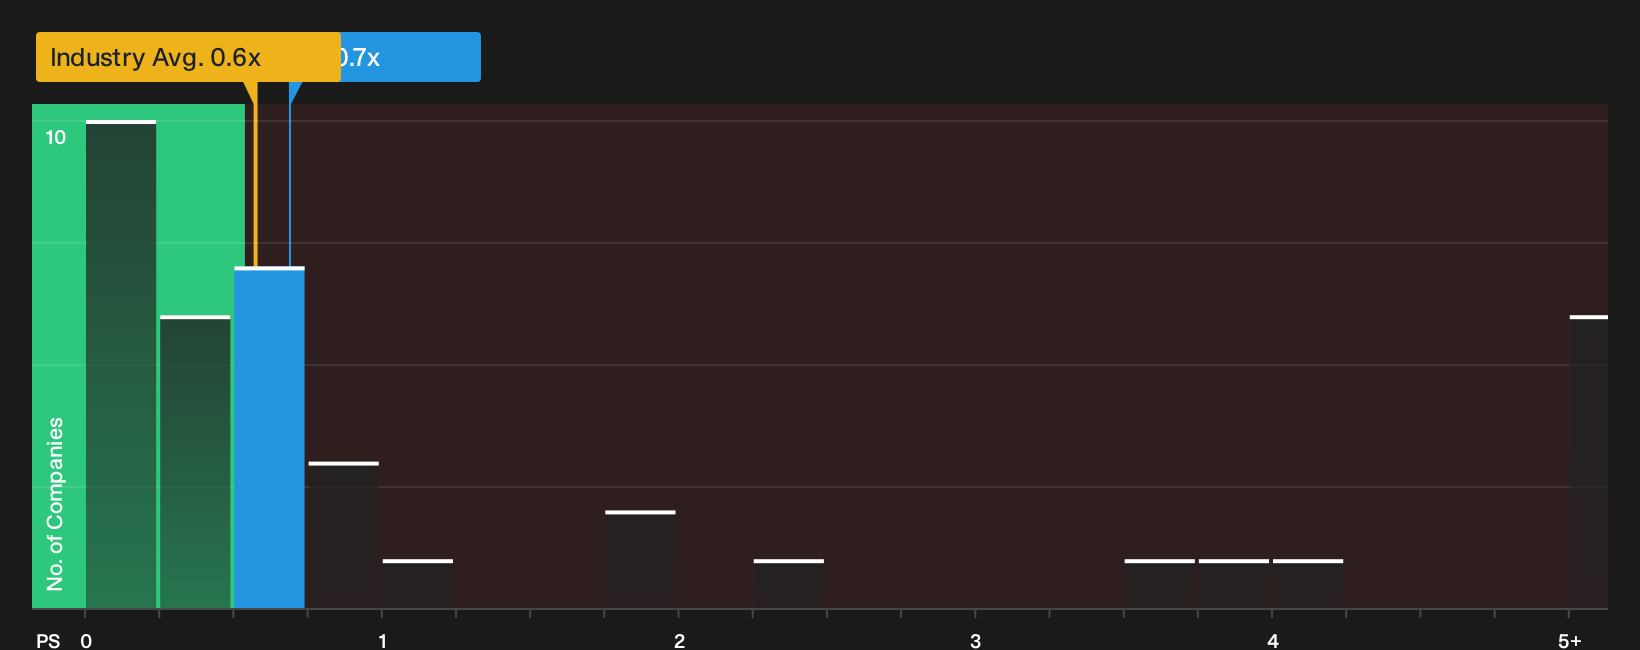
That underpriced story meets a different read once you look at what investors are paying for Li Auto’s revenue today. On a P/S of 0.7x, the stock trades above the US Auto industry average of 0.6x, yet in line with its own 0.7x fair ratio estimate. That mix suggests limited room for error if the growth narrative stumbles, even if peers trade richer.
For anyone weighing these conflicting signals, the key question is whether Li Auto deserves to move closer to peer levels or drift back toward the fair ratio if expectations cool.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Li Auto is clearly split, so this is the point where you pressure test the numbers yourself and decide if the caution is justified. To see which potential upsides analysts are highlighting, review the 2 key rewards.
Looking for more investment ideas beyond Li Auto?
If Li Auto has sharpened your focus on pricing power and risk, do not stop here. Broaden your watchlist with a few targeted stock ideas.
- Go hunting for potential mispricings across the market by scanning the 27 high quality undervalued stocks that pair solid fundamentals with discounted share prices.
- Prioritise resilience and capital protection by reviewing the 31 resilient stocks with low risk scores that score well on business stability and financial strength.
- Spot earlier stage opportunities with robust balance sheets by combing through the 20 high quality undiscovered gems that remain off most investors’ radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com