
Did Earnings Beat Just Shift Bancorp's (TBBK) Investment Narrative?
- The Bancorp, Inc. recently reported Q2 FY26 earnings per share of 1.45 with a 67.05% profit margin and introduced its Finetics embedded finance platform for nonbank partners.
- The combination of a high reported margin and a new embedded finance offering suggests that Bancorp may be emphasizing fee-based fintech partnerships rather than relying solely on traditional spread income.
- Next, attention will likely turn to how Bancorp's reported profitability and the Finetics launch might shape the existing investment narrative.
Bancorp Investment Narrative Recap
To own Bancorp, you need to be comfortable with a bank that leans heavily on fintech partners and fee income while managing traditional banking pressures like a weaker net interest margin. Recent Q2 FY26 EPS of 1.45 and a 67.05% reported profit margin keep the short term focus on whether that fee heavy model can stay resilient while revenue expectations point to declines.
The biggest near term swing factor remains execution in fintech programs versus any strain in REBL and other lending portfolios. Key risks cluster around partner concentration, a lower allowance for bad loans, and margin pressure. The latest quarter does not remove those issues, but it also does not fundamentally change them.
The launch of Finetics appears closely connected to the existing fintech catalyst that analysts already focus on: higher fee income from ACH, card, and payment processing plus credit sponsorship. This platform formalizes that push by giving nonbank partners a clearer way to plug into Bancorp’s banking as a service infrastructure for services such as instant payouts, prepaid cards, and digital wallets.
For you as an investor, the practical question is whether Finetics can deepen or diversify those partnerships fast enough to offset pressure from a declining net interest margin and expected revenue contraction. Execution risk rises as dependency on a concentrated fintech base increases, especially with regulatory or partner credit events still on the risk list.
Bancorp Earnings And Revenue Setup Into 2028
Bancorp's analyst narrative ties the Finetics launch into a fairly specific earnings roadmap. Forecasts point to revenues of $497.5 million and earnings of $337.0 million by 2028, off a base of $217.5 million in earnings today. That profile assumes revenue will decline 0.1% per year while profit margins climb, which implies an earnings increase of about $119.5 million from current levels.
Uncover how Bancorp's fair value indicates a 55% potential upside to its current price before a perceived discount in Bancorp closes.
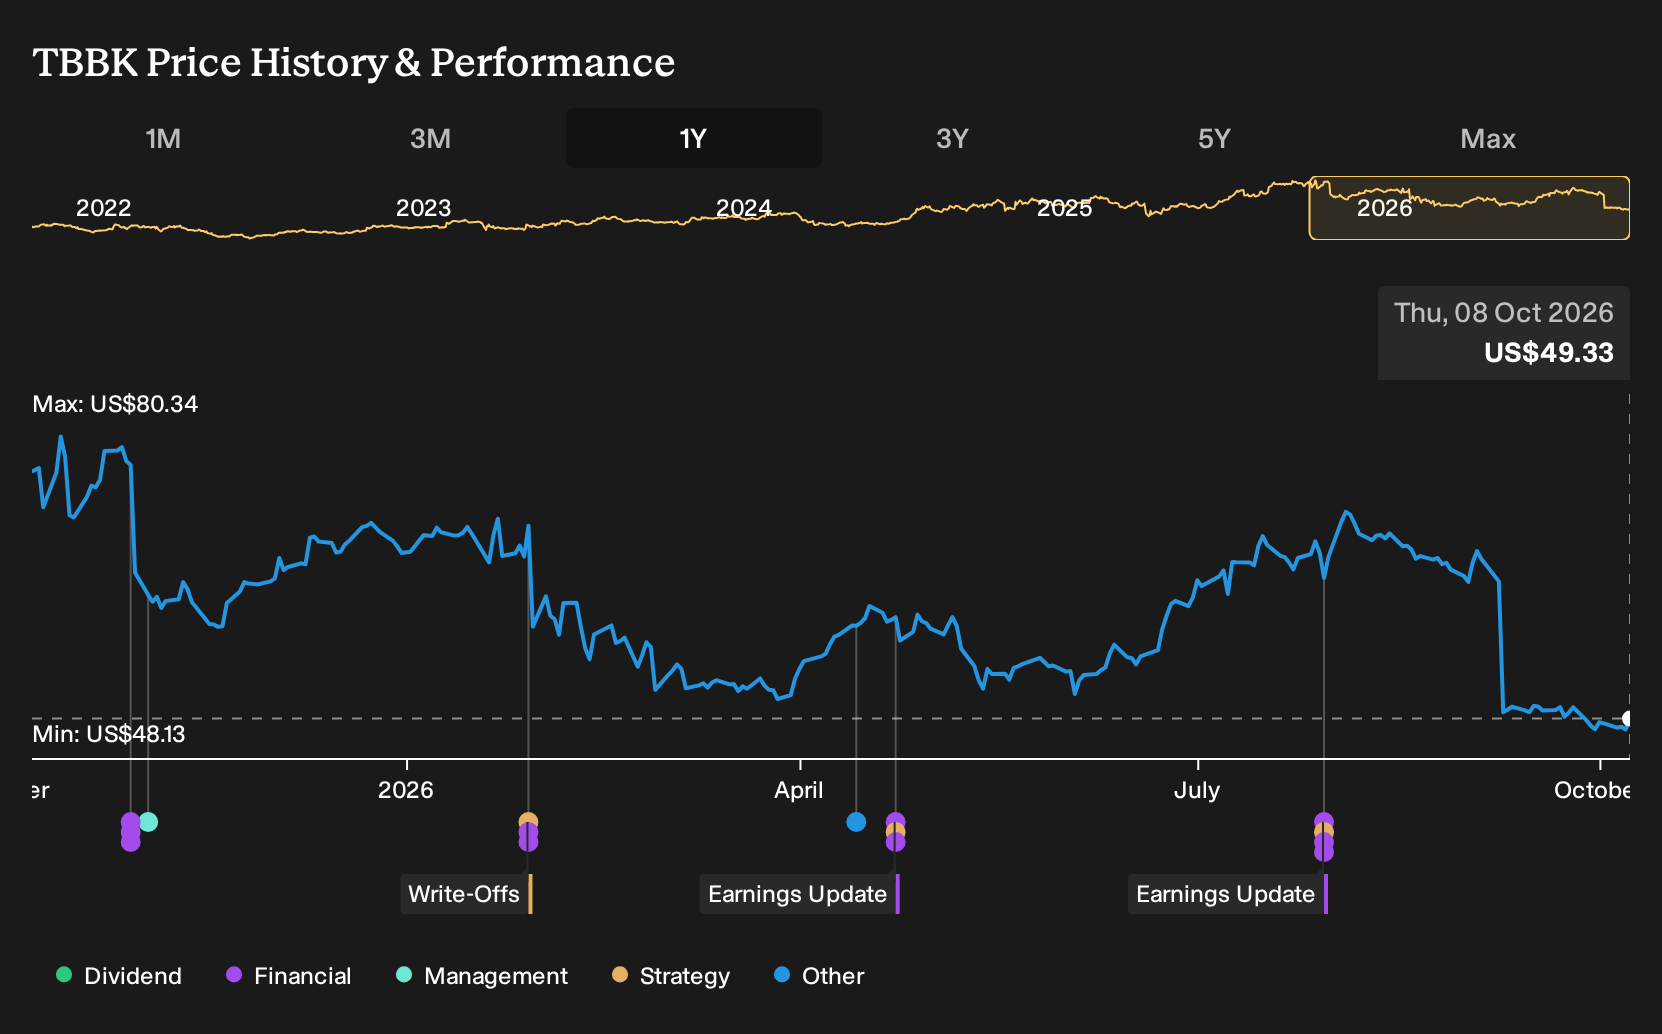
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$75.88 to about US$136.78, so private investors are split on where Bancorp should trade. Set that against fintech fee growth hopes and margin pressure risks, and opinions clearly diverge. Take time to compare several viewpoints before deciding where you sit.
Explore 2 other Bancorp fair value estimates, including one that suggests it could be worth just $75.88!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Bancorp research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bancorp's overall financial health at a glance.
Looking for more ideas beyond Bancorp?
Once you have a view on Bancorp, it can help to compare it with other opportunities that share similar quality traits or risk profiles. Use the Simply Wall St Screener to spot stocks that fit your own return goals and risk limits rather than just following the latest headline.
- If you want businesses that aim to combine quality with attractive entry points, scan a curated set of 27 high quality undervalued stocks that may align with a disciplined price conscious approach.
- If balance sheet strength matters most to you, filter for companies on a list of solid balance sheet and fundamentals (25 results) that can help you focus on resilience and financial flexibility.
- If you like the idea of backing underfollowed opportunities, search across a 20 high quality undiscovered gems and see which quieter stories match your criteria.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com