
argenx (ENXTBR:ARGX) Dropped, So What Is Behind The Latest Attention?
argenx (ENXTBR:ARGX) moved into focus after it halted the Phase 3 UNITY trial of subcutaneous efgartigimod in Sjögren's disease, while on the same day it reported positive Phase 2 data for FB102 in celiac disease.
argenx’s news hit a stock that was already under pressure, with the share price falling about 16% over the past week and roughly 19% over the past month. Over the longer term, total shareholder return over five years is up about 172%, so recent momentum is clearly fading from a strong multi‑year run.
Scan how argenx’s setback and pipeline progress compare with other complex healthcare plays by reviewing our curated list of 124 healthcare AI stocks.
The sharp pullback in argenx after the UNITY setback contrasts with a long stretch of strong shareholder returns and ongoing trial progress. This slide may reflect a change in sentiment ahead of further valuation analysis.
Most Popular Narrative: 2.8% Overvalued
The most followed valuation narrative for argenx, according to kapirey, places fair value at €686.43 compared with the last close of €705.60, which implies a small premium that hinges on how the pipeline and VYVGART story play out from here.
argenx is a commercial-stage biotech in immunology with an active blockbuster (VYVGART) and an advanced pipeline focused on rare autoimmune diseases. The investment thesis is based on:
• Leadership in a new therapeutic class (FcRn inhibitors)
• Very strong commercial growth (revenues doubled in 2 years)
• Pipeline with multiple near-term catalysts (2026–2027)
• Typical biotech risks: dependence on a single asset, pricing pressure, competition
See why 2 investors see argenx as 3% overvalued.
Result: Fair Value of €686.43 (OVERVALUED)
Still, the argenx memo leans heavily on VYVGART momentum and ambitious revenue scenarios, so any pricing squeeze or pipeline disappointment could quickly undermine that 2.8% overvaluation call.
Find out about the key risks to this argenx narrative.
Another View: argenx Through The DCF Lens
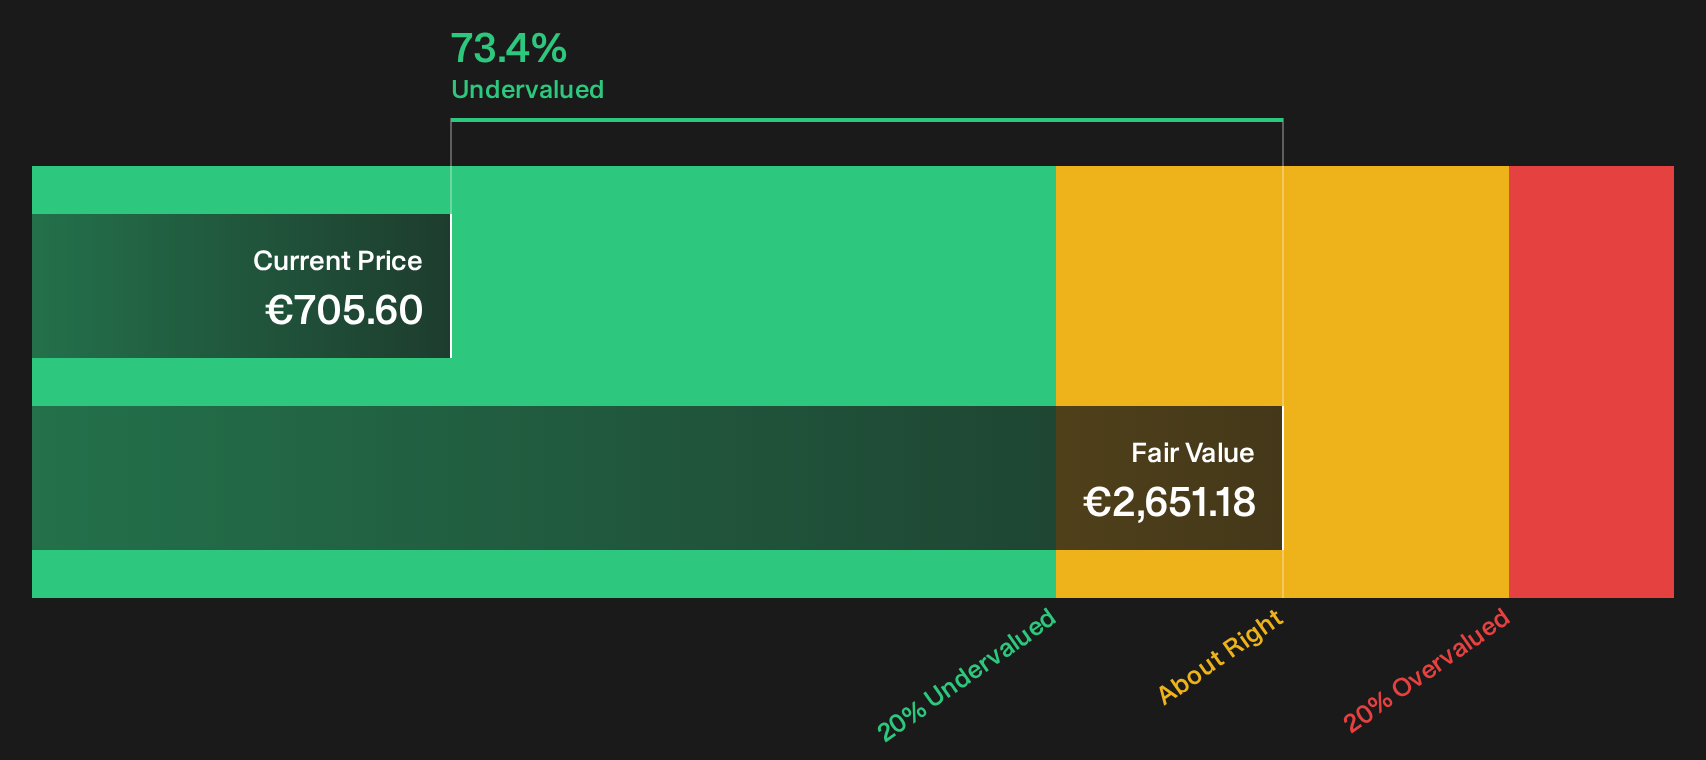
Where the user memo lands on argenx as 2.8% overvalued at €705.60 versus a €686.43 fair value, the SWS DCF model points in the opposite direction. It estimates future cash flow value at €2,651.18, which implies the current quotation trades far below that level.
This gap is substantial in practical terms. A DCF that high indicates the model assumes very strong, long-lasting cash generation, while the narrative memo reflects a much more conservative outcome. The tension between those two views raises a simple question for investors: Which set of assumptions appears more realistic for argenx today?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment in argenx is clearly divided, with recent trial news cutting both ways, so consider acting promptly and weigh the trade off yourself using the 4 key rewards and 2 important warning signs.
Looking for more argenx-like investment ideas?
Do not stop your research with argenx. Broaden your watchlist using the Simply Wall St Screener so you do not miss opportunities hiding in plain sight.
- Target potential mispricings by scanning a curated set of 178 high quality undervalued stocks that pair quality fundamentals with appealing valuations.
- Prioritise resilience first and stress test your portfolio against a 225 resilient stocks with low risk scores that focuses on companies with stronger risk profiles.
- Hunt for future standouts before they hit the spotlight with a 619 high quality undiscovered gems built around solid financial quality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com