
Arteris (AIP) Dropped, So What Is Behind the Latest Attention?
Government backed security program expansion puts Arteris in focus
Arteris (AIP) is back on investor radar after expanding its third party IP security assurance program with BAE Systems and SiFive, backed by an additional US$3.3 million in government funding.
For context, Arteris shares closed at US$22.84, with a 1-day share price return that declined 2.39% and a 7-day return down 4.87%. However, the year-to-date share price return of 46.60% and a 3-year total shareholder return of 273.20% point to strong longer term momentum despite a 34.31% drop over 90 days.
Scan opportunities tied to secure microelectronics by comparing Arteris with a curated 31 resilient stocks with low risk scores that may benefit as government backed security programs gain more attention.
Bulls point to Arteris winning government backed security work, while bears focus on ongoing losses and a sharp 90 day pullback. Which side does the current valuation evidence support as you weigh the stock today?
Most Popular Narrative: 44% Undervalued
Arteris is framed as undervalued in the most widely followed narrative, with a fair value of $41.00 versus the last close at $22.84, and that view leans heavily on how AI and chiplet trends could reshape its revenue mix.
Accelerating adoption of AI and machine learning in enterprise computing and automotive sectors is associated with higher demand for Arteris' advanced NoC IP, as evidenced by recent major wins like AMD and Whalechip. This trend is cited as a key factor that could influence the company’s revenue profile as AI workloads and system complexity expand across industries.
See why 6 investors see Arteris as 44% undervalued.
Result: Fair Value of $41.00 (UNDERVALUED)
Still, Arteris faces two clear pressure points: ongoing losses with projected non GAAP operating deficits into 2025, and heavy reliance on a few large AI and data center customers.
Find out about the key risks to this Arteris narrative.
Another View: Arteris looks expensive on sales multiples
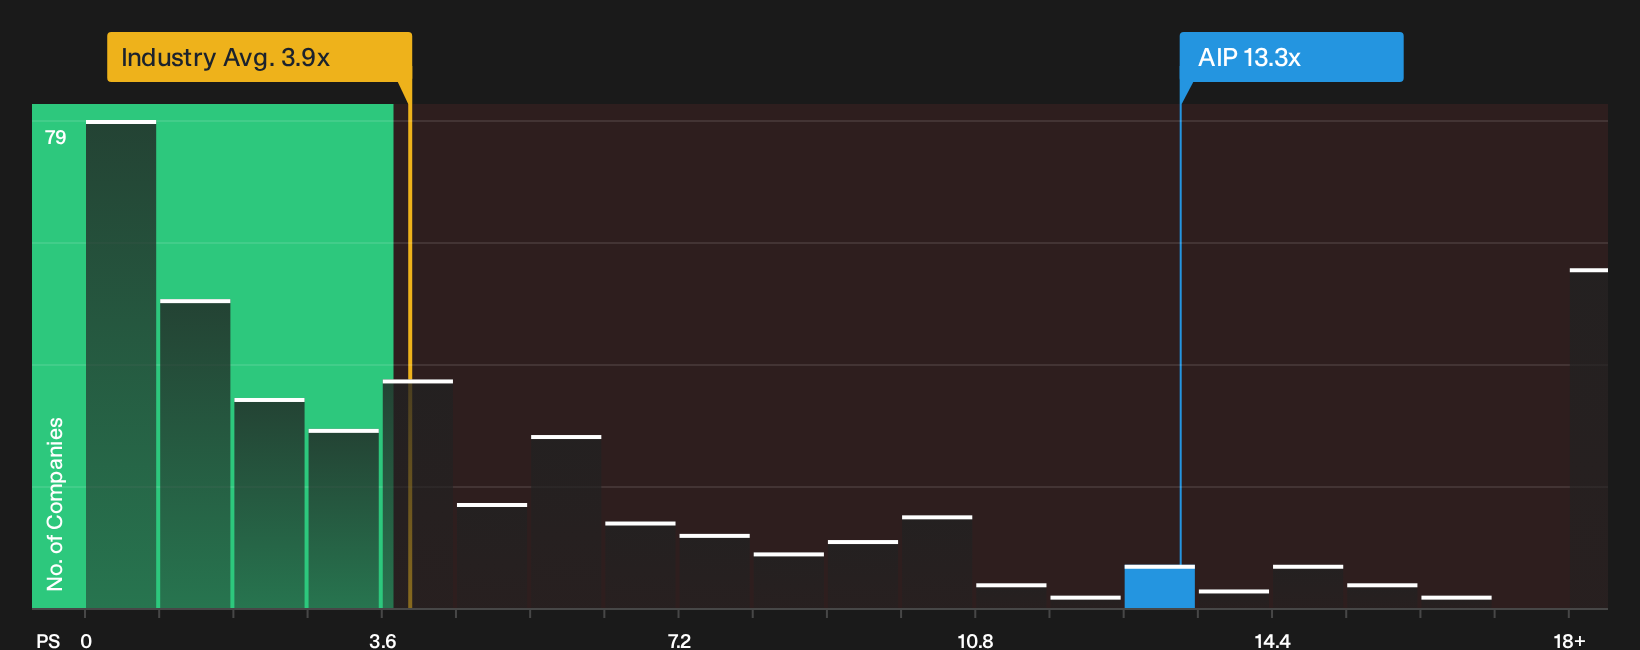
There is a very different picture once you move away from fair value models and look at what Arteris costs on sales. The P/S ratio of 13.3x sits far above the US Software average of 3.9x, a peer average of 2x, and the 5.8x fair ratio that the market could gravitate toward.
If sentiment cools and the share price drifts closer to that fair ratio, the gap between story and sticker price could matter more than any DCF line item for investors deciding when to act. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Arteris can make the story feel blurry, so move fast, stress test the numbers yourself, and weigh both the upside and the red flags with 3 key rewards and 3 important warning signs.
Ready for more ideas beyond Arteris?
If Arteris has your attention, do not stop at one ticker. Use the same energy to scan fresh ideas that fit your risk and return goals.
- Target quality at a discount by lining up companies that pass strict value filters with the 27 high quality undervalued stocks.
- Strengthen your downside protection by focusing on balance sheets that look resilient using the list of solid balance sheet and fundamentals (25 results).
- Spot potential early movers by scanning a 10 elite penny stocks with strong financials before the crowd catches on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com