
3 US Capex And R D Stocks Built For Higher Rates
Rising US deficits, swelling interest costs and fresh tax breaks for capex and R&D are quietly rewiring where capital flows in the market. While higher required returns can pressure valuations, they also reward companies that invest heavily and still keep balance sheets in check. This article walks through three such stocks from a capex and R&D focused screener and explains how the recent fiscal shift could affect each one.
The three stocks below are just a starting sample from this capex and R&D focused idea, and the full screen surfaced 27 more U.S. large caps with similarly detailed stories that are not covered here. To identify and analyze the highest conviction capex and R&D heavy corporates, head straight into the U.S. Capex & R&D-Heavy Corporates screener.
Skyworks Solutions (SWKS)
Skyworks Solutions sits right in the sweet spot of this screener theme, pouring heavy capex and R&D into RF and analog chips that power everything from smartphones to cars. The Qorvo deal could reshape how those investments show up in future earnings power.
Skyworks Solutions develops and manufactures analog and mixed signal chips used in wireless and power applications, with all US$4.0b in revenue coming from proprietary semiconductor products and a US$12.6b market cap anchoring it firmly in the large cap bracket.
"The planned Qorvo merger is framed around creating a combined mobile business of roughly US$5.5b and a non mobile business of about US$2.5b to US$2.6b. This would be together with at least US$500m of cost synergies over 24 to 36 months and a long term model of 50% to 55% gross margin and 30% to 35% operating margin."
What really matters for investors now is how one unresolved pressure around future capital allocation shapes the balance between those margin targets and growth ambitions.
That capital allocation question is exactly what the full narrative for Skyworks Solutions unpacks, highlighting where capex, R&D and the Qorvo merger could be quietly accelerating or masking Skyworks Solutions earnings power.

Ichor Holdings (ICHR)
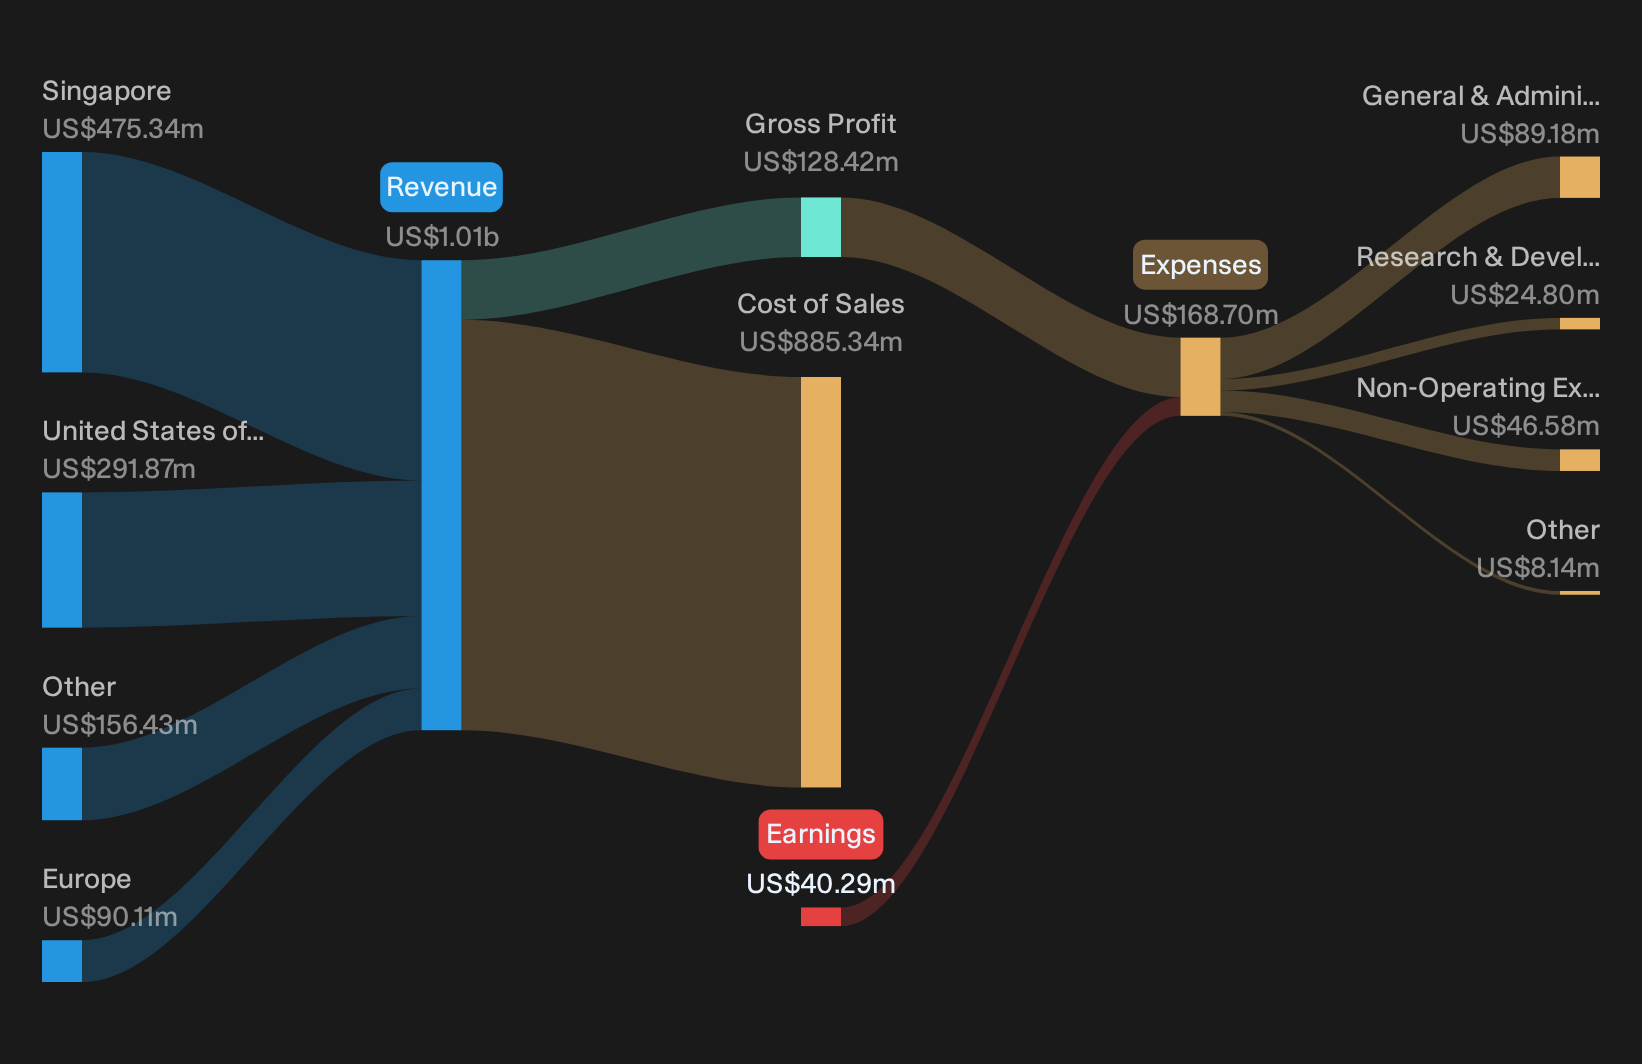
Ichor Holdings plugs neatly into the capex and R&D heavy theme, supplying critical fluid delivery subsystems to semiconductor equipment makers and generating about US$1.0b in revenue from this activity, while its roughly US$2.3b market cap keeps it squarely in large cap territory.
Ichor Holdings gives you exposure to the plumbing behind chip factories, where heavy equipment spending, engineering complexity and tax incentives all intersect and set up the conditions investors care about next.
"Ongoing digital transformation in industries such as automotive, healthcare, and industrial automation is driving secular demand growth for advanced semiconductor manufacturing; this is expected to support sustained long-term order growth for Ichor's fluid delivery subsystems, positioning the company for above-industry revenue growth as these trends accelerate."
What really matters now is how one unresolved pressure inside that upgrade cycle feeds through to the margins investors watch most closely.
To see how that pressure could be accelerating or masking the real upside in Ichor Holdings margins, read the full narrative for Ichor Holdings for the full picture.
SolarEdge Technologies (SEDG)
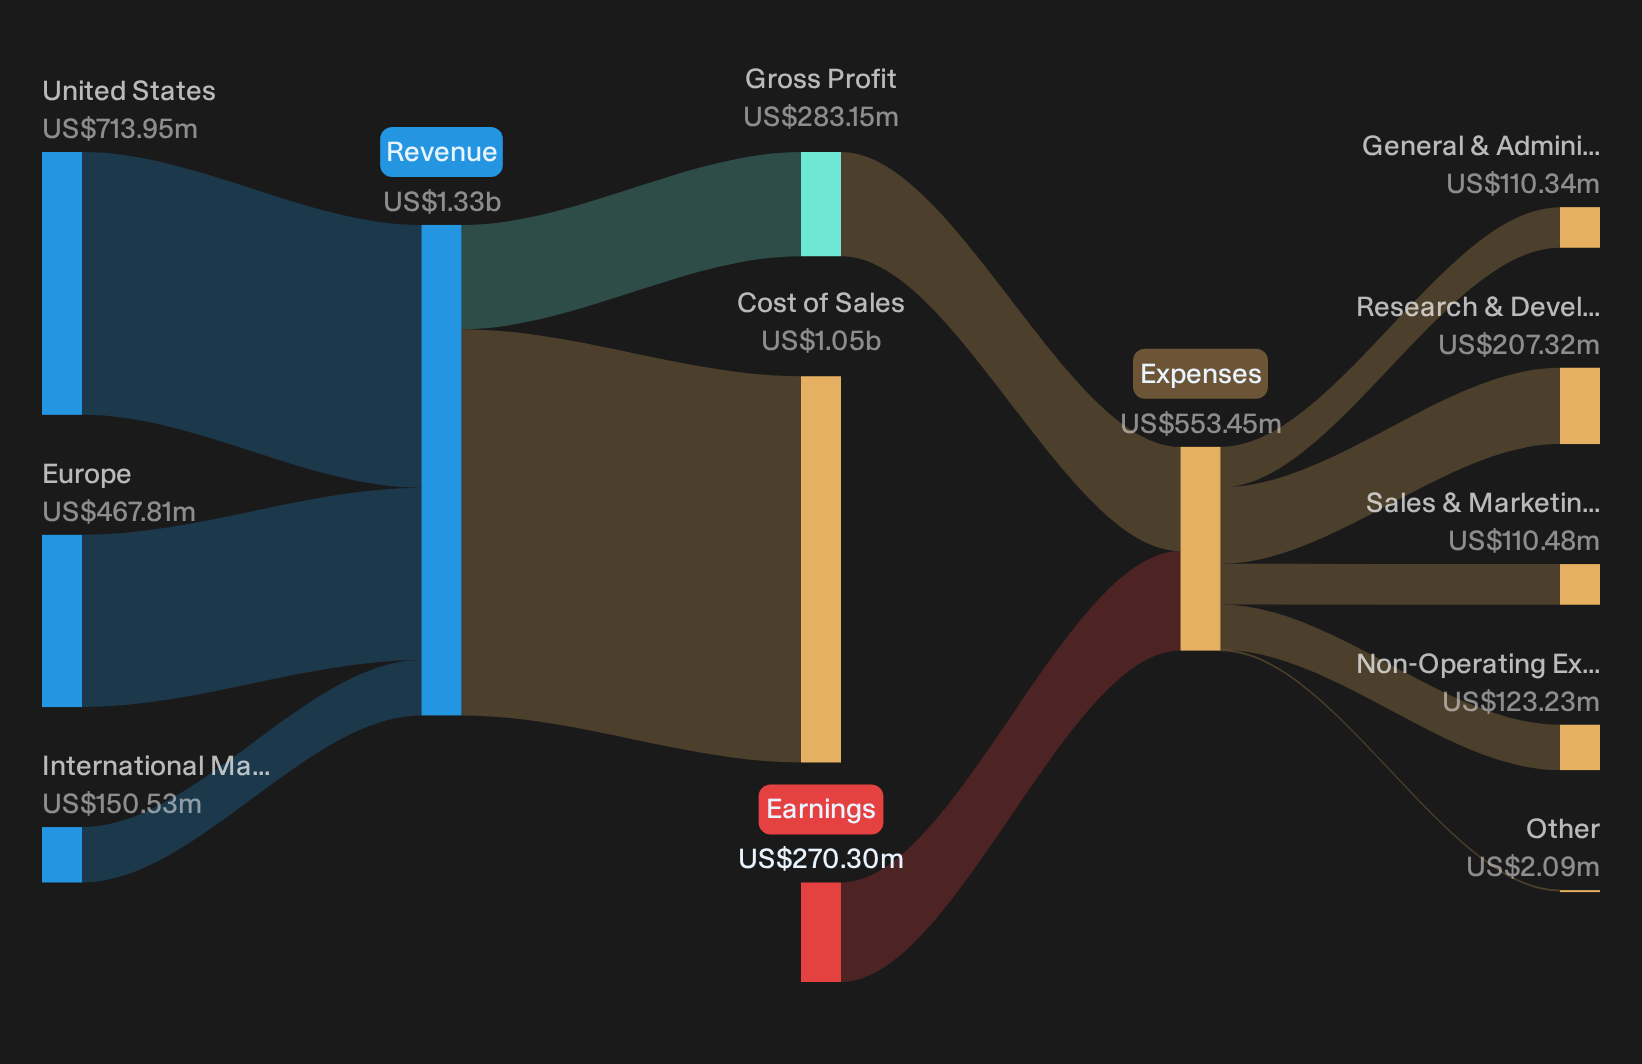
SolarEdge Technologies leans heavily on capex and R&D to build its inverter, storage and EV charging platform, with about US$1.3b in revenue from electric equipment and a roughly US$2.0b market cap anchoring it in this screener’s energy tech manufacturing theme.
SolarEdge Technologies channels that capex and R&D into a full energy stack, from rooftop optimizers to software, which is exactly what this screen is looking for in power electronics and grid-focused manufacturing.
"The combination of global government incentives and rising energy prices will sustain long-term demand for distributed solar and storage, positioning SolarEdge to capitalize as a 'one-stop' solution provider with integrated PV, storage, EV charging, and energy management, leading to durable revenue growth and a richer mix of recurring software and service earnings."
What happens to that upside if one pressure on future margins and cash flow bites harder than current assumptions allow?
If that pressure on margins is what you care about most, read the full narrative for SolarEdge Technologies to see whether SolarEdge Technologies cash flow is quietly accelerating or stalling.
Seeking Alternatives Before The Crowd Moves?
Fresh ideas move first. Once momentum builds and capital starts flying into new themes, early entry points get caught and pricing power drops. Scan these curated picks while it matters and get in early.
- Identify cash-generative leaders before they trend by running the list of solid balance sheet and fundamentals (25 results). This helps you focus research time where the numbers already appear robust.
- Look for opportunities where income and resilience intersect using the 8 dividend fortresses. This can help you concentrate on yield-focused ideas while keeping risk in view.
- Monitor where AI spending is expanding with the 92 AI infrastructure stocks and concentrate on companies that enable this buildout before the theme becomes widely recognized.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com