
MetLife (MET) Shares Climbed, What Is Behind The Latest Attention?
MetLife (MET) has put its dividend policy back in focus after the board declared a fourth-quarter 2026 common stock payout of $0.5925 per share, payable on December 8.
MetLife’s latest dividend decision lands after a strong run in the shares, with the stock at $98.47 and a year to date share price return of 22.6%, while the 1 year total shareholder return of 23.5% and 5 year total shareholder return of 74.7% point to momentum that has been building rather than fading.
Scan how MetLife’s dividend story compares with other income plays by reviewing hand-picked 8 dividend fortresses that combine yield with sturdier balance sheets.
MetLife now pairs a global insurance footprint with a share price near record territory after a strong run. The bigger question is whether that solid franchise is already fully reflected in today’s valuation.
Most Popular Narrative: 8% Undervalued
Against a last close of $98.47, the most followed narrative pegs MetLife’s fair value at about $107 per share, leaving a modest valuation gap that hinges on how effectively the group executes its long term plan.
Continued execution of the New Frontier program, which has already been associated with 10% EPS growth in 2025, a 17% adjusted ROE in the first half of 2026 and direct expense ratios at or better than target, suggests further scope to sustain earnings and free cash flow that underpin MetLife’s current valuation.
See why 29 investors see MetLife as 8% undervalued.
Result: Fair Value of $107.38 (UNDERVALUED)
Still, the MetLife narrative can wobble if fee based earnings at MetLife Investment Management stay under pressure, or if Retirement and Income Solutions spreads remain soft.
Find out about the key risks to this MetLife narrative.
Another View On MetLife’s Valuation
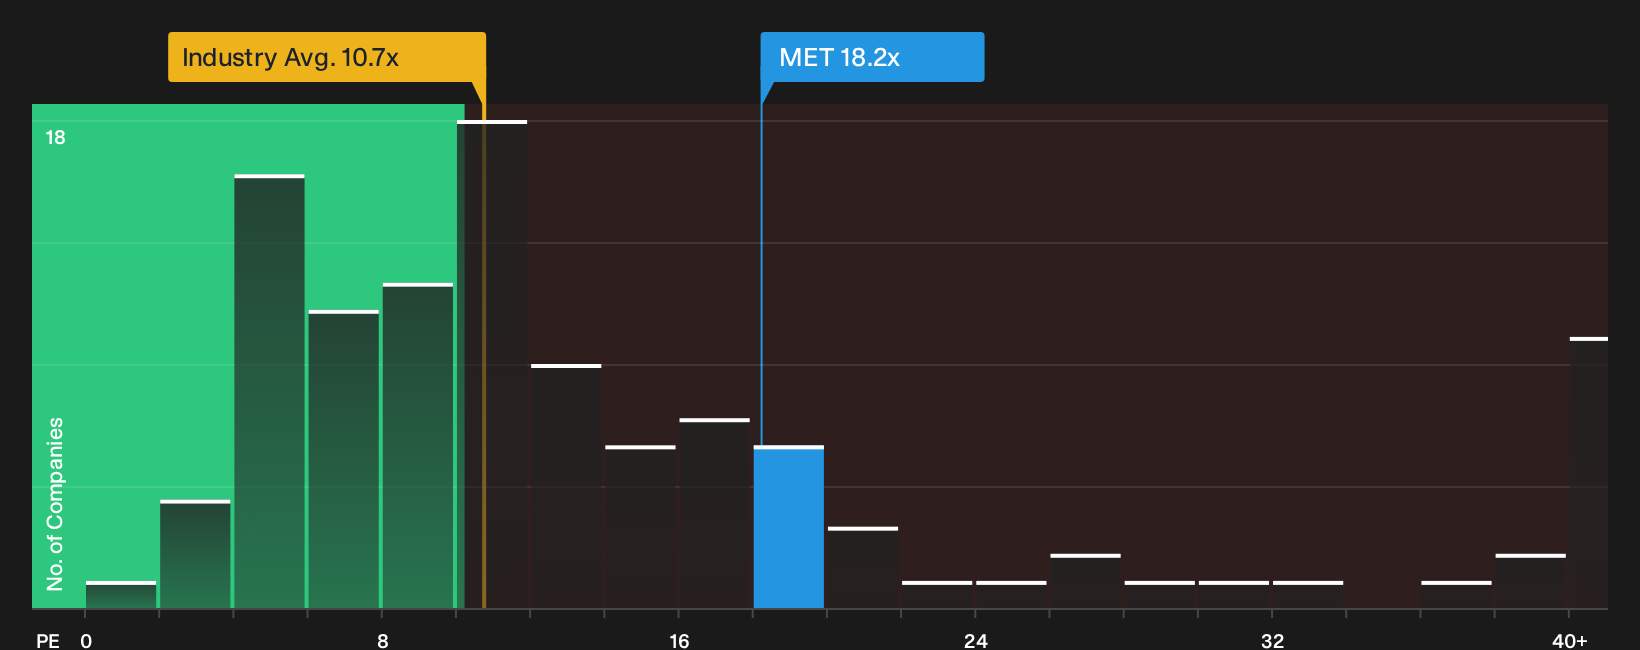
There is a very different read on MetLife when looking at simple earnings multiples. The stock trades on a P/E of 18.2x, while the insurance industry sits near 10.6x and the fair ratio points to 13.6x. That pricing leans richer. Does that signal confidence or leave less room for error?
For a closer look at how this earnings based view lines up against a more detailed cash flow approach, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
To see how MetLife’s current multiple compares visually with peers and the wider sector, review the latest valuation snapshot in
Next Steps
Mixed messages in the MetLife story so far. If you want to move fast and build your own view from the numbers up, start with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond MetLife?
If MetLife caught your eye, do not stop there. Broaden your opportunity set with a few targeted screens that can surface very different types of potential candidates.
- Target resilient payers by scanning a focused group of income stocks built to shoulder higher yields with sturdier balance sheets through the 8 dividend fortresses.
- Hunt for mispriced potential and compare MetLife with a wider pool of quality stocks that may trade below intrinsic value by running the 27 high quality undervalued stocks.
- Prioritise resilience first and sort for companies with robust finances that can better handle shocks by filtering through the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com