
Norwegian Cruise Line Holdings (NCLH) Plans Refinancing, Is The Discount To Fair Value Justified?
Refinancing move puts focus back on Norwegian Cruise Line Holdings stock
Norwegian Cruise Line Holdings (NCLH) has been in focus after outlining a US$750 million refinancing plan aimed at easing its interest costs, even as the stock has declined 32% this year.
The refinancing news lands against a mixed backdrop for Norwegian Cruise Line Holdings, with the share price down 32% year to date but up 5.81% over the past week and recovering 2.92% in the last session. Recent headlines around record booked occupancy, firmer pricing and a heavier debt load have pulled investor focus toward whether recent short term momentum can offset a 1 year total shareholder return that has fallen 33.49% and a 5 year total shareholder return that has declined 41.77%.
Compare Norwegian Cruise Line Holdings with other travel and leisure plays facing similar debt and rate pressures by scanning our hand picked list of solid balance sheet and fundamentals (25 results).
Norwegian Cruise Line Holdings now trades well below the average analyst target and our own fair value range. Is the recent refinancing enough to justify closing that gap, or does the discount still look warranted?
Most Popular Narrative: 23% Undervalued
Against a last close of $15.49, the most followed narrative pegs Norwegian Cruise Line Holdings at a fair value of $20.20, using a 12.54% discount rate and a detailed view on earnings, margins and leverage.
Measured fleet renewal that retires older ships, adds higher earning vessels and moderates capacity growth after 2027 is expected to reduce growth capex by about US$1b annually from 2028. This may free up cash flow that supports deleveraging and, over time, net margin and earnings quality.
See why 53 investors see Norwegian Cruise Line Holdings as 23% undervalued.
Result: Fair Value of $20.20 (UNDERVALUED)
Still, Norwegian Cruise Line Holdings faces two key pressure points: heavy leverage that keeps interest costs high, and ongoing net yield weakness at its core brand.
Find out about the key risks to this Norwegian Cruise Line Holdings narrative.
Another View on Norwegian Cruise Line Holdings Valuation
The first narrative leans on earnings forecasts and a fair value of $20.20. A different lens comes from our cash flow work. The SWS DCF model points to a future cash flow value of $3.97 per share, which makes the current $15.49 price look expensive rather than cheap. Which story you lean toward depends on how much weight you give to long term cash generation versus near term earnings multiples.
For readers who want to see how the cash flow math is built up line by line, Look into how the SWS DCF model arrives at its fair value..
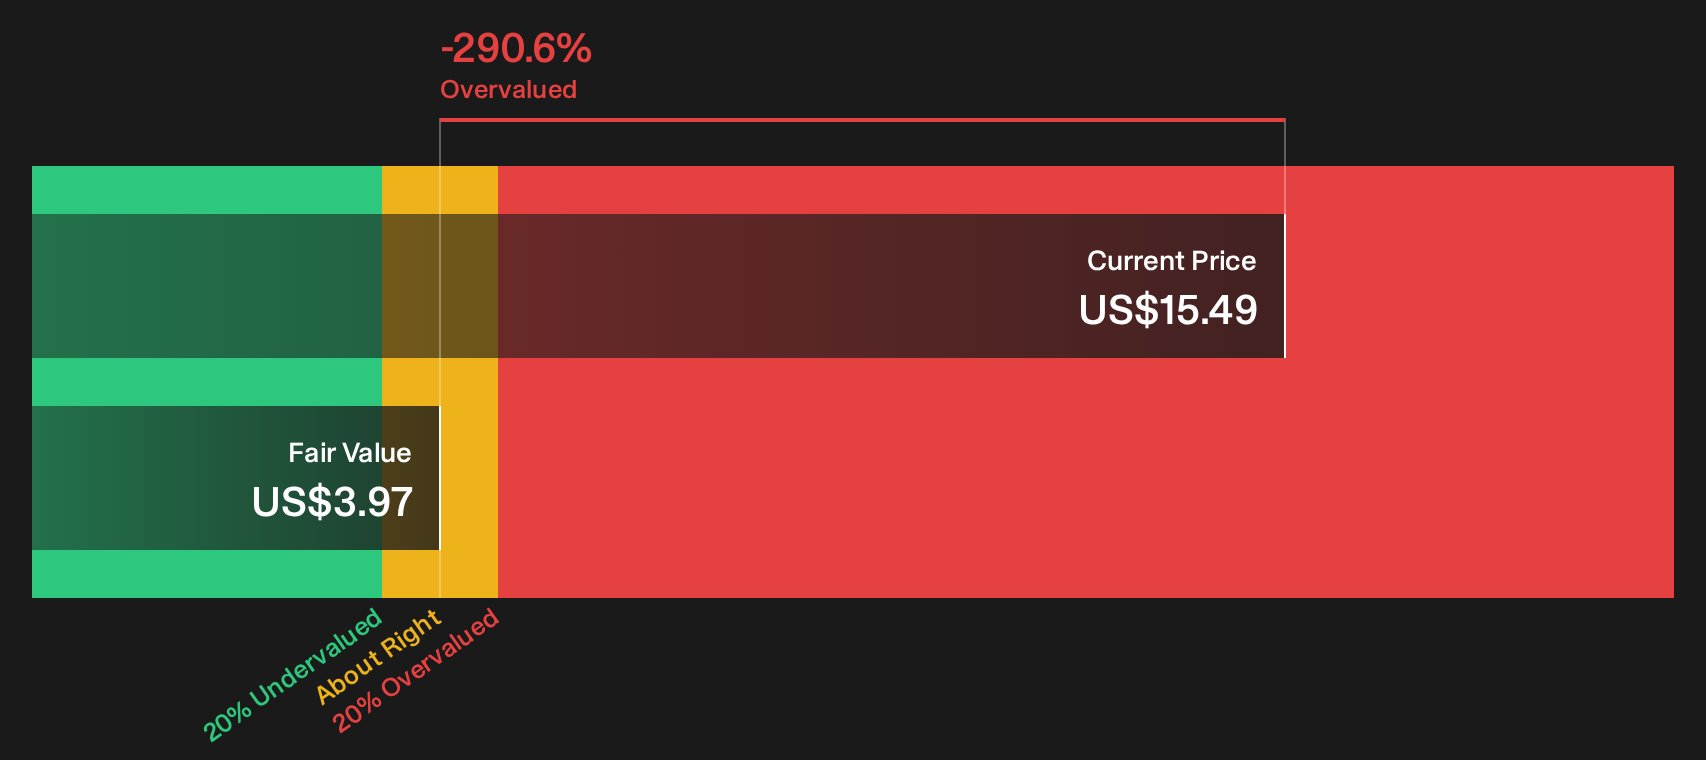
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Norwegian Cruise Line Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals around Norwegian Cruise Line Holdings leave you uncertain, consider taking a closer look yourself and rigorously examining both sides of the argument using the full breakdown of 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Norwegian Cruise Line Holdings?
You have seen how much story sits behind a single ticker. Do not stop here; broaden your watchlist now with fresh, differentiated ideas.
- Target potential upside in quality businesses trading at a discount by running the 27 high quality undervalued stocks before the crowd catches on.
- Strengthen your income stream by focusing on companies built to sustain yields with the 8 dividend fortresses.
- Dial down portfolio stress and concentrate on durability using the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com