
How Robotics Expansion At Helmerich And Payne Has Changed Its Investment Story
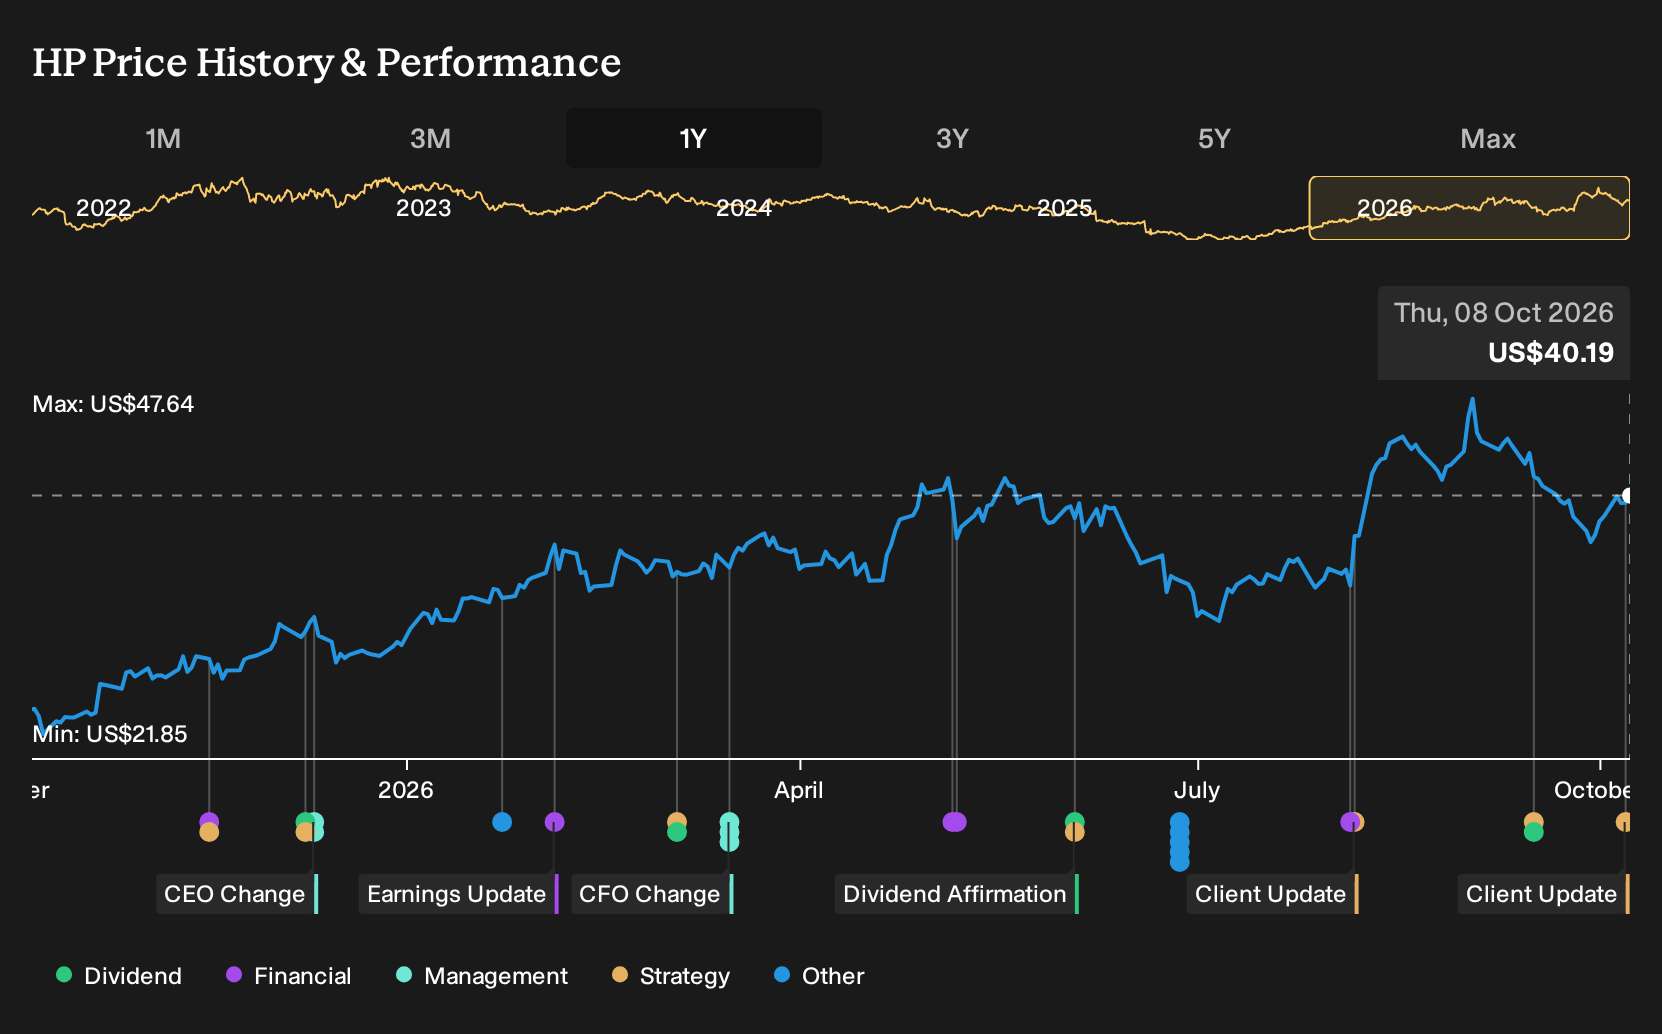
- Helmerich & Payne reported that ExxonMobil is expanding deployment of its FlexRobotics systems to nine rigs over the next 12 months, alongside expectations that fiscal Q4 direct margins across North America, International and Offshore Solutions segments come in at or near the high end of prior guidance.
- The combination of deeper FlexRobotics adoption and management’s focus on stronger direct margins and a 1x net debt to EBITDA target clarifies how execution on technology and balance sheet discipline feeds into Helmerich & Payne’s operating story.
- The investment narrative now needs to reflect how wider FlexRobotics use with ExxonMobil could influence Helmerich & Payne’s margin profile and capital plans.
Helmerich & Payne Investment Narrative Recap
To own Helmerich & Payne, you need to believe its drilling technology and high spec rig fleet can convert into consistently solid direct margins and cash generation, even as global rig activity shifts. The latest update, with fiscal Q4 margins tracking near the high end of guidance, supports that operating story in the near term rather than reshaping it.
The key short term swing factor still sits in dayrates and utilization across North America and key international markets, where overcapacity or customer pullbacks could squeeze profitability. Conflict related issues in places like the Middle East remain an operational risk, and any renewed disruptions there would matter more than this single quarter’s margin outcome.
The most relevant fresh datapoint is management’s outlook that North America, International and Offshore Solutions direct margins for fiscal Q4 should land at or near the top of prior guidance ranges. That ties directly into the FlexRobotics expansion, because higher adoption of automated systems tends to show up in segment economics, not just in press releases.
For you as a shareholder, the read through is simple. Execution on these margin expectations supports Helmerich & Payne’s effort to strengthen its balance sheet, including the push toward roughly 1x net debt to EBITDA by the end of 2027, while ongoing Middle East exposure, dividend coverage and interest service remain important watchpoints if operational conditions soften.
Helmerich & Payne's narrative projects US$4.3b revenue and US$410.2m earnings by 2029. That lines up with analysts using a 2.8% yearly revenue growth rate and implies an earnings swing of about US$548.9m from a current loss of US$138.7m.
Uncover why Helmerich & Payne's fair value indicates an 11% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some bullish analysts frame Helmerich & Payne’s FlexRobotics rollout as a potential earnings catalyst. Before this news, the most optimistic forecasts already pencilled in about US$4.3b of revenue and US$564.6m of earnings by 2029. You can see how those targets, and the more cautious US$352.4m view, might shift as automation adoption accelerates.
Explore 3 other Helmerich & Payne fair value estimates, including one that suggests as much as 108% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Helmerich & Payne research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Helmerich & Payne. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Helmerich & Payne's overall financial health at a glance.
Looking for more Helmerich & Payne sized ideas?
If you want to broaden your watchlist beyond Helmerich & Payne and keep the same level of discipline around balance sheets, cash flow and risk, the Simply Wall St Screener is an efficient way to surface other candidates that fit your style.
- If capital preservation is near the top of your priorities, start with a basket of companies that score well on stability and resilience through the 31 resilient stocks with low risk scores.
- For investors hunting for mispriced opportunities with solid fundamentals, filter for businesses that combine quality metrics with appealing valuations using the 27 high quality undervalued stocks.
- If you like the idea of strong finances acting as a buffer through the cycle, scan for companies with cleaner balance sheets and sturdier fundamentals via the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com