
Why PolyNovo Fell Even As Sales Rose
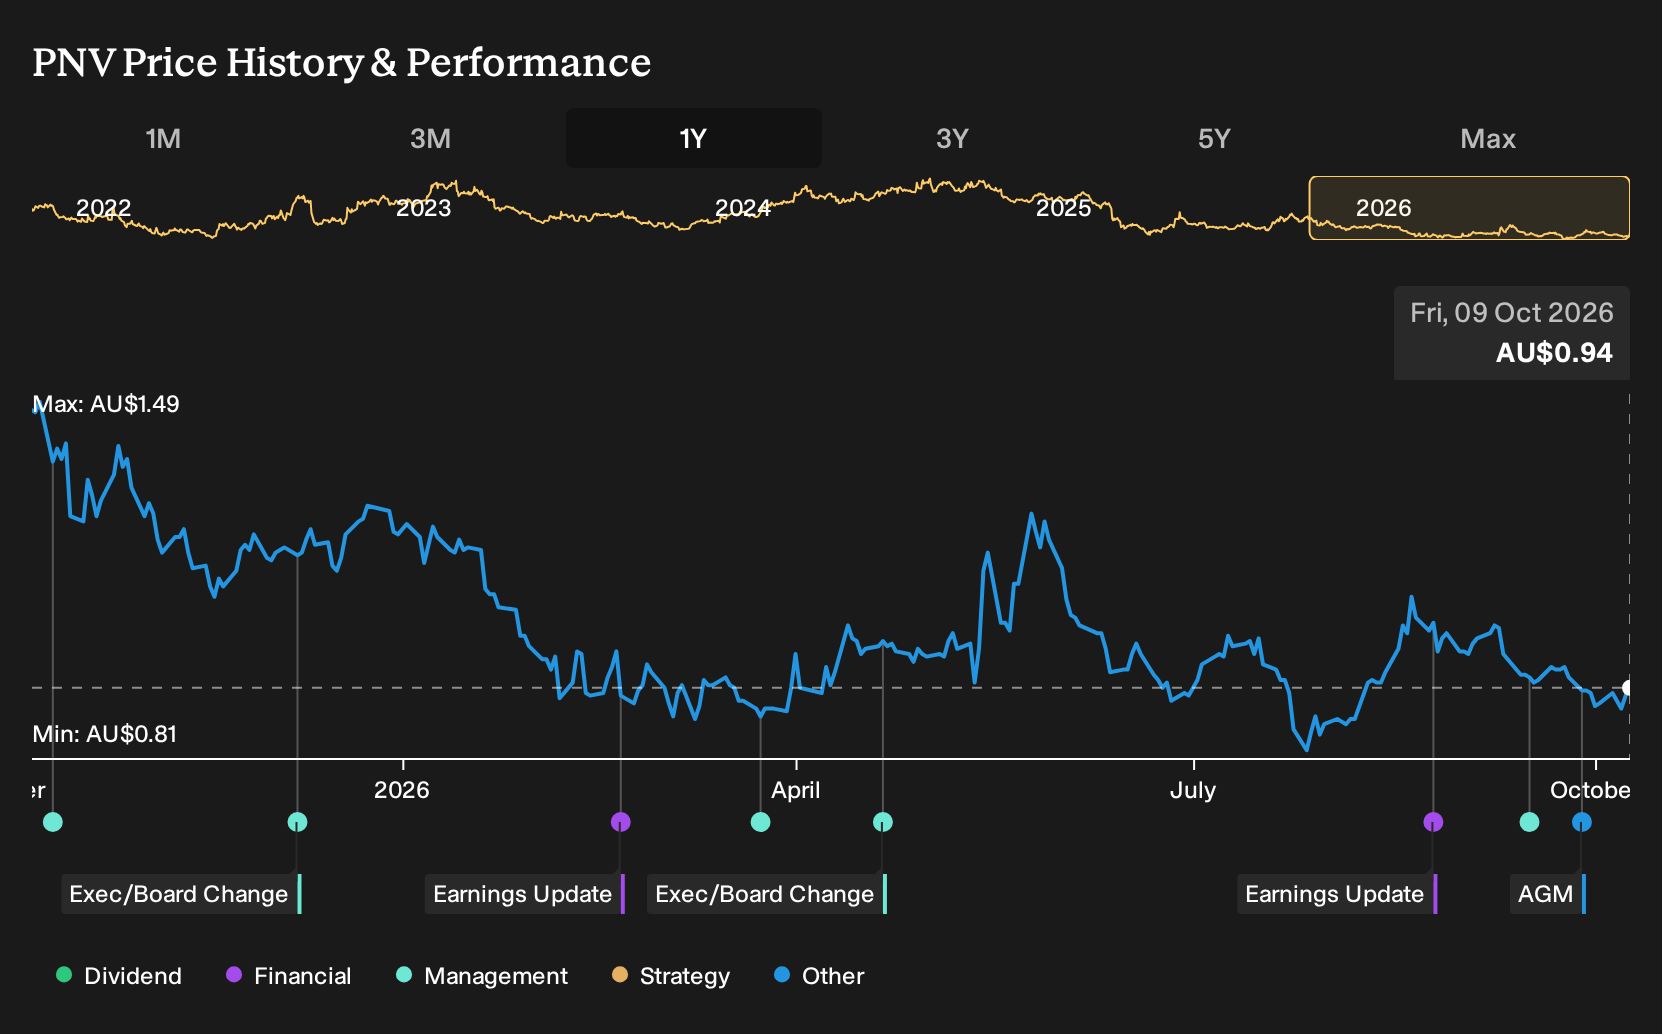
If you had seen the sharp disagreement over PolyNovo in mid 2025 and decided to sit it out, the result might look different today. Holding PolyNovo over the past year would have meant a 37.0% loss, including dividends. Fresh numbers now show higher revenue but a thinner net margin in H2 2026 compared with H2 2025. If you rewind to October 2025, what assumptions on pricing power and costs were already on record that might have signalled this profit squeeze?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The easy part of this move is behind PolyNovo. Zero in on 4 high quality undervalued stocks for companies trading below our estimates.
The Two PolyNovo Stories Investors Had To Weigh
The shares cost A$1.47 at the start of the period, so any view on PolyNovo had to start with whether that price matched the story you believed.
The bullish narrative put fair value at A$2.60 and focused on aging and diabetic populations potentially increasing demand for advanced wound care. NovoSorb products were also expected to support premium pricing and higher net margins.
The bearish view set fair value at A$1.15 and treated global healthcare cost pressure and tighter reimbursement as a potential threat to pricing power and long-term profitability.
What The PolyNovo Results Actually Tested
The clearest new fact for PolyNovo was the split between the top and bottom lines. Total revenue was A$69.164m in H2 2025 and A$79.522m in H2 2026, yet net income moved from A$9.876m to A$7.338m and the net margin shifted from 14.3% to 9.2%. That pattern challenged the optimistic margin story and leaned toward the cautious case on pricing power and costs.
The lesson travels easily. When a bullish pitch leans on operating leverage or premium pricing, treat net margin as the key test. Track whether margin is moving in the same direction as revenue in later reports and compare that trend with the original claim about profitability expansion.
What You Are Paying For In PolyNovo After A 37% Fall
PolyNovo now trades at A$0.94, which is well below the A$1.47 starting point for the one year return discussed earlier. The selected Narrative still sets Fair Value above the current price, based on its own framework rather than any proven fact.
That Narrative leans on international expansion, a broader NovoSorb pipeline and future margin strength, rather than just a lower share price. For the higher Fair Value to be reached, a buyer today would need to assume that global growth in advanced wound care supports sustained, profitable adoption of PolyNovo products across new markets.
"Strong growth prospects in both developed and emerging markets, underpinned by record regulatory approvals, product registrations, and recurring sales in new geographies such as India, Malaysia, and multiple European countries; this ongoing international expansion leverages the increasing global demand for advanced wound care and reconstructive solutions, directly supporting future revenue growth."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Looking Beyond PolyNovo’s Wounds
PolyNovo sits inside a vast healthcare spend, far beyond wound care alone. That budget must stretch further without reducing clinical quality.
You see one answer in firms that run health plans and clinics. Their challenge is simple: medical bills keep climbing.
So they push into value based care, tighter benefit designs and pharmacy programs. They also lean on software, data and AI to trim overhead.
These efforts try to keep cover affordable and earnings steady as care moves outside hospitals. If that pressure builds, the role of these platforms could matter even more.
One Narrative has already put a figure on it. → Uncover the company trading 23% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com