
Moderna Stock Skyrockets on Reports of U.S. Cancer Vaccine Initiative
Moderna (MRNA) shares ripped higher on Friday as reports of a planned U.S. initiative to accelerate cancer vaccine development renewed enthusiasm for its oncology business. According to The New York Times, the proposed public-private partnership would bring together federal researchers, drugmakers, nonprofits and patients, with a launch expected in December.
Moderna stock has been nothing short of a blockbuster investment in 2026, currently trading at about 7x its price at the start of this year.
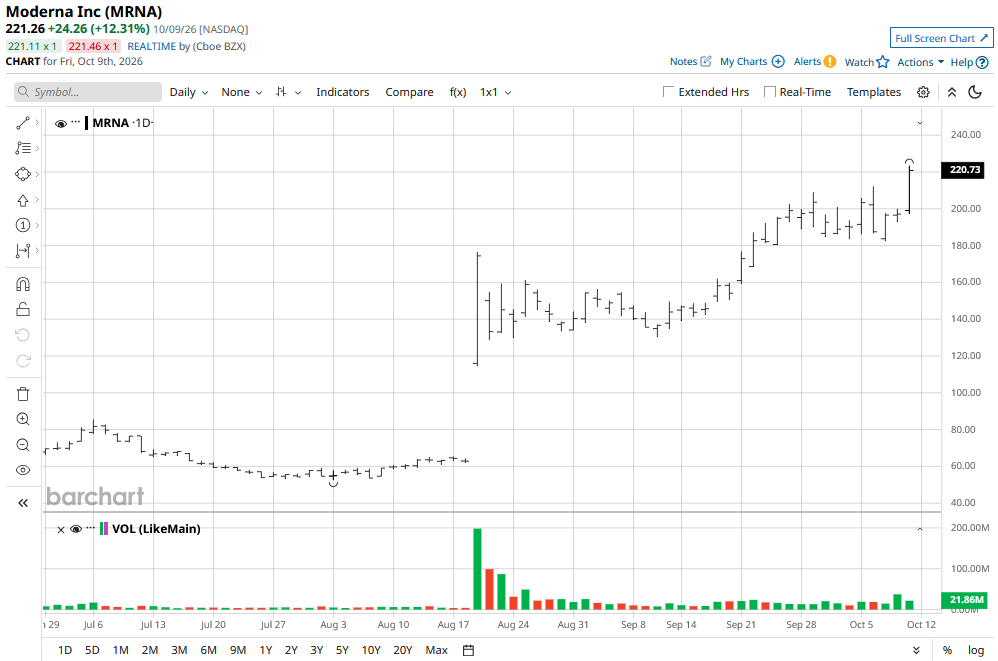
Why Moderna Stock Rallied Today
Moderna’s involvement will reportedly involve the National Institutes of Health and its non-profit foundation, alongside industry and patient groups — an approach similar to the one used to advance Covid-19 vaccines.
For MRNA, the potential upside is stronger coordination across a field where it already has a leading clinical program.
Its experimental intismeran autogene treatment, developed with Merck (MRK), met recurrence-free and distant-metastasis-free survival endpoints in a Phase 3 trial when combined with Keytruda.
The bullish inference is that broader institutional support could help advance development.
Should You Chase the Momentum in MRNA Shares?
The biotech firm’s oncology progress gives investors a concrete reason for optimism, but buying after such a dramatic rally requires confidence that future commercial results can justify the price.
The next major checkpoint is Oct. 24, when Moderna and Merck are scheduled to present detailed Phase 3 melanoma results at the ESMO Congress. Those findings should help investors assess the treatment’s clinical benefit more closely.
Crucially, regulatory approval, manufacturing execution, and commercial uptake remain important hurdles; successful trial results do not guarantee a profitable product.
For investors considering a fresh position, waiting for the detailed data looks more measured than chasing a policy-driven jump today. The opportunity is substantial, but expectations have already risen sharply, with MRNA stock now trading at a rather stretched 40x sales.
Moderna May Be Overvalued at Current Levels
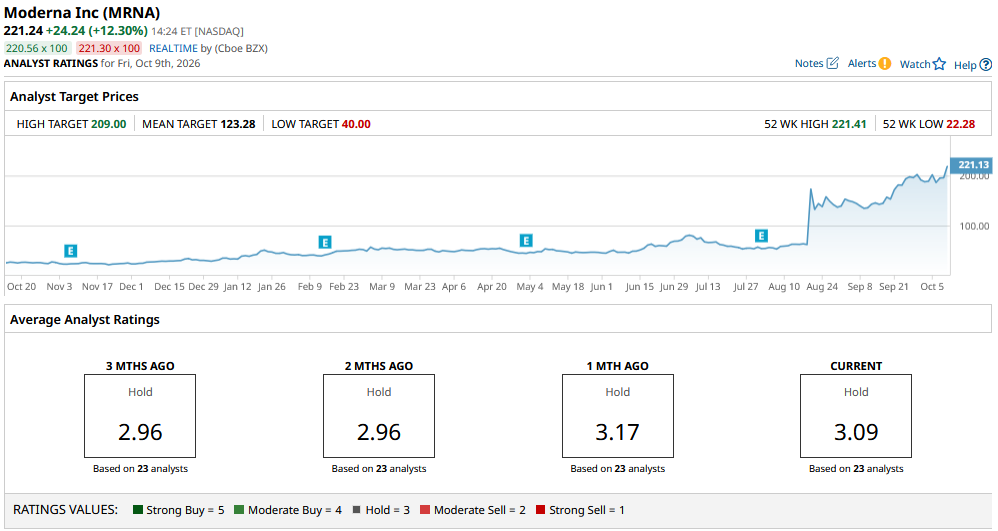
Wall Street analysts currently rate Moderna shares at “Hold.” More importantly, even the highest price target of $209 currently indicates potential downside of nearly 5% from current levels.
On the date of publication, Wajeeh Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.