
Humana (HUM) Rebounds On Star Ratings, Is It Already Fairly Valued?
Humana (HUM) is back in the spotlight after its 2027 Medicare Advantage Star Ratings jumped, with 95% of members in 4 star or higher plans, compared with just 20% for 2026.
That ratings reset has arrived alongside a sharp rerating in the Humana share price. It now trades at US$431.87 after an 11.6% 1 day share price return and a 63.3% year to date share price return. The 1 year total shareholder return of 55.8% contrasts with a 3 year total shareholder return that declined 11.7%, suggesting strong recent momentum following a tougher multi year stretch.
Scan how Humana's Medicare Advantage surge compares with other insurers by reviewing list of solid balance sheet and fundamentals (25 results), which may also be positioned for quality driven momentum.
After a 63.3% year to date surge and a 1 year total return of 55.8%, Humana now poses a simple question for new capital: pay a higher price following the Medicare Advantage reset, or wait for a more forgiving entry point, as detailed in the valuation section next.
Most Popular Narrative: 0% Overvalued
Humana closed at $431.87, almost exactly in line with the most followed fair value estimate of $430.70 that uses a 7.24% discount rate. The key question becomes whether the Medicare Advantage margin plan and Stars traction can keep justifying that level.
The main thing that has to go right is that Humana delivers on its multiyear Medicare Advantage margin and cost-transformation program, including disciplined plan pruning, operating cost ratio reductions, and effective value-based partnerships, while managing regulatory and compliance risks.
The current narrative that Humana is fairly valued and bullish implies the share price already reflects meaningful progress on margin restoration, operating cost efficiencies, and balance sheet optimization with limited room for disappointment if these plans slip.
See why 60 investors see Humana as 0% overvalued.
Result: Fair Value of $430.70 (ABOUT RIGHT)
Still, the Medicare Advantage plan exits affecting about 600,000 members, along with ongoing scrutiny of coding and Star Ratings, could easily unsettle the current Humana narrative.
Find out about the key risks to this Humana narrative.
Another View: What Humana’s P/E Is Signaling
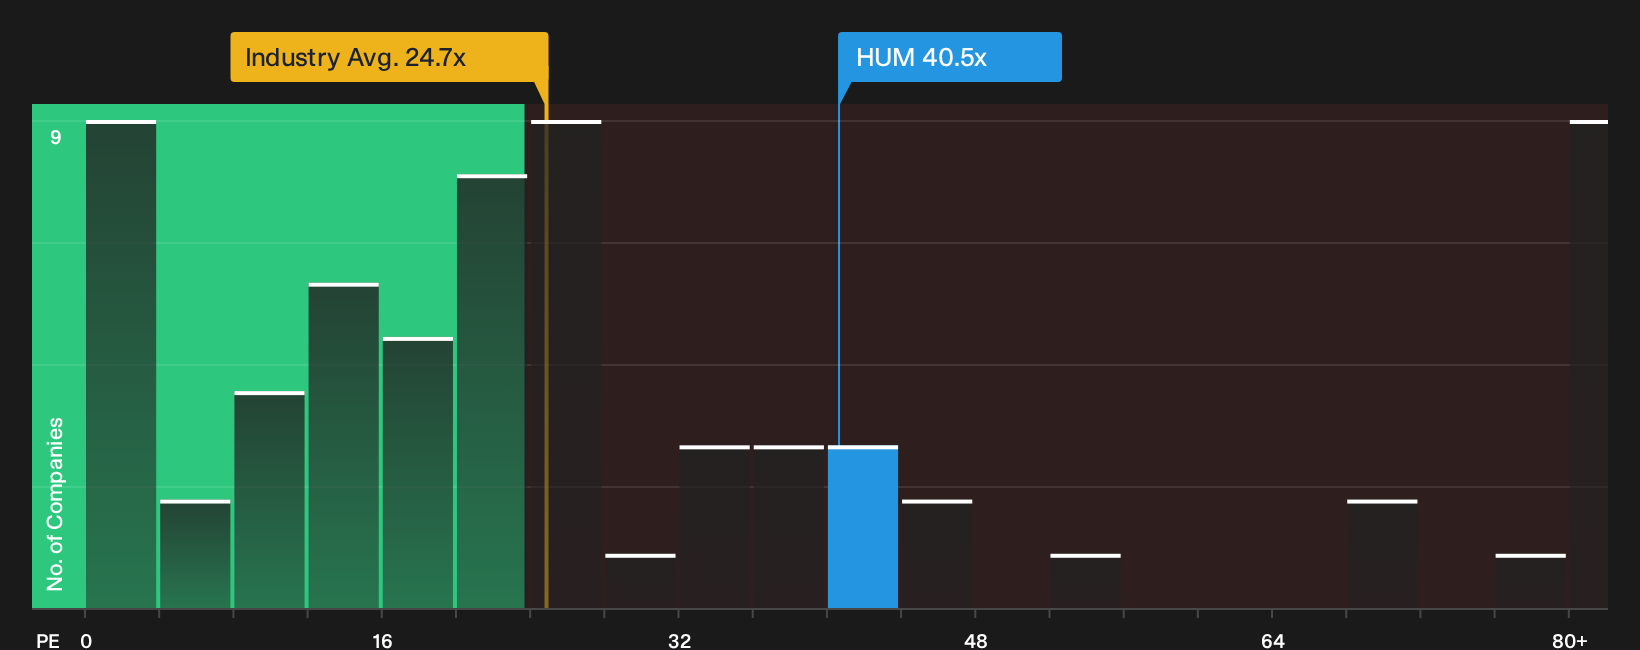
On simple earnings multiples, Humana tells a different story. The stock trades on a P/E of 40.5x, which is richer than both the US Healthcare industry at 24.7x and a peer average of 25.4x, even though the estimated fair ratio sits higher at 45x. That gap points to valuation risk if sentiment cools, but also leaves room if the market moves closer to the fair ratio. Which side of that trade off appears more realistic to you?
For a closer look at how this P/E profile compares with what the numbers imply, review See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed on the story so far, or feeling confident in your own angle on Humana after these moves and ratings shifts? Act quickly, review the opposing signals, and weigh both the upside and the downside through 2 key rewards and 2 important warning signs.
Looking for more ideas beyond Humana?
If Humana has sharpened your focus, do not stop here. Fresh opportunities often appear where the crowd is not yet looking.
- Target potential mispricing by scanning companies screened as 28 high quality undervalued stocks that combine quality fundamentals with more modest expectations baked into current prices.
- Strengthen the defensive side of your portfolio by reviewing 31 resilient stocks with low risk scores that score well on resilience and balance sheet stability.
- Get ahead of the herd by searching through 20 high quality undiscovered gems that pair solid financials with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com