
Lundin Gold (TSX:LUG) Record Output Puts Its Valuation Back In Focus
Lundin Gold (TSX:LUG) just posted its highest quarterly gold output since operations began at Fruta del Norte, with third quarter 2026 production and throughput grabbing investor attention ahead of a sales heavy fourth quarter.
The production update arrived alongside a sharp move in Lundin Gold’s share price, with the stock up 10.51% on the day and 8.91% over the past week. The year-to-date share price return is still down 14.33%, while the 5-year total shareholder return is close to 10x, indicating meaningful long-term wealth creation and suggesting that recent momentum may be rebuilding after a softer stretch.
Go beyond Lundin Gold’s breakout and identify other producers that are reporting strong output with the hand-picked 36 elite gold producer stocks.
Lundin Gold now has record output, a surging share price and a long runway of produced ounces still to be sold. Does that mix still skew the risk reward toward buyers at today’s valuation?
Most Popular Narrative: 40% Undervalued
Lundin Gold’s most followed narrative puts fair value at CA$96.25, almost level with the CA$95.82 last close, yet still frames the stock as undervalued when longer term cash flows are brought into the picture at a 7.8% discount rate.
The current valuation seems to price in a seamless and rapid expansion of the company's resource base and mine life, particularly through ongoing drilling at FDNS, FDN East, and the new porphyry corridor. This optimism assumes material reserve additions and life extension, which, if not realized, could lead to future revenue disappointment post-2030.
See why 42 investors see Lundin Gold as 0% undervalued.
Result: Fair Value of CA$96.25 (UNDERVALUED)
Still, the whole Lundin Gold narrative can be knocked off course if gold prices soften, or if its single Ecuadorian asset runs into political or regulatory friction.
Find out about the key risks to this Lundin Gold narrative.
Another View: What Lundin Gold’s P/E Is Saying
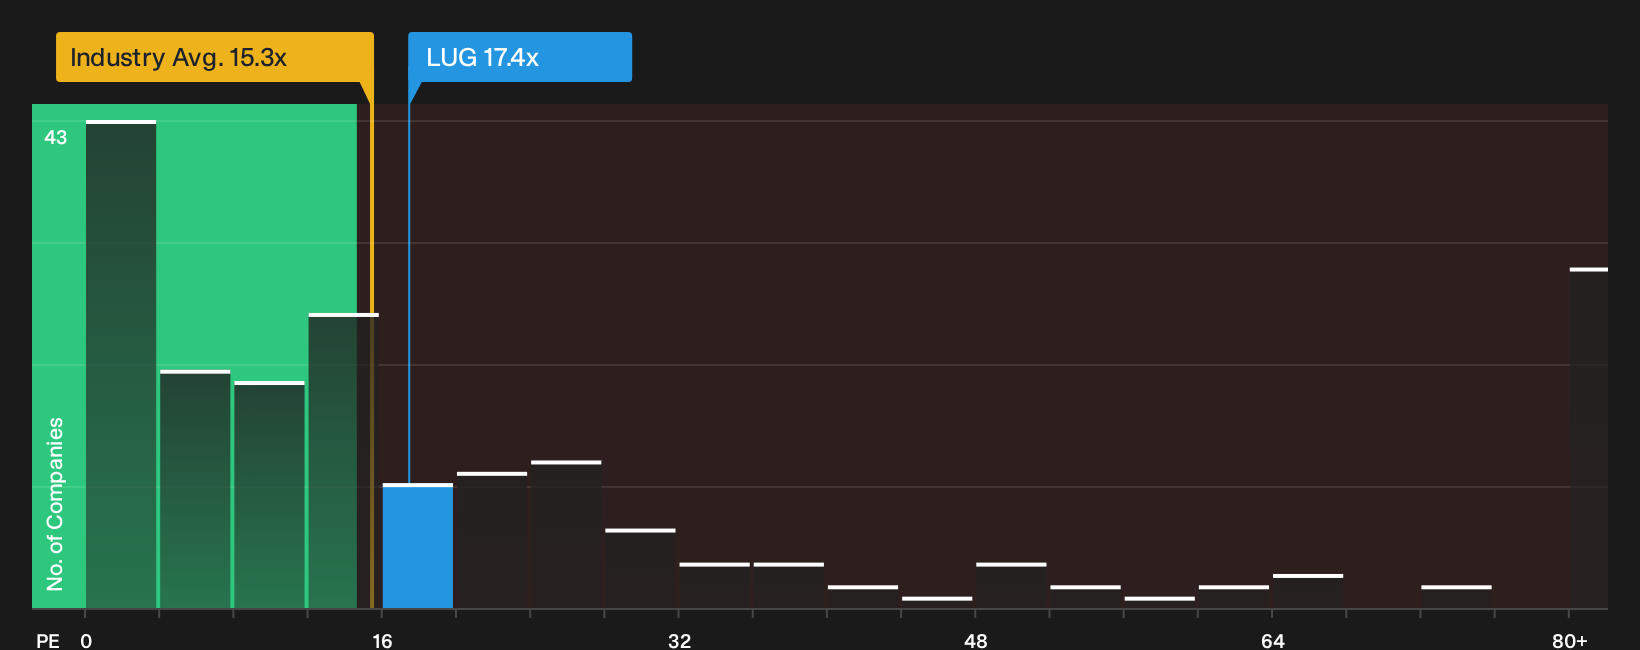
The SWS DCF model points to Lundin Gold trading at a discount to estimated future cash flows, yet the market price tells a different story when earnings are used as the yardstick. The stock trades on a P/E of 17.4x versus a fair ratio of 16x, and above the Canadian metals and mining average of 15.3x, which points to investors already paying a premium multiple for the business. If cash flow work signals value while earnings multiples lean rich, which lens do you trust more for your own decision?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Lundin Gold is split, with strong production and valuation debates on one side and clear risk flags on the other. Weigh those trade offs yourself, move quickly if you need to, and ground your view in the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Lundin Gold?
If you only focus on Lundin Gold, you could miss other opportunities that fit your style, match your risk limits, and line up with your return goals.
- Target deep value by scanning companies that screen well on quality and price with the 9 high quality undervalued stocks.
- Build a portfolio that works for income by reviewing potential high yield payers through the 3 dividend fortresses.
- Reduce potential downside risk by focusing on businesses with stronger finances in the list of solid balance sheet and fundamentals (7 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com