
G Mining Ventures (TSX:GMIN) Production Update Keeps Undervalued Narrative In Focus
G Mining Ventures (TSX:GMIN) drew fresh attention after reporting preliminary third quarter figures for its Tocantinzinho Gold Mine, including 44,960 ounces of gold produced and 43,110 ounces sold, alongside reaffirmed full year production guidance.
Recent trading suggests the latest Tocantinzinho update is feeding into stronger sentiment around G Mining Ventures. The share price is up 3.08% over one day and 18.08% over 90 days, while the 1-year total shareholder return of 60.42% and very large 5-year total shareholder return point to momentum that has built over time, even after a 6.01% decline in the 30-day share price return.
Scan how G Mining Ventures compares with other producers showing strong momentum and fundamentals using the hand picked 36 elite gold producer stocks in the same space.
After a Q3 production update that has already pushed G Mining Ventures higher over the past year, the real tension now sits in the price. The key question is whether the current valuation still skews the risk reward toward buyers, or whether most of the easy upside has been used up.
Most Popular Narrative: 21% Undervalued
On the current narrative, G Mining Ventures is priced below an internal fair value of about CA$62.08, compared with the last close at CA$49.25. This puts the spotlight on whether its project pipeline can justify that gap.
The company reports strong free cash flow from TZ and expects this cash flow to fund a large part of Oko West construction and a record exploration budget of about $46 million across the portfolio. This could support future revenue and free cash flow if new resources and projects move into production.
See why 10 investors see G Mining Ventures as 21% undervalued.
Result: Fair Value of CA$62.08 (UNDERVALUED)
Still, G Mining Ventures faces clear pressure points, including substantial capital spending at Oko West and full exposure to gold prices, which directly affect its cash flow.
Find out about the key risks to this G Mining Ventures narrative.
Another View: What G Mining Ventures’ P/E Is Telling You
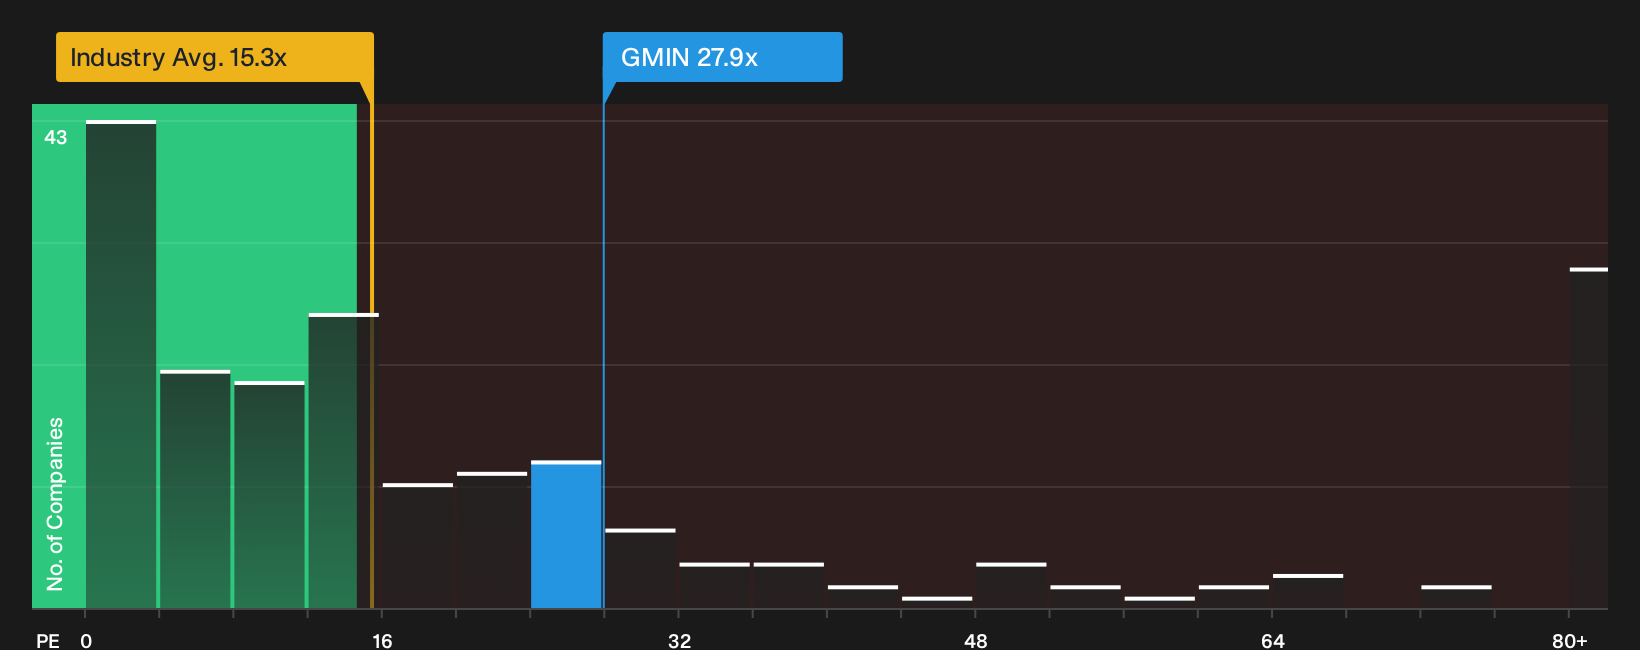
The story looks very different when you switch from fair value models to a simple earnings multiple. G Mining Ventures trades on a P/E of 27.9x, which is far richer than both the Canadian Metals and Mining industry at 15.3x and its peer group at 13.5x, and only slightly below a fair ratio of 29x. That gap suggests the market already prices in a lot of good news, so the question is how much margin for error is really left.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around G Mining Ventures can make this story feel finely balanced, so move quickly, study the data, and weigh both 4 key rewards and 3 important warning signs.
Looking For More Ideas Beyond G Mining Ventures?
If G Mining Ventures has sharpened your focus, now is the moment to widen your watchlist and uncover other opportunities before the crowd starts paying attention.
- Zero in on quality at a discount by scanning companies that pass a high bar for fundamentals through the 9 high quality undervalued stocks.
- Lock in potential income streams by checking out businesses with robust payouts using the 3 dividend fortresses.
- Strengthen your watchlist with companies that pair resilience and solid finances through the list of solid balance sheet and fundamentals (7 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com