
3 Defensive Dividend Stocks That Could Hold Up As Treasury Yields Rise
Bond yields are surging and the 10 year Treasury edging toward levels the market has not seen in decades. That kind of move can punish richly priced growth stories and reward investors who already hold sturdier, income focused stocks. In this article you will see three large cap dividend payers from a defensive equities screener that appear well placed or relatively insulated if funding costs stay elevated.
The three dividend stocks below are just a starting sample. The full defensive equities screen surfaced 8 more large cap companies with equally compelling income and value stories that are not covered here.
If you want to move straight from ideas to your own shortlist, use the US Large-Cap Value & High-Dividend Stocks (Defensive Equities) screener to identify candidates, analyze their fundamentals, and focus on the opportunities that best fit your risk profile.
UnitedHealth Group (UNH)
Overview: UnitedHealth Group is a large US healthcare company that provides insurance, care services, and pharmacy benefits to consumers and institutions.
Operations: UnitedHealth generates about US$346.5b from UnitedHealthcare and US$274.8b combined from Optum Health, Optum Rx, and Optum Insight, with eliminations reducing reported totals.
Market Cap: US$333.0b
UnitedHealth Group brings a healthcare tilt to this defensive equities screen, pairing scale and essential services with a dividend profile that leans more toward reliability than headline yield. This is the sort of ballast some investors look for when bond yields pressure riskier corners of the market.
"The current AI program targets billions of dollars of G&A savings through automation of claims, call handling, clinical documentation and back-office functions and is aimed at lifting net margins and operating earnings over time."
The real test for UnitedHealth Group is how one unresolved pressure on medical costs shapes the margin repair story investors are watching.
That margin tug of war is exactly what the full narrative for UnitedHealth Group unpacks in detail, including how management aims to keep earnings momentum accelerating beyond headline cost pressures.

AT&T (T)
Overview: AT&T is a large US telecom provider that offers wireless, broadband, and fiber services, aligning neatly with this defensive, income focused screen.
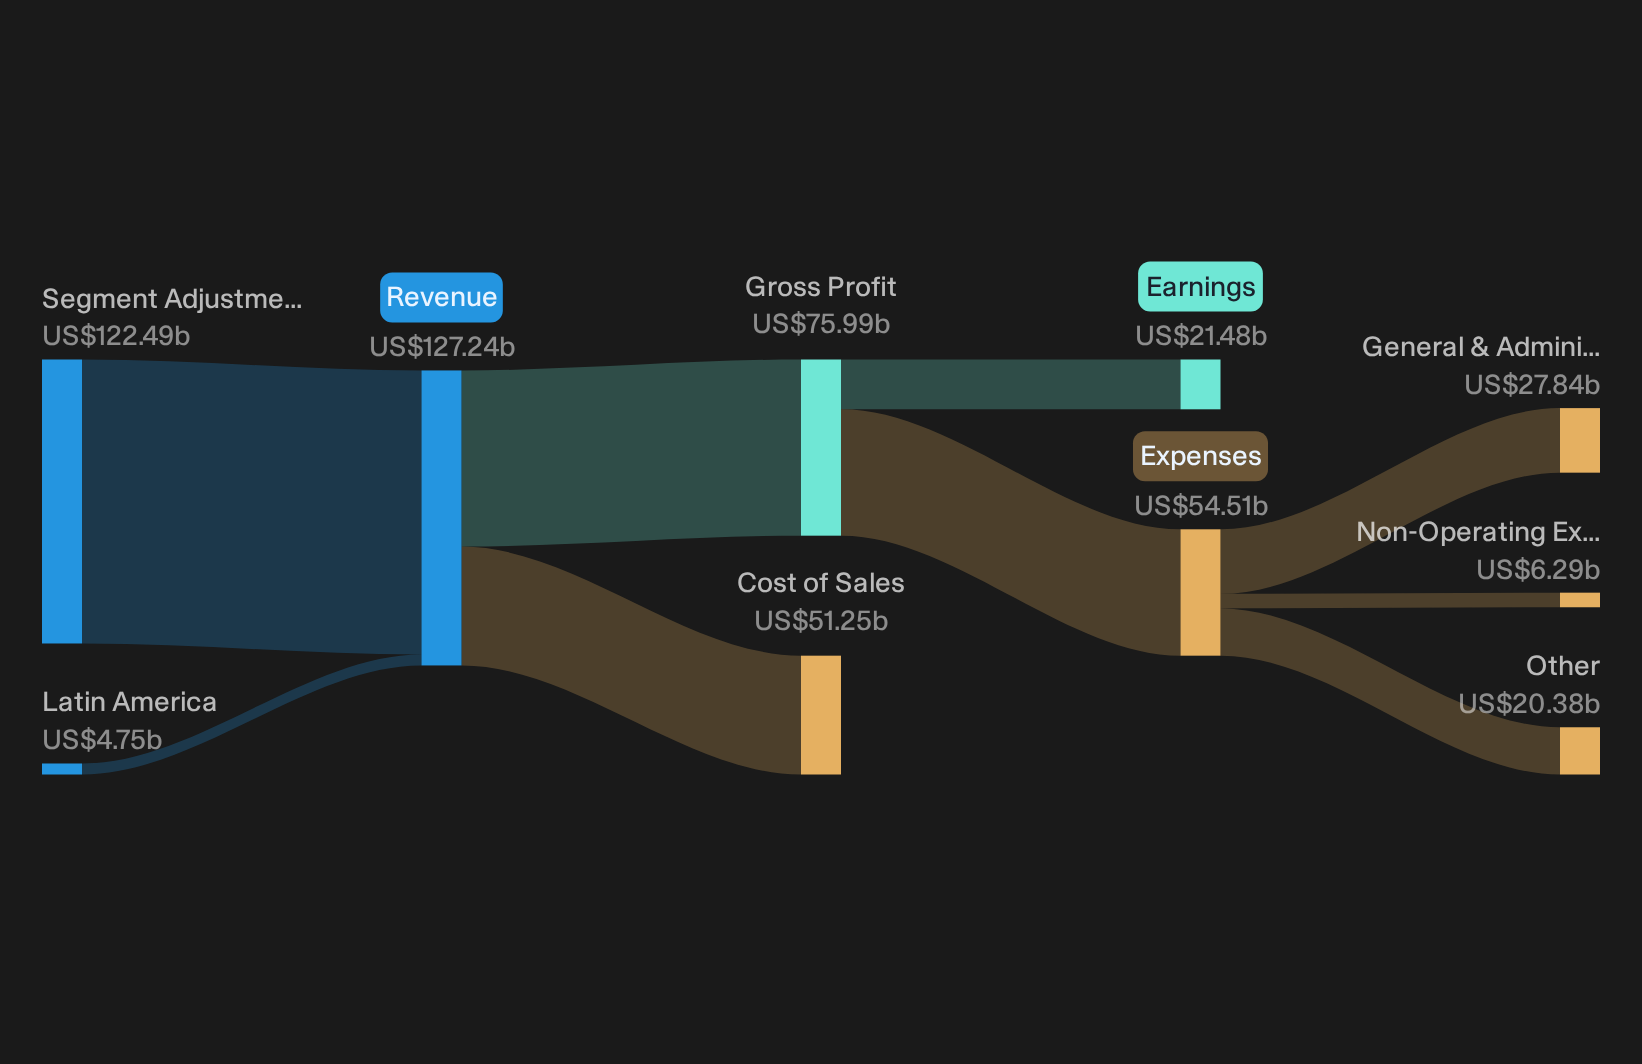
Operations: AT&T reports US$4.8b from its Latin America segment, with a US$122.5b segment adjustment reflecting its broader communications activities.
Market Cap: US$170.4b
AT&T brings a different sort of resilience to this dividend heavy list. It pairs critical connectivity services with a long running cash generation story that investors often consider when bond yields pressure more speculative growth ideas.
"Retirement of legacy copper and wireline infrastructure is moving forward, with plans to eliminate roughly US$6b of costs tied to copper networks and progress toward being able to discontinue copper in a large portion of the footprint."
The real question for AT&T is how far that shift away from legacy networks can push margins and free cash flow if a single key assumption breaks.
If that assumption shifts, the full narrative for AT&T lays out how AT&T’s fiber push, cost cuts, and capital choices could turn a slow grind into accelerating cash strength.
New Jersey Resources (NJR)
Overview: New Jersey Resources is a regulated natural gas utility with related energy services that supplies fuel and home services across several US states.
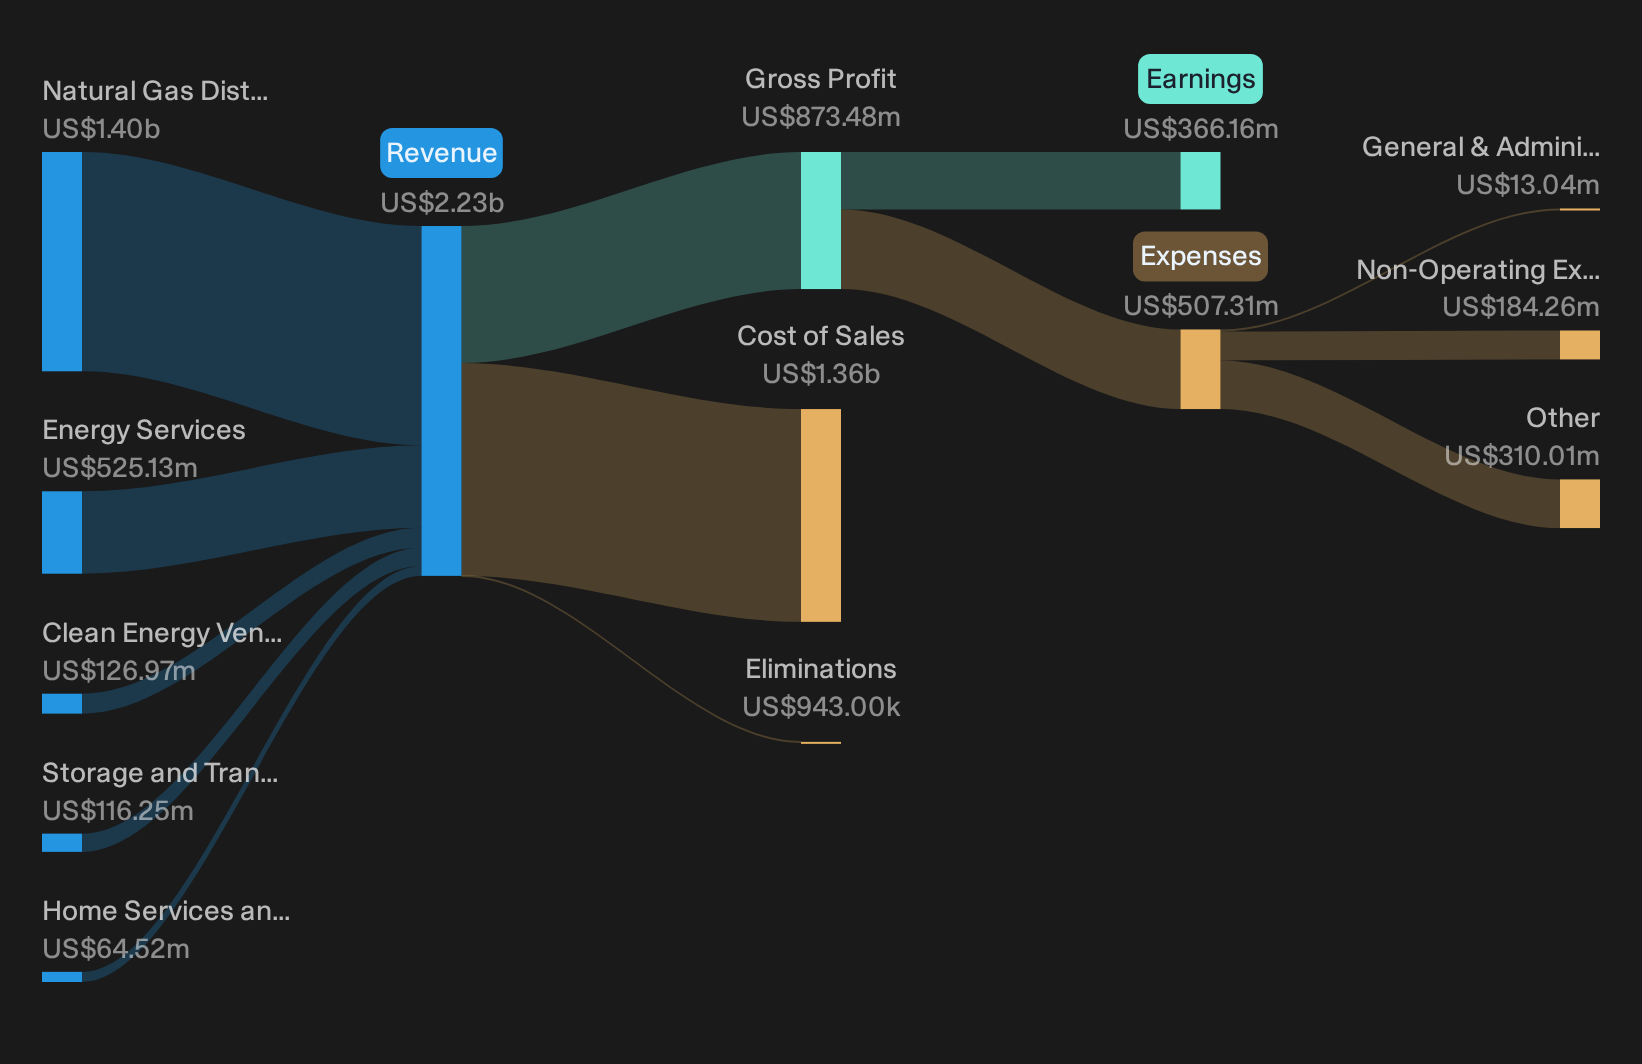
Operations: New Jersey Resources generates about US$1.4b from Natural Gas Distribution, with additional revenue from Energy Services, Clean Energy Ventures, Storage and Transportation, and Home Services.
Market Cap: US$5.2b
New Jersey Resources fits this defensive, dividend focused screen as a regulated gas utility that pairs recurring bill payments with a growing portfolio of fee based energy assets.
"New contracts and capacity additions at Adelphia Gateway and Leaf River are expected to more than double Storage & Transportation net financial earnings between fiscal 2025 and 2027. A FERC-approved plan to increase Leaf River working gas capacity by over 70% and long term fixed price, fee based agreements directly target higher future fee income and potentially a steadier contribution to overall earnings."
The key wildcard is how one funding and payout trade off shapes future dividend comfort if borrowing costs keep grinding higher.
If that trade off matters to you, the full narrative for New Jersey Resources shows how New Jersey Resources balances higher funding costs with regulated cash flows and accelerating fee income potential.
Seeking Alternatives Before The Crowd?
Fresh ideas often move first. Breakout themes, new momentum, and quietly dropping valuations rarely stay under the radar for long. Scan what others might miss and consider your options.
- Look for early strength in smaller companies by reviewing the curated 31 resilient stocks with low risk scores that aim to keep downside pressure in check.
- Monitor where infrastructure demand may develop by scanning the hand picked 43 power grid technology and infrastructure stocks that focus on grid technology and critical upgrade spending.
- Follow the data center build out by reviewing the focused 92 AI infrastructure stocks targeting backbone suppliers to AI demand.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com