
Senior Notes Sale Could Matter For Atmos Energy Stock (ATO)
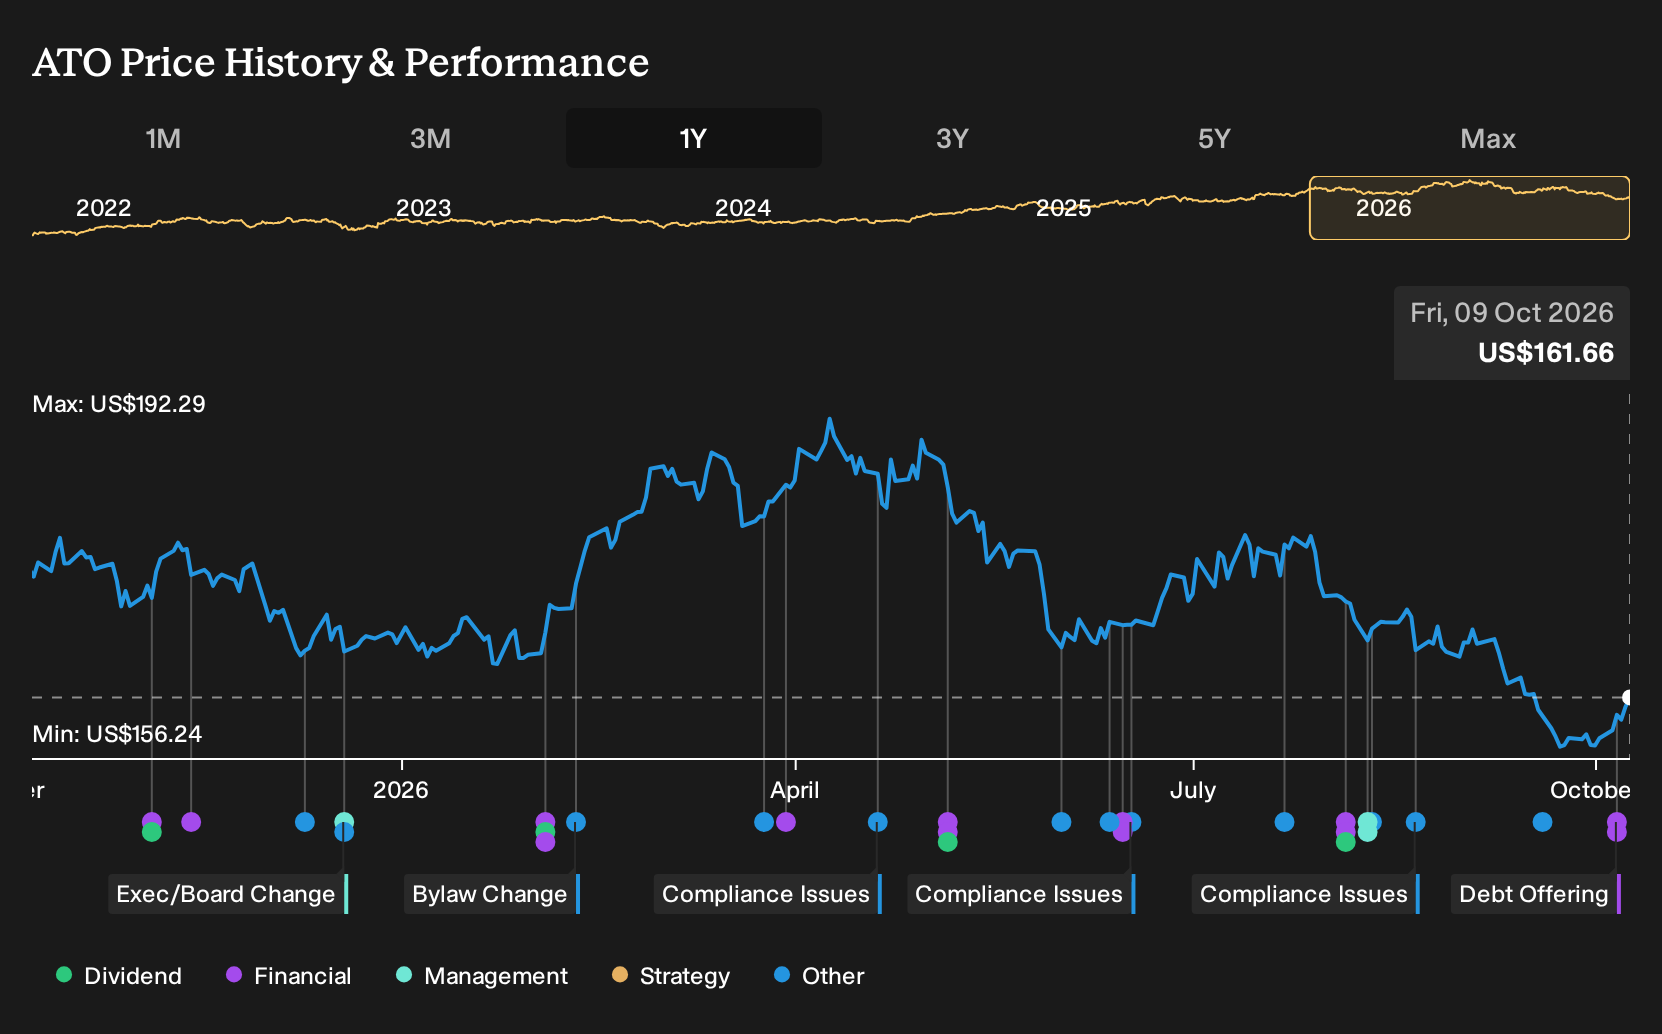
- Atmos Energy completed a US$697.466 million fixed income offering of 6.000% senior unsecured notes due 2036, issued at 99.638% of par with callable features and a fixed coupon.
- The new 6.000% senior notes provide another funding option for Atmos Energy as it balances safety-related capital expenditures with higher ongoing operations and maintenance costs.
- This review considers how Atmos Energy's investment narrative relates to the new 6.000% senior note funding and the company’s execution priorities.
Scan how Atmos Energy’s financing move compares with peers by running utility-focused filters through our curated list of list of solid balance sheet and fundamentals (25 results).
Atmos Energy Investment Narrative Recap
To own Atmos Energy, you need to be comfortable with a regulated utility that is heavily investing in its pipes and safety systems while carrying a large, ongoing capex plan around US$4.2b for fiscal 2026. The thesis leans on the business converting customer growth, supportive Texas regulation and prior rate actions into steady earnings, while keeping operational incidents contained.
The key near term swing factor is how efficiently Atmos Energy executes that capex while managing guided operating and maintenance spending of US$875 million to US$885 million. The fresh 6.000% senior notes do not fundamentally change that equation. However, funding execution helps reduce near term pressure as external financing needs remain high.
The new US$697.466 million 6.000% senior unsecured notes due 2036 matter because they directly connect to that heavy 2026 investment slate, most of which is earmarked for safety, reliability and modernization. Fresh long term funding supports the build out of the regulated asset base, which underpins future rate filings and operating income potential.
There is a flip side. Analysts flag that debt is not well covered by operating cash flow and that the dividend is not well covered by free cash flows, so more borrowing at a 6.000% coupon heightens the need for clean execution. For you, the practical question is whether Atmos Energy can keep converting customer additions, Texas legislation and recent rate outcomes into enough earnings to comfortably support this thicker capital stack.
Atmos Energy Analyst Assumptions Behind The Story
Analysts currently build their Atmos Energy models around revenue expanding by 10.6% a year over the next three years, with profit margins moving from 28.5% today to 29.0% by 2029. On that framework, earnings are forecast to rise from US$1.4b today to US$1.9b by 2029, which is roughly a US$500m increase, while consensus views on these forecasts are described as relatively aligned.
On the valuation side, those same projections imply Atmos Energy would generate about US$6.7b of revenue and US$1.9b of earnings by 2029 and trade on a P/E of 22.8x, compared with 19.1x today and 16.1x cited for the broader US gas utilities group. For you as an investor, the focus is less on the exact target price and more on whether revenue growth near 10.6% and a higher future P/E multiple appear realistic in light of the heavy infrastructure program and the regulated returns that frame this business.
Atmos Energy's narrative projects US$6.7b revenue and US$1.9b earnings by 2029. This assumes 10.6% yearly revenue growth and roughly a US$500m earnings increase from US$1.4b today.
Uncover why Atmos Energy's fair value indicates a 15% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community span roughly US$134 to US$186 per Atmos Energy share, so you are looking at a wide gap between the lowest and highest private estimates. Set that against heavy 2026 capex, rising O&M guidance and ongoing legal scrutiny, then decide which narrative feels more convincing.
Explore another Atmos Energy fair value estimate, including one that suggests up to 15% potential upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Atmos Energy research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Atmos Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Atmos Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond Atmos Energy?
Once you have a view on Atmos Energy, it can help to set it alongside other opportunities with different risk profiles, income characteristics and balance sheet strengths. The Simply Wall St Screener lets you do that quickly by zeroing in on focused groups of stocks that match the type of portfolio you want to build.
- For investors who want potential upside but still care about financial resilience, you can filter for companies with strong fundamentals using our 20 high quality undiscovered gems.
- If capital preservation sits high on your priority list, you can narrow your universe to steadier profiles through the 31 resilient stocks with low risk scores.
- When reliable balance sheets matter most, you can compare Atmos Energy with peers that show similar financial footing by scanning the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com