
PC Connection (CNXN) Earnings Beat Puts Fair Value Back In Focus
PC Connection (CNXN) moved into focus after its latest quarterly update showed revenue rising 12.4% year on year, with both sales and earnings per share topping analyst expectations during a strong period for IT distribution and solutions.
The recent quarterly beat has come alongside a sharp re-rating in the market, with PC Connection’s share price up 12.18% over 30 days and 20.14% over 90 days. The year-to-date share price return of 63.17% and 1-year total shareholder return of 58.45% point to momentum that has been building rather than fading.
Scan for other IT solution providers that are showing similar earnings momentum and sector tailwinds through our curated list of 20 high quality undiscovered gems.
PC Connection has already delivered a powerful run, yet the current price still implies a sizeable intrinsic discount. Has most of the upside been pulled forward, or is the market only partway through repricing this story?
Price-to-Earnings of 24.4x: Is it justified?
PC Connection now trades on a P/E of 24.4x, with the recent share price strength lifting the multiple above both its own fair ratio estimate and the peer average.
The P/E ratio compares the current share price to earnings per share, so it shows how much investors are paying for each dollar of profit. For an IT solutions distributor such as PC Connection, that yardstick often reflects how durable the earnings base looks and how much confidence there is around future profit growth.
At 24.4x earnings, the stock is described as expensive compared to the peer average of 22.1x and also sits above the estimated fair P/E of 20.1x. That suggests the market is paying a premium for PC Connection relative to both its peer set and the level the ratio could move towards if expectations cool.
Against the broader US Electronic industry, the picture shifts, because the sector average P/E is 29.9x. On that yardstick CNXN is framed as good value, since investors are paying a lower multiple than the wider group even after the recent rally.
Explore the SWS fair ratio for PC Connection.
Result: Preferred multiple of 24.4x price-to-earnings (OVERVALUED).
Still, the PC Connection story can be challenged if IT hardware demand softens, or if public sector and enterprise budgets tighten faster than expected.
Find out about the key risks to this PC Connection narrative.
Another view on PC Connection’s value
The P/E angle paints PC Connection as slightly expensive, yet the SWS DCF model points in the opposite direction. With the shares at $92.81 and an estimated future cash flow value of $419.88, that model frames the stock as heavily undervalued. Which signal do you trust when they disagree this sharply?
Look into how the SWS DCF model arrives at its fair value.
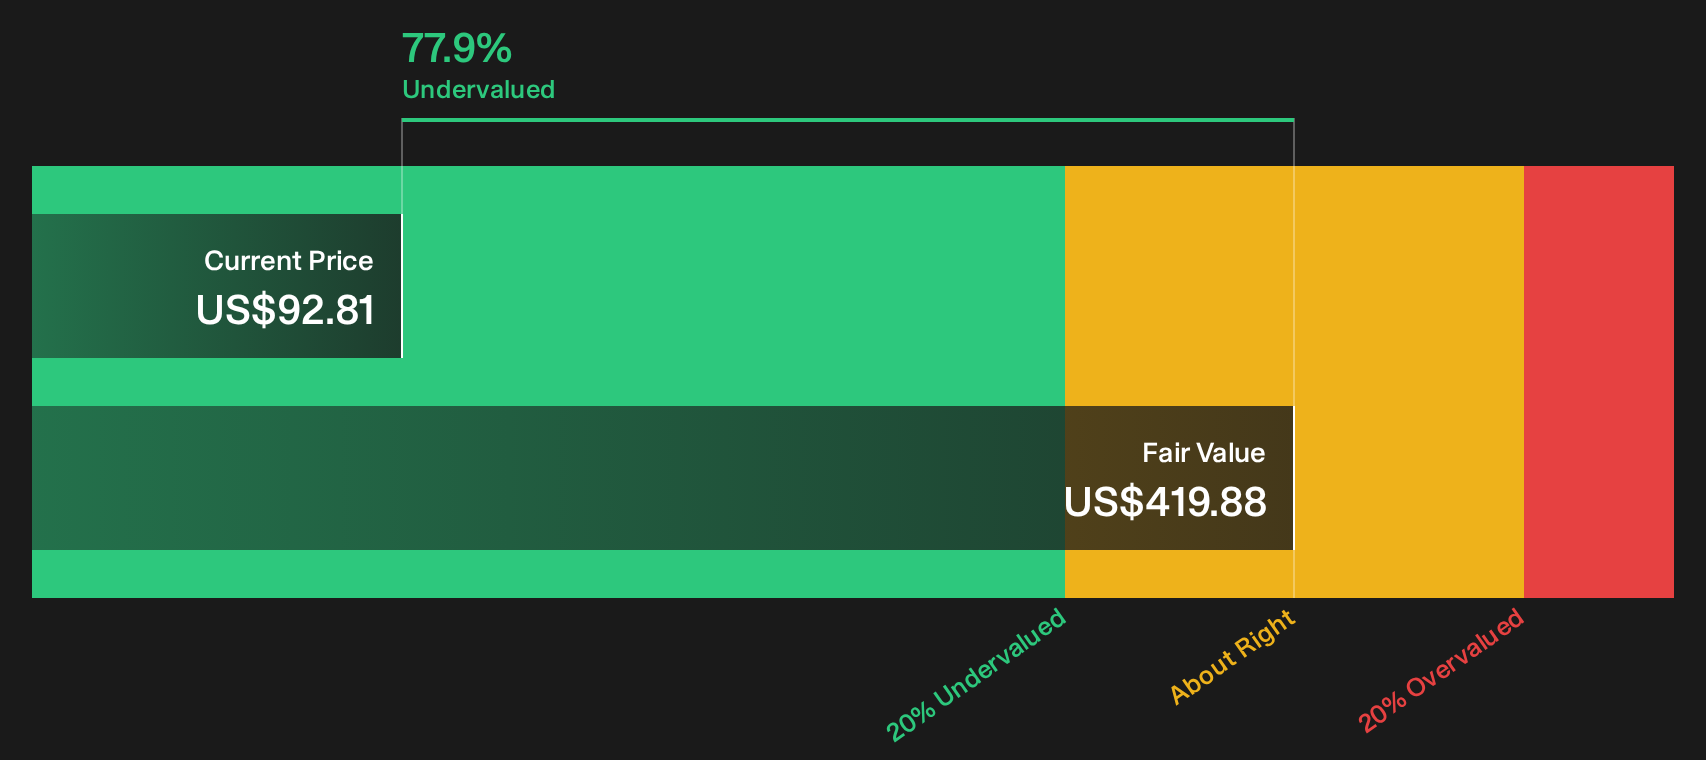
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out PC Connection for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around PC Connection is clearly mixed, with strong price action set against both flagged risks and identified strengths. Move quickly, pull up the key data points, and weigh the 3 key rewards and 1 important warning sign
Looking for more PC Connection sized opportunities?
If PC Connection has sharpened your focus, do not stop here. Broaden your watchlist with other ideas that match clear financial rules and tailored risk profiles.
- Target potential mispricing by scanning for quality companies trading below their implied worth through our curated 28 high quality undervalued stocks.
- Build an income focused portfolio by filtering for resilient businesses in our carefully selected 8 dividend fortresses.
- Prioritise capital protection by zeroing in on companies that score well on financial resilience using the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com