
How Earnings Outlook At Archer Daniels Midland Has Changed Its Investment Story
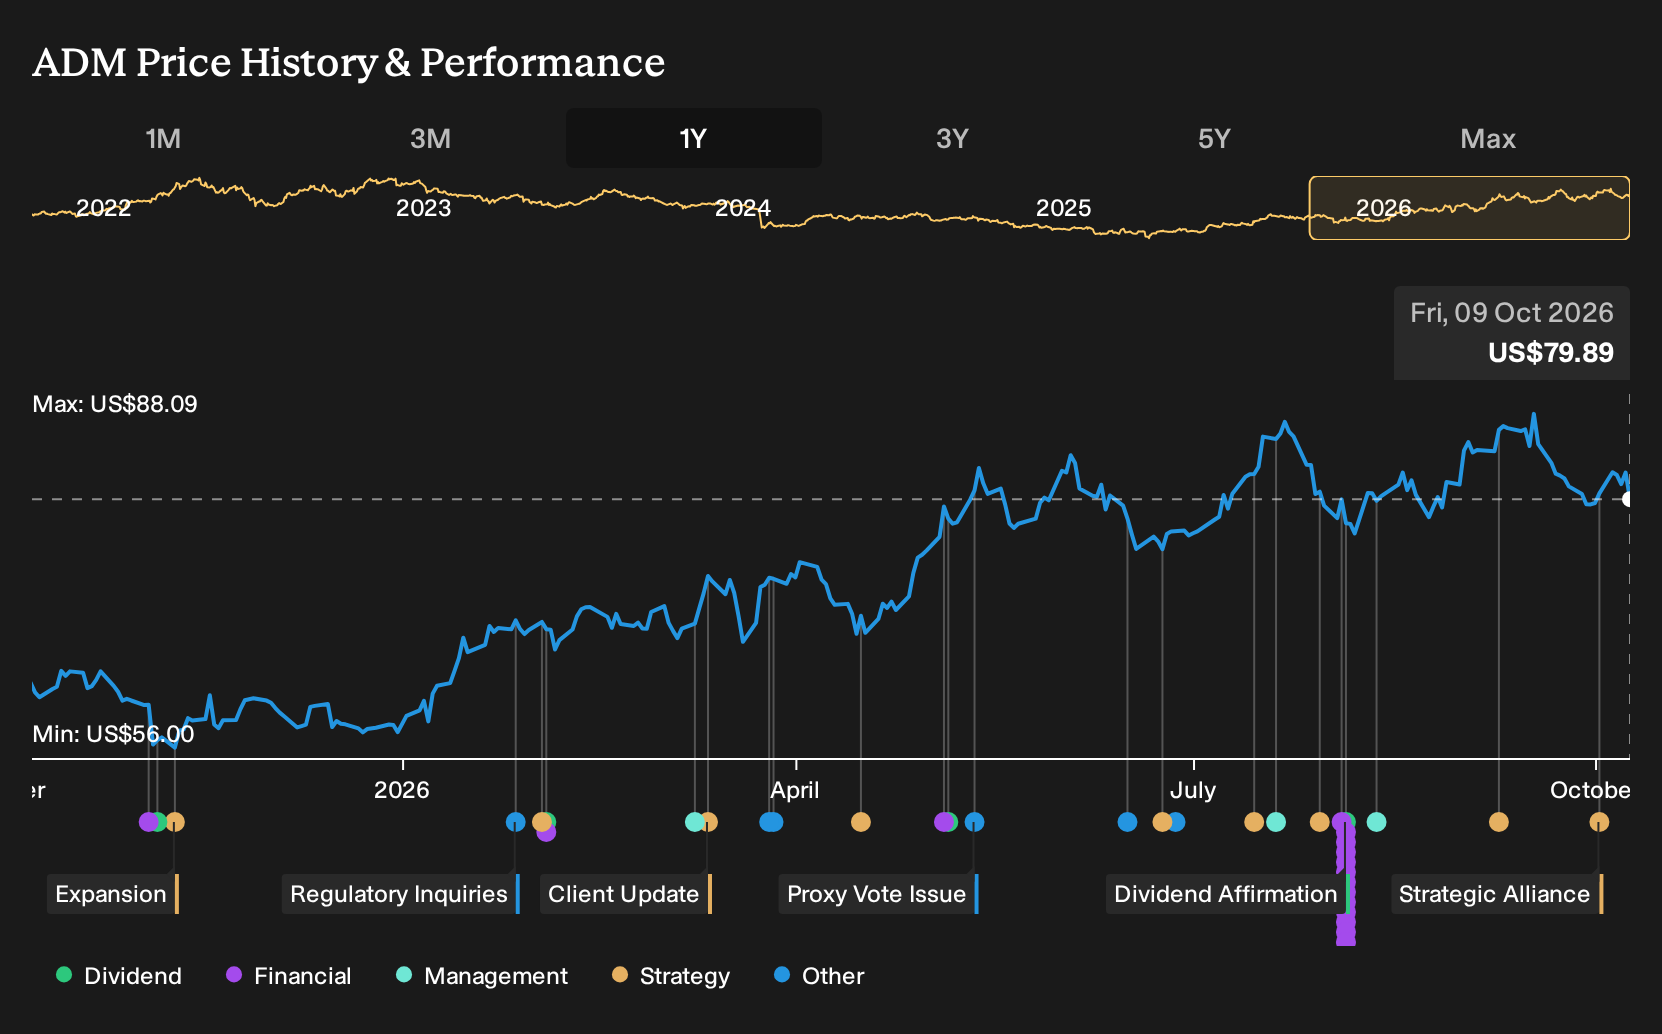
- CJ CheilJedang and Archer-Daniels-Midland formed a joint venture to produce and sell fermentation-based feed-grade amino acids across the Americas, combining plants in Iowa, Illinois and Brazil with CJ’s regional sales network and intellectual property.
- The agreement ties Archer-Daniels-Midland’s U.S. production footprint directly into livestock nutrition supply chains, which can affect utilization rates, cost efficiency and resilience in its broader Nutrition and feed operations.
- We will now look at how Archer-Daniels-Midland’s investment narrative could be influenced by the new feed-grade amino acid joint venture.
Scan Archer-Daniels-Midland’s joint-venture catalyst against other agribusiness and food-security plays by running through our hand-picked list of solid balance sheet and fundamentals (25 results).
Archer-Daniels-Midland Investment Narrative Recap
To stay comfortable as a shareholder in Archer-Daniels-Midland, you need to believe the core crush, biofuels and Nutrition engines keep doing their job while cost programs steadily lift efficiency. The recent CJ joint venture fits that picture by leaning into fermentation and animal nutrition, but it does not change the fact that execution on higher margin Nutrition and cost savings remains the key short term test.
The bigger risk still sits in the combination of margin pressure in Carbohydrate Solutions, potential earnings volatility from macro shocks and lingering governance questions after the former CFO litigation. The new amino-acid platform can add some operational resilience in feed ingredients, yet it does not materially dilute those headline risks.
The CJ CheilJedang joint venture is the announcement that most clearly links to Archer-Daniels-Midland’s existing catalyst list. It expands fermentation based offerings and plugs directly into animal nutrition, which already features as a growth focus alongside higher margin flavors, specialty ingredients and color solutions in the Nutrition segment.
For catalysts, you are effectively layering this venture on top of planned crush debottlenecking, the 45Z biofuel credit expectations and enterprise wide cost simplification. The amino-acid footprint could help ADM deepen customer relationships in feed, but investors still have to watch how consistently management delivers on the targeted US$500 million to US$750 million in cost savings and the shift in mix toward value added Nutrition.
What The Joint Venture Has To Earn Against
Archer-Daniels-Midland's new amino acid venture now sits alongside a consensus narrative that already bakes in measured improvement. Analysts are working off revenue growth assumptions of 2.8% a year and a lift in profitability rather than a sharp reset. That context matters when you weigh how much extra credit to give the CJ CheilJedang partnership.
Forecasts point to earnings of US$2.3b by 2029, compared with earnings today of US$1.8b. That implies an earnings increase of about US$0.5b on current consensus numbers, with margin expansion from 2.2% to 2.5% doing some of the heavy lifting alongside modest top line growth. Any incremental contribution from fermentation based feed ingredients effectively has to slot inside that US$0.5b earnings bridge or justify analysts pushing the ceiling higher.
Valuation work already links those 2029 estimates to revenues of US$89.2b and assumes Archer-Daniels-Midland trades on a P/E of 21.3x in that same year. That is higher than the current quoted multiple for the wider US Food industry at 17.3x, so the stock already carries a quality and execution premium in the consensus view. For you as a shareholder, the key question is whether the new joint venture strengthens the case for that premium or simply adds another moving piece to an already busy earnings story.
Archer-Daniels-Midland's narrative projects revenues of US$89.2b and earnings of US$2.3b by 2029. This rests on 2.8% yearly revenue growth and an earnings increase of about US$0.5b from earnings today of US$1.8b.
Discover why Archer-Daniels-Midland's fair value appears to be largely consistent with its current price.
Exploring Other Perspectives
You can look at the CJ joint venture through a different lens. The most pessimistic Archer-Daniels-Midland analysts focus on slower revenue growth of about 1.2% a year and earnings of roughly US$2.4b by 2029. Those views were set before this alliance, so your own stance may shift as new information settles in.
Explore 3 other Archer-Daniels-Midland fair value estimates, including one that suggests it could be worth just $80.10.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Archer-Daniels-Midland research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Archer-Daniels-Midland. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Archer-Daniels-Midland's overall financial health at a glance.
Looking For More Investment Ideas Beyond Archer-Daniels-Midland?
If the Archer-Daniels-Midland story has sharpened your thinking, use that momentum to broaden your watchlist with other businesses that line up with your preferred balance of quality, risk and income.
- For investors who want strong fundamentals first, a curated list of solid balance sheet and fundamentals (25 results) can help you focus on businesses with sturdier financial footing.
- If value is your priority, a targeted sweep through 28 high quality undervalued stocks can surface stocks where pricing and quality appear out of sync.
- Income focused readers can zero in on potential cash flow streams by reviewing 8 dividend fortresses that emphasize higher yields with an emphasis on resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com