
Property Value Falls Could Be A Game Changer For REA Group Stock
- Recent reporting from REA Group highlights broad property value declines across Australia, tighter rental markets, and shifting buyer and tenant behaviour under higher interest rates and new tax settings.
- The breadth of value falls, from prestige enclaves to working class suburbs, points to a housing cycle that is now testing REA Group’s listing volumes and pricing power across multiple customer segments at once.
- We will now explore how this broad based housing downturn, driven by higher rates and tax reform, could reshape REA Group’s investment narrative.
REA Group Investment Narrative Recap
To own REA Group, you need to believe its core portals and data services can stay central to how Australians search, rent, buy and finance property, even when prices and sentiment soften. The broad value declines and tighter rental markets hit both listing volumes and advertiser budgets, so the near term swing factor is how quickly volumes stabilise across key states.
The biggest short term risk is that this housing downturn drags on, which would keep listings subdued while agents push back on premium upsells. At the same time, REA Group’s push into financial services and India gives it extra levers, but those only help if the Australian classifieds engine holds its audience and pricing.
The most relevant thread in recent reporting is REA Group’s own data showing that more than 80% of suburbs saw value falls over the past quarter, with similar patterns across Adelaide, Queensland and Melbourne. That breadth of weakness matters for the thesis, because REA’s A$1.6b Australian property and online advertising segment is highly exposed to vendor confidence and transaction churn.
For catalysts, that same data set can work both ways. If listing volumes in pressured markets such as Melbourne and Adelaide start to rebuild off these lower price points, REA Group’s premium listing packages and audience tools could see renewed uptake. If distress listings continue to rise and agents cut spend, the focus shifts to how well management can lean on cost control and adjacent revenue streams like mortgage broking.
REA Group's current analyst narrative points to A$2.3b in revenue and A$984.2m in earnings by 2029. This implies forecast revenue growth of 5.1% per year and an earnings increase of about A$311m from current earnings of A$673.0m.
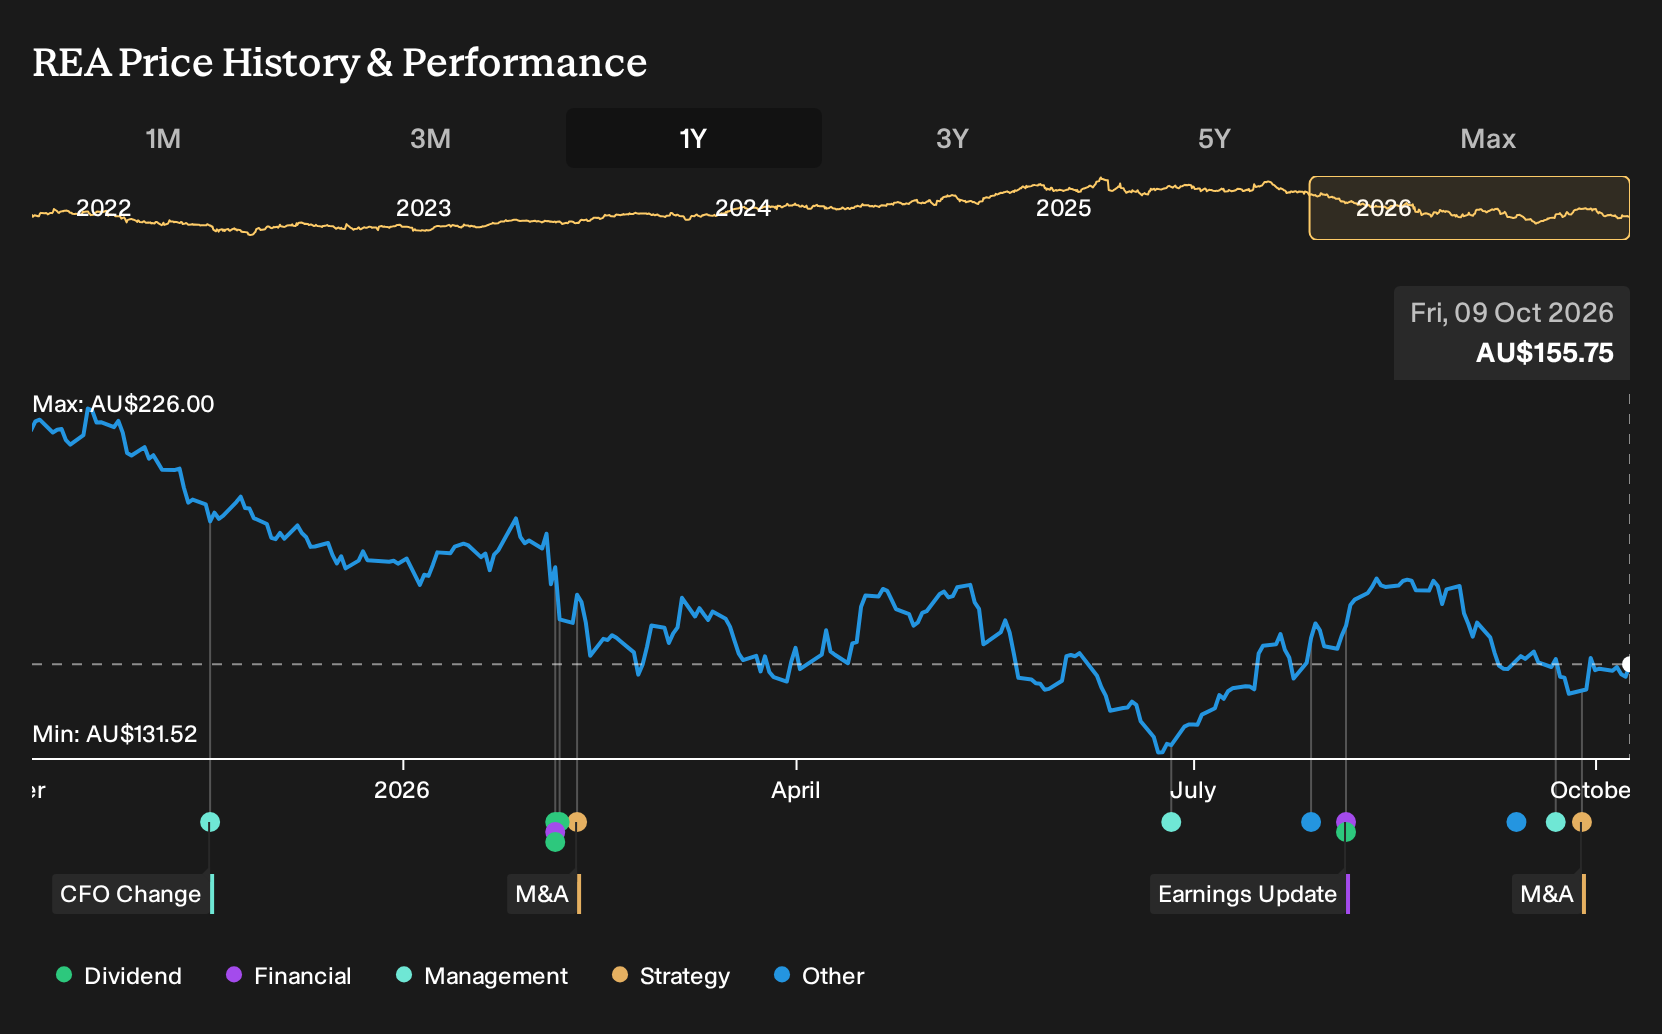
Uncover why REA Group's fair value indicates a 24% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle on REA Group focuses on the risk that softer housing conditions and tight rentals keep listing activity weak for longer than consensus expects. The most cautious analysts were only pencilling in A$2.2b of revenue and A$890.8m of earnings by 2029 before this news, so their narrative is already materially more pessimistic. These views show how far opinions can spread and invite you to weigh several forecasts that may shift again once this broad downturn and rental stress are fully reflected.
Explore 6 other REA Group fair value estimates, including an estimate that suggests it could be worth just A$148.00.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your REA Group research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for REA Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate REA Group's overall financial health at a glance.
Looking for more investment ideas beyond REA Group?
Once you have a view on REA Group, it can help to widen the lens and line it up against other opportunities that fit different portfolio goals.
- For investors hunting for strong balance sheets and robust fundamentals, start with a list of solid balance sheet and fundamentals (12 results) that can help you stress test quality under tougher conditions.
- If value is your priority, use the 4 high quality undervalued stocks to surface companies where current pricing sits below their assessed fundamentals.
- Income focused portfolios can benefit from steady cash returns, so run your eye over a 6 dividend fortresses that concentrates on higher yielding payers with room to sustain payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com