
DSV (CPSE:DSV) Could Be 47% Undervalued Following J.P. Morgan Downgrade
DSV (CPSE:DSV) is back in focus after J.P. Morgan downgraded the freight forwarder to neutral, cutting earnings forecasts and highlighting deeper than expected profit pressure and operational issues in the Road division.
The J.P. Morgan downgrade comes after a difficult period for DSV shareholders, with the share price down 29.71% over the past 90 days and 27.09% year to date. The 1-year total shareholder return has declined 9.63%, despite recent sustainability partnerships and asset sale and leaseback initiatives that have kept the investment story active.
Scan freight and logistics peers that analysts view as potential rebound candidates with 174 high quality undervalued stocks following DSV's downgrade and sharp share price reset.
After a near 30% slide in three months and a fresh downgrade hanging over the Road division, DSV now presents a tougher question: Does today's reset price still compensate you for those operational and earnings risks?
Most Popular Narrative: 47% Undervalued
On one side, DSV closed at DKK1,166.5. On the other, the most followed valuation narrative points to a fair value near DKK2,195, using a 6.36% discount rate and a long term earnings outlook that contrasts sharply with the recent drawdown.
DSV just pulled off the biggest deal in its history, the Schenker acquisition, instantly making it the world's #1 freight forwarder. That is not just a headline, it is a game changer for pricing power, scale, and cross selling.
See why 4 investors see DSV as 47% undervalued.
According to Bejgal, the narrative rests on DSV continuing to compound earnings under a familiar playbook, integrating Schenker after UTi, Panalpina and Agility, and eventually earning a valuation multiple that reflects that track record. The thesis assumes revenue expansion of 7.91% per year, earnings reaching DKK23b by 2029 and a 28x P/E on those profits, discounted back at 6.36% to reach a fair value of DKK2,194.89.
Analyst expectations tell a different story from the recent share price slide. Consensus points to earnings growth of 27.41% per year over the next three years, which is described as significant and faster than the wider Danish market, even as revenue is forecast to expand 2.6% each year, slower than both the local market and the logistics sector. That sets up a clear tension. The market has punished the stock, while both this narrative and analyst models still assume a sharp profit recovery from a year in which earnings fell 29.5% and net margins moved from 5.3% to 2.5%, partly influenced by a DKK6.6b one off loss.
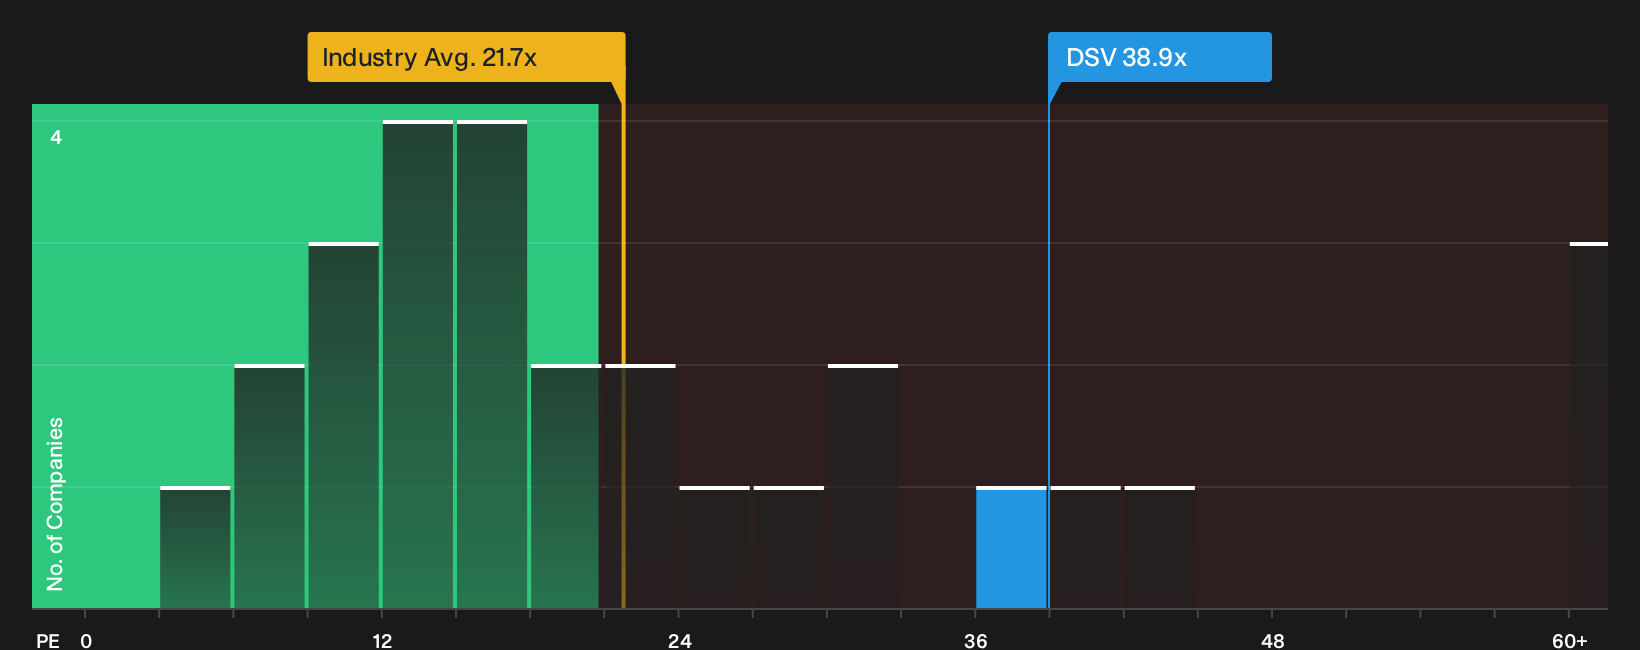
Valuation views are also mixed. On one hand, Simply Wall St’s DCF estimate places DSV at a future cash flow value of DKK2,269.21, and the fair P/E ratio implied by regression work is 49.7x, both framing the current 38.9x P/E as inexpensive relative to those models. On the other hand, the same 38.9x multiple looks expensive compared to the European logistics industry average of 21.5x and a peer average of 21.2x, while DSV’s 6% return on equity is described as low and forecast to remain subdued at 16.6% in three years.
For investors weighing the downgrade against this 47% discount narrative, the tension is clear. There is a DKK7160m net income base reported on DKK290,772m of revenue, earnings forecasts that point sharply higher, and a long list of qualitative risks that range from Schenker integration to higher risk funding and volatile recent trading. Whether DKK1,166.5 offers enough compensation for that mix of growth hopes and operational pressure is the crux of the reset.
Result: Fair Value of DKK2,194.89 (UNDERVALUED)
Still, the narrative can crack if Schenker integration drags on performance or if DSV’s current 38.9x P/E compresses toward typical sector levels.
Find out about the key risks to this DSV narrative.
Another View: DSV Through The P/E Lens
The SWS DCF model and Bejgal's fair value both point to DSV shares trading at a discount, yet the P/E picture tells a tougher story. DSV trades on 38.9x earnings, while the European logistics group is at 21.5x and peers average 21.2x, even though the fair ratio is 49.7x. That gap suggests plenty of valuation risk if sentiment keeps leaning toward the sector rather than the model. The key question is which reference point investors might prioritize when earnings are still under pressure.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals run through this DSV story, so move quickly to test the numbers, weigh both sides and decide if the 3 key rewards and 4 important warning signs match your own view.
Looking For More Investment Ideas Beyond DSV?
If DSV has sharpened your focus on valuation and risk, do not stop here. Broaden your watchlist now or you could miss cleaner setups elsewhere.
- Target quality at a discount by scanning companies that combine stronger fundamentals with attractive pricing through the 174 high quality undervalued stocks.
- Build a steadier income stream by assessing businesses with robust payouts using the 223 dividend fortresses.
- Tilt your portfolio toward resilience by focusing on sturdier balance sheets and healthier financial profiles with the list of solid balance sheet and fundamentals (204 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com