
How Fusion Partnership Will Impact Fuji Electric Stock Investors
- Fuji Electric has joined fusion startup Helical Fusion as both an investor and Official Partner in the Helix Program, which targets commercially viable fusion power in the 2030s and aims for integrated demonstration and eventual net electricity generation.
- The move connects Fuji Electric directly to next generation clean energy hardware development. This could influence how its power electronics, grid solutions, and plant systems evolve for future utility scale fusion projects.
- The focus now turns to how Fuji Electric's investment and partnership in Helical Fusion could reshape the broader investment narrative around energy solutions.
Scan curated peers positioned for the same fusion and power grid transition that Fuji Electric is targeting by checking out the 43 power grid technology and infrastructure stocks
Fuji Electric Investment Narrative Recap
To consider Fuji Electric, you need to believe its mix of energy systems, semiconductors, and industrial solutions can keep turning long term electrification demand into steady earnings, despite modest forecast growth and heavy exposure to Japan. The Helical Fusion news connects to that clean power story, but it does not change the near term earnings setup in a material way.
The short term outcome still depends on grid projects, semiconductor utilization, and cost control after capacity build out. Margin pressure, FX swings, and softer overseas demand remain the key operational risks. Fusion is more of an option on future relevance than a driver of the next few years.
With no major new filings or guidance changes tied directly to Helical Fusion, the most relevant context is the existing focus on energy management and power supply systems. That part of Fuji Electric already targets grid stabilization, storage, and data center demand. These are practical near term arenas where any fusion learning could eventually plug in.
For potential catalysts, the important question is whether order intake and backlog in those energy and industry segments continue to support earnings growth forecasts around 8.4% a year. Execution risk lies in converting large projects into profitable revenue while fixed costs from new semiconductor capacity and overseas headwinds do not erode the benefit.
Fuji Electric's narrative projects ¥1,493.8b revenue and ¥141.9b earnings by 2029. This rests on 6.0% yearly revenue growth and an earnings increase of about ¥34.1b from ¥107.8b today.
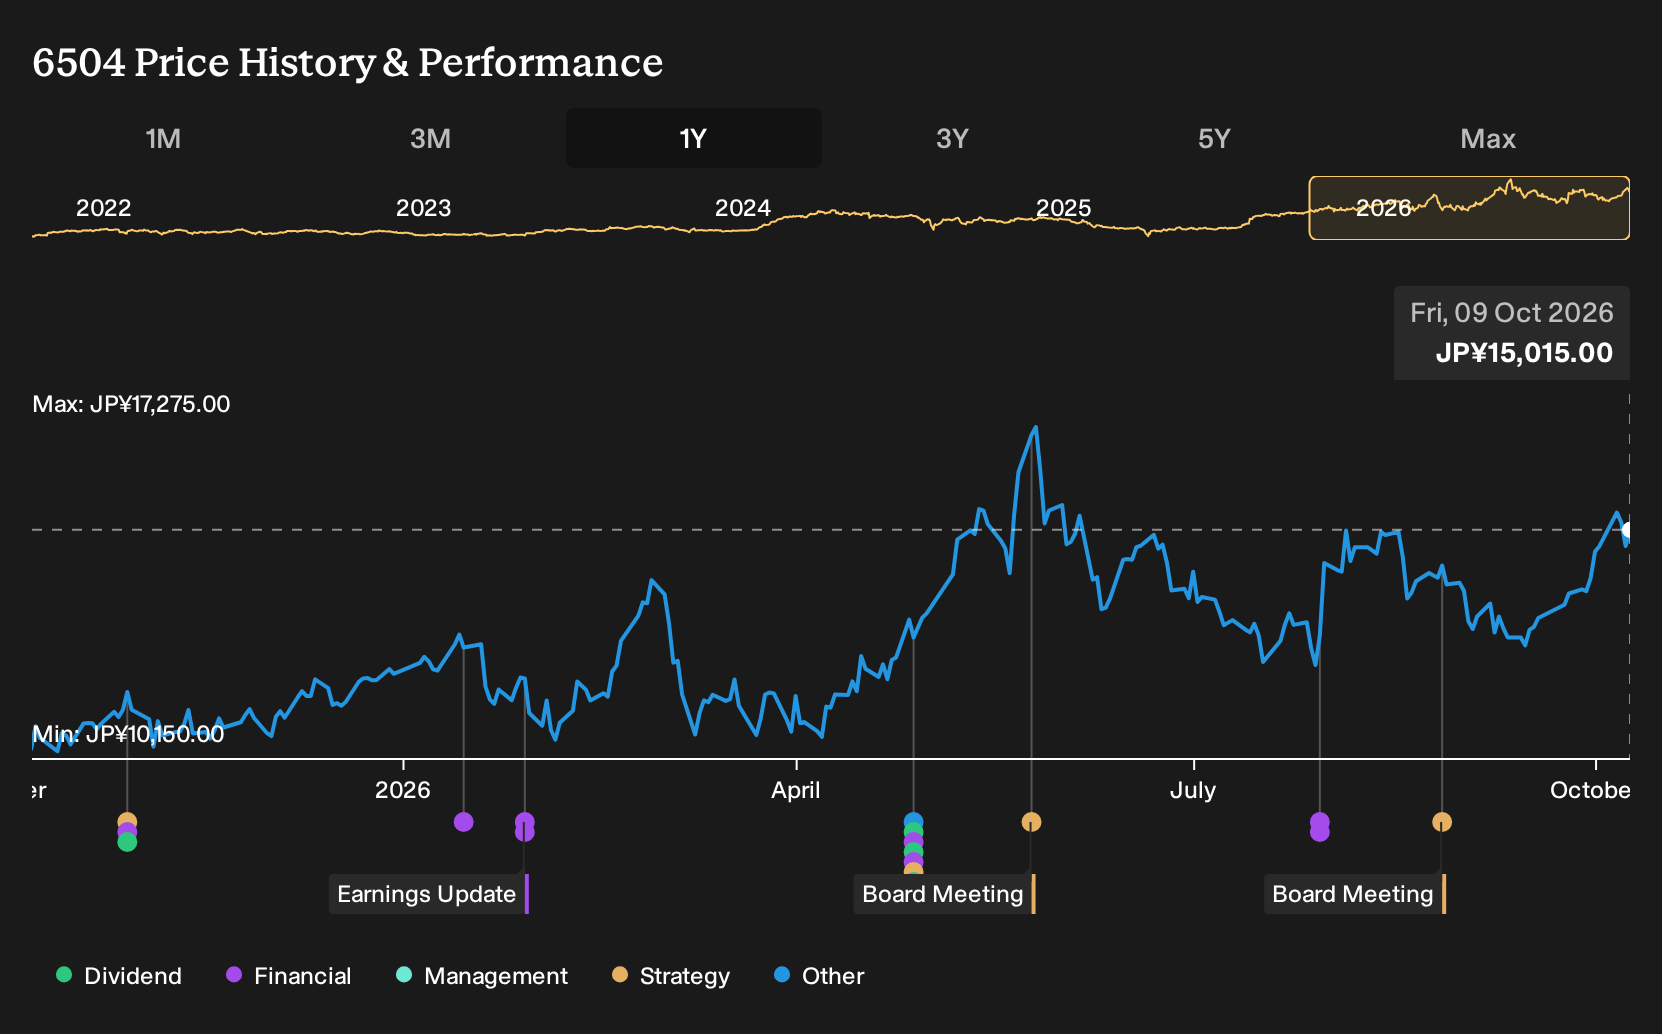
Uncover why Fuji Electric's fair value indicates a 10% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You have a very different story if you lean into the alternate risk that Fuji Electric stays too tied to legacy thermal power hardware while cleaner technologies move faster. The most cautious analysts were already working with revenue of ¥1,431.0b and earnings of ¥135.8b by 2029. Those figures came before this fusion partnership, so their narrative may shift as new information filters through.
Explore 2 other Fuji Electric fair value estimates, including one that suggests there may be as much as 18% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Fuji Electric research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Fuji Electric. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fuji Electric's overall financial health at a glance.
Looking For More Ideas Beyond Fuji Electric?
If the Fuji Electric story has you thinking bigger about where to put fresh capital to work, it can help to line it up against other businesses with different risk and income profiles. The Simply Wall St Screener lets you quickly filter for the kind of opportunities that match your own priorities, whether that is upside potential, stability, or reliable cash returns.
- If you want potential value with quality fundamentals and room for a re rating, sort through a curated set of opportunities using the 12 high quality undervalued stocks.
- If capital protection and balance sheet strength matter most to you, focus on companies that pass strict financial health filters via the list of solid balance sheet and fundamentals (23 results).
- If income is a priority and you prefer to be paid while you wait, scan for resilient payers with higher yields through the 28 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com