
Samsung Electronics (KOSE:A005930) Stock Trades Below Fair Value After A 312% Run
Samsung Electronics has logged very strong gains in recent years, and the question now is whether the current share price can still be explained by its earnings power. With the stock having moved sharply over multiple time frames, you need to ask if recent enthusiasm lines up with what the business is actually generating in profit.
- Over the past 5 years, Samsung Electronics has returned 311.7%, which puts a lot of weight on whether its earnings profile can keep backing that kind of share price performance.
- The group relies heavily on converting its technology and manufacturing scale into consistent profits, so any change in chip pricing, production efficiency or capital spending can reshape how much earnings investors are effectively paying for today.
- Your read on Samsung Electronics is one view; the desks covering it have another. See what analysts think Samsung Electronics's shares could be worth.
The stock's next move may depend on whether Samsung Electronics' current price still lines up with what its earnings suggest investors should be willing to pay.
To pressure test whether Samsung Electronics' past 5 year return of 311.7% is reasonable for the earnings profile you are seeing today, it can help to compare it with 173 high quality undervalued stocks.
Is Samsung Electronics a Bargain on Earnings?
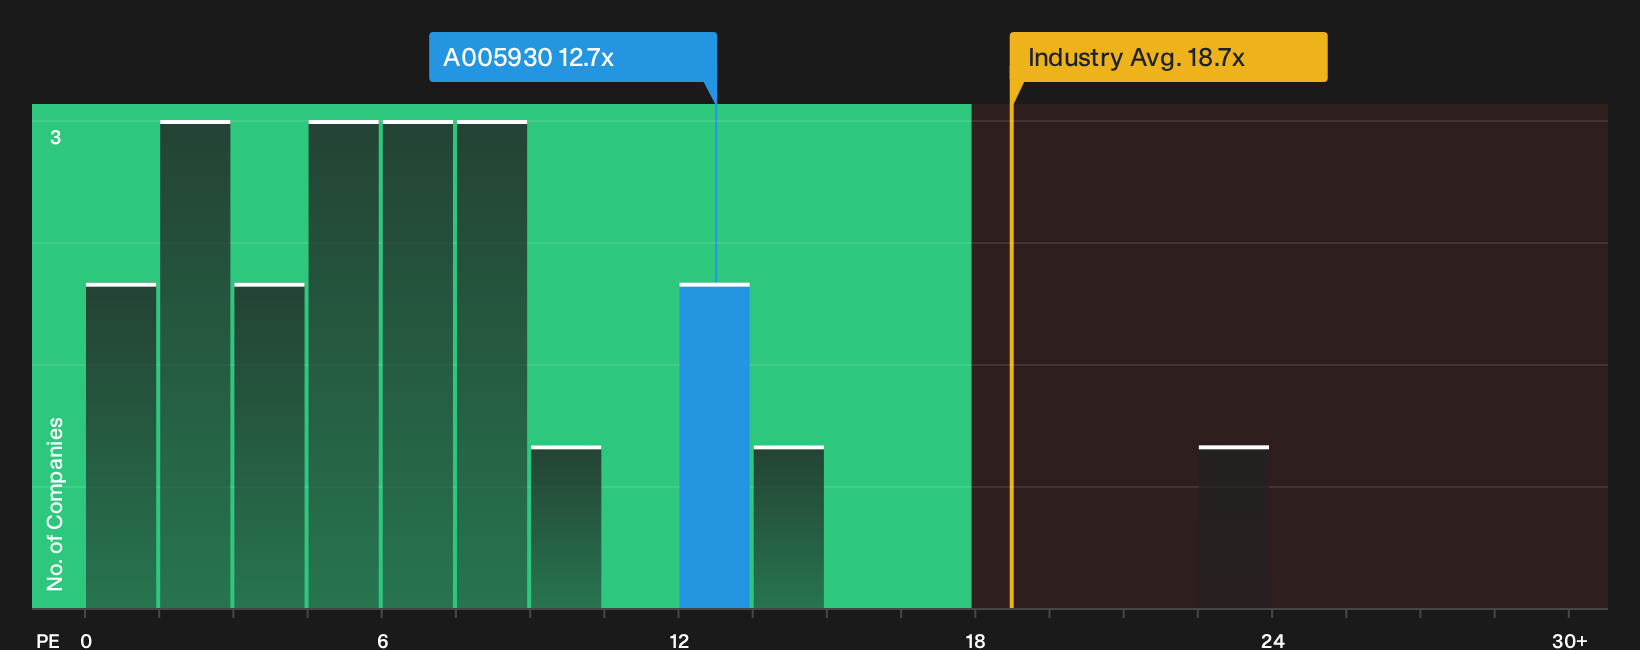
The P/E ratio is a useful fit for Samsung Electronics because earnings are a key anchor for how investors judge a mature, capital intensive tech group. On this metric, the stock trades on a P/E of 12.7x, compared with a Tech industry average of roughly 19.4x and a peer group that clusters much higher at about 61.1x. That is a wide gap between what the market is paying for Samsung Electronics profits and what it pays for many other chip and hardware players.
The fair value framework, which blends the company’s growth profile, margins, size and risk into a tailored benchmark, points to a higher P/E than the current 12.7x. That places the stock below the multiple implied by that model and suggests the market is pricing its earnings at a discount relative to those fundamentals. For you as a shareholder or potential buyer, the key question is whether the earnings quality and long term cash generation justify closing some of that gap in time. Explore the numbers behind Samsung Electronics's P/E valuation.
The Samsung Electronics Narrative: What Would Justify Today's Price?
Narratives on Samsung Electronics pick up where the valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to trade meaningfully above or below today’s price. Each scenario ties a fair value anchor to a specific mix of potential catalysts and risks in Samsung Electronics' story so you can track over time which version of events the business seems to be following on the Community page.
Community views on Samsung Electronics are split between those who see a discounted AI and memory champion and those who think the current price already reflects most of the good news.
Bull case: 48% undervalued
"Samsung's competitors like TSMC, SKHY, MU, and INTC are not capable of what Samsung can..."
Discover why this Narrative puts Samsung Electronics at 48% undervalued.
Bear case: 5% overvalued
"Since 1996 there have been six completed memory booms. All six died, each within roughly two years..."
Explore why this Narrative puts Samsung Electronics at 5% overvalued.
Samsung Electronics valuation leaves one crucial piece of the puzzle unresolved
Numbers only go so far if you do not know who is steering Samsung Electronics, how their incentives are set up, and whether those rewards truly line up with your interests as a shareholder. See who runs Samsung Electronics and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com