
What Man Group Holders Bought Into Before A 88% Run
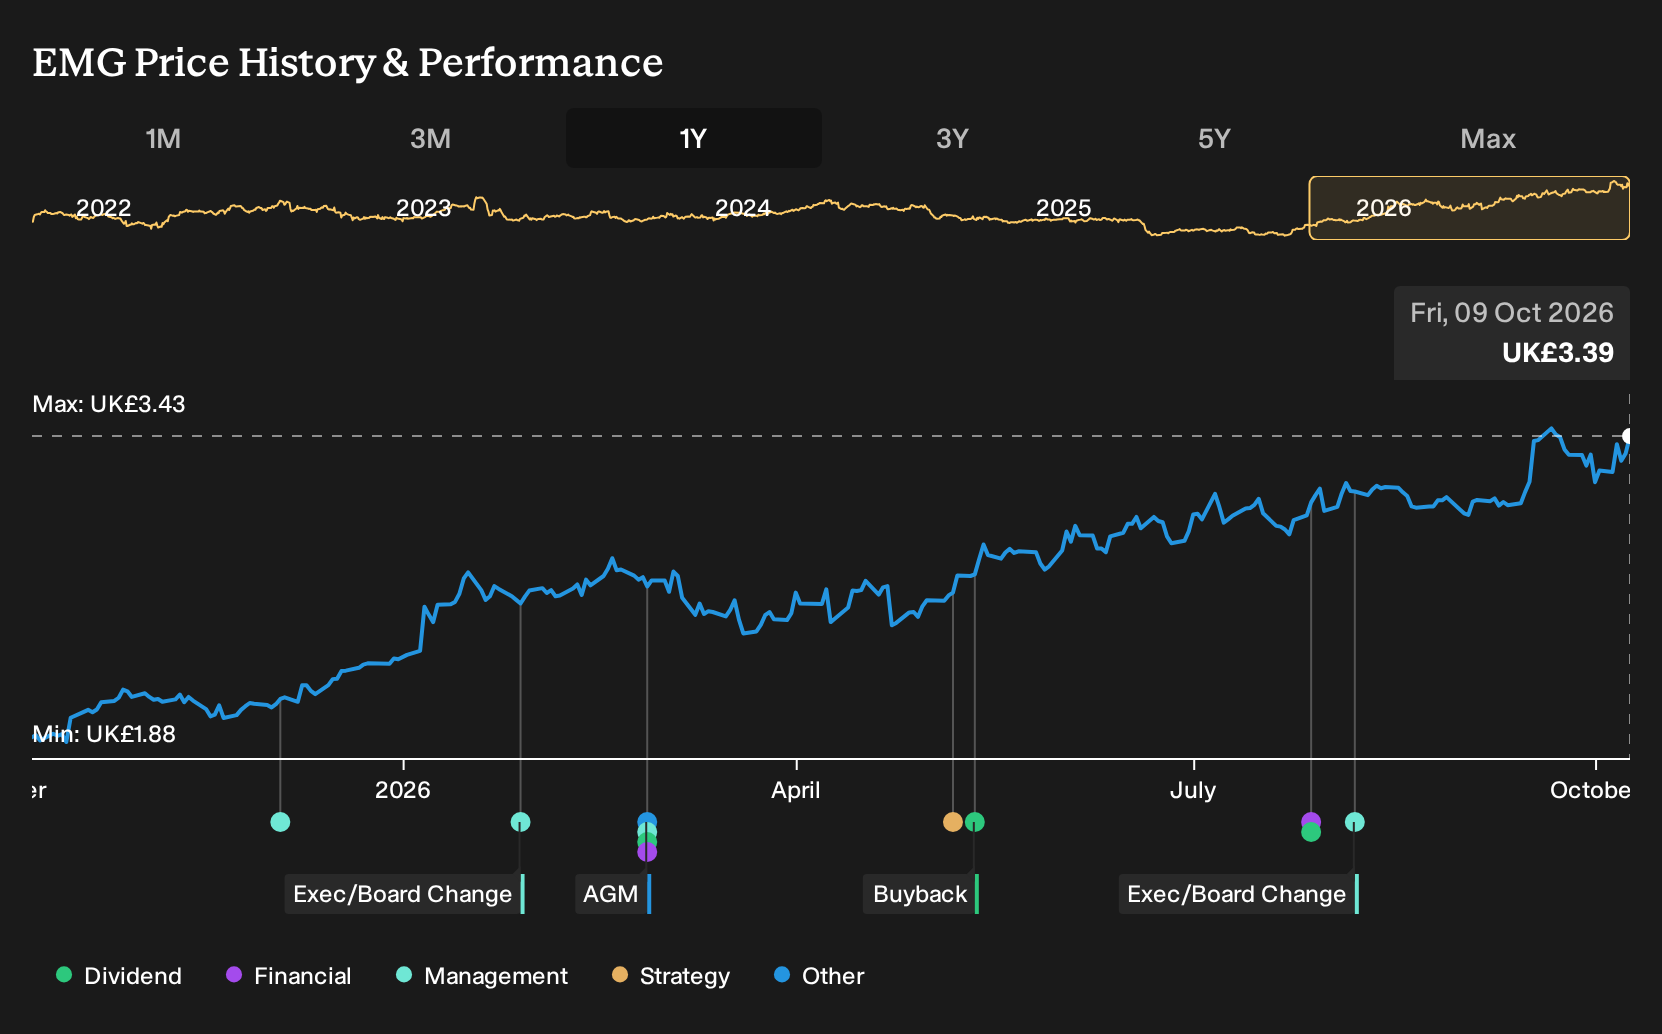
If you only glanced at Man Group headlines in 2025 and saw record inflows sitting beside fee pressure and underperforming trend followers, this outcome might surprise you. For Man Group shareholders, the return over the past year was 88.2%, including dividends. If you had been deciding on 9 October 2025, you were weighing bullish arguments about ESG and data analytics against worries over ETFs and fintech rivals. Which side of that debate really mattered for this result?
If the move has made Man Group harder to judge, start where the gap is still open and scan 6 high quality undervalued stocks.
The Two Man Group Stories Investors Were Choosing Between
The shares cost £1.91 at the start of the period, and Man Group investors were choosing between two very different stories about what that price already implied.
On the optimistic side, the ESG and data analytics Narrative pointed to a Fair Value of £2.13. This was essentially the price that scenario said the stock should reach if its assumptions played out, backed by strong institutional demand, record net inflows and heavy investment in quant platforms and generative AI.
The pessimistic view, focused on rising ETF use and fintech rivalry, put Fair Value at £1.59. It hinged on the risk that passive products, fee compression and underperforming trend followers would keep squeezing margins and earnings even if assets stayed high.
What The Results Changed For The Man Group Debate
The clearest new fact came from Man Group’s H1 2026 report. Total revenue was US$892m against US$604m in H1 2025, while net income excluding extra items moved from US$51m to US$201m and net margin shifted from 8.4% to 22.5%. That profit improvement lent more weight to the optimistic story that assumed scalable data analytics and efficiency could support higher margins, although it did not disprove the cautious case on future fee pressure.
The main lesson to apply elsewhere is simple. When a thesis depends on profitability improving through technology and mix, watch the reported net margin and absolute earnings rather than just assets or inflows, and test whether they move in the direction that story requires.
What Man Group’s Price Already Assumes
Man Group now trades at £3.39. The selected Narrative views its Fair Value as higher than that level, based on how record assets, a broader fee mix and heavy AI use might influence long term earnings power.
The real hinge is execution. A buyer today has to judge whether Man Group can keep converting its diversified platform and AI driven processes into fee income that does not dilute margins. That is the central business assumption.
"The main requirement is that Man Group continues to convert its broader product mix, growing credit and private markets platform and AI enabled operating model into sustained client demand and fee earning growth without eroding margins."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Where Man Group’s Rails Point Next
Watching Man Group, you are really watching how money moves. That raises a natural next question. Who helps move the payments themselves?
Every digital purchase needs a route between banks, merchants and account holders. One business quietly runs that connectivity and collects a fee each time.
It does not lend or carry credit risk. The focus is operating a global network and selling services around security, data and analytics.
The interesting part is how those extra tools matter as payments evolve. Could the need for secure, efficient transaction plumbing become even more important than the cards you see?
One Narrative has already put a figure on it. → Uncover the company trading 21% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com