
Discovery Mining (TSX:DSV) Shares Moved, What Is Behind The Attention?
Discovery Mining (TSX:DSV) is back in focus after fresh drill results at the Pamour Mine extended gold mineralization beyond the current open pit plan, while new permits at Cordero and a Timmins area asset deal reshaped its project pipeline.
Investors have been reacting to a flood of news around Discovery Mining, with the share price up 2.00% over the last day but down 6.47% over the past week and 5.64% over the past month, even as exploration results, Cordero permits and the Timmins acquisition reshape the portfolio. Despite that short term cooling, the 90 day share price return of 44.39% sits alongside a 39.07% year to date gain and a very large 1 year total shareholder return of 120.11%, with the 3 year total shareholder return above 15x. This indicates momentum that has built over several years rather than just on the latest set of drill hits.
Explore other precious metals opportunities that offer similar infrastructure and permitting catalysts by reviewing our curated list of 36 elite gold producer stocks
Discovery Mining has already delivered a huge multi year run on the back of Pamour, Cordero and Timmins newsflow. The question now is whether the current valuation still leaves enough upside for new buyers.
Most Popular Narrative: 83% Undervalued
According to the most followed narrative on Discovery Mining, the fair value sits far above the recent CA$11.71 close. This frames the recent pullback very differently for anyone focused on long term project delivery rather than short term price swings.
Discovery Silver Corp. is no longer just a silver development company. After acquiring the Porcupine Operations from Newmont in 2025, Discovery has transformed into a producing Canadian gold company with a major silver growth asset in Mexico. The company now combines operating gold production in Timmins, Ontario with 100 percent ownership of the Cordero project in Chihuahua, Mexico, one of the world’s largest undeveloped silver deposits. Discovery describes itself as an Americas-focused precious metals company with producing gold assets in Canada and a large silver development-stage project in Mexico.
See why 68 investors see Discovery Mining as 83% undervalued.
The narrative from RTRockeTeller assigns Discovery Mining a fair value of CA$70.00, using a discount rate of 6.65%. That implies an 83.3% discount to this reference point at the current CA$11.71 share price, even after a 120.11% total return over the past year and a 3 year total shareholder return above 15x.
This view leans heavily on the combination of current Porcupine cash generation, the Cordero feasibility study, and the potential contribution from the Kidd acquisition. It also factors in that Discovery Mining has recently become profitable, reports revenue of CA$1.12b and net income of CA$241.56m, and has a high Return on Equity of 33.1% with revenue and earnings growth forecasts of 13.5% and 11.7% per year respectively.
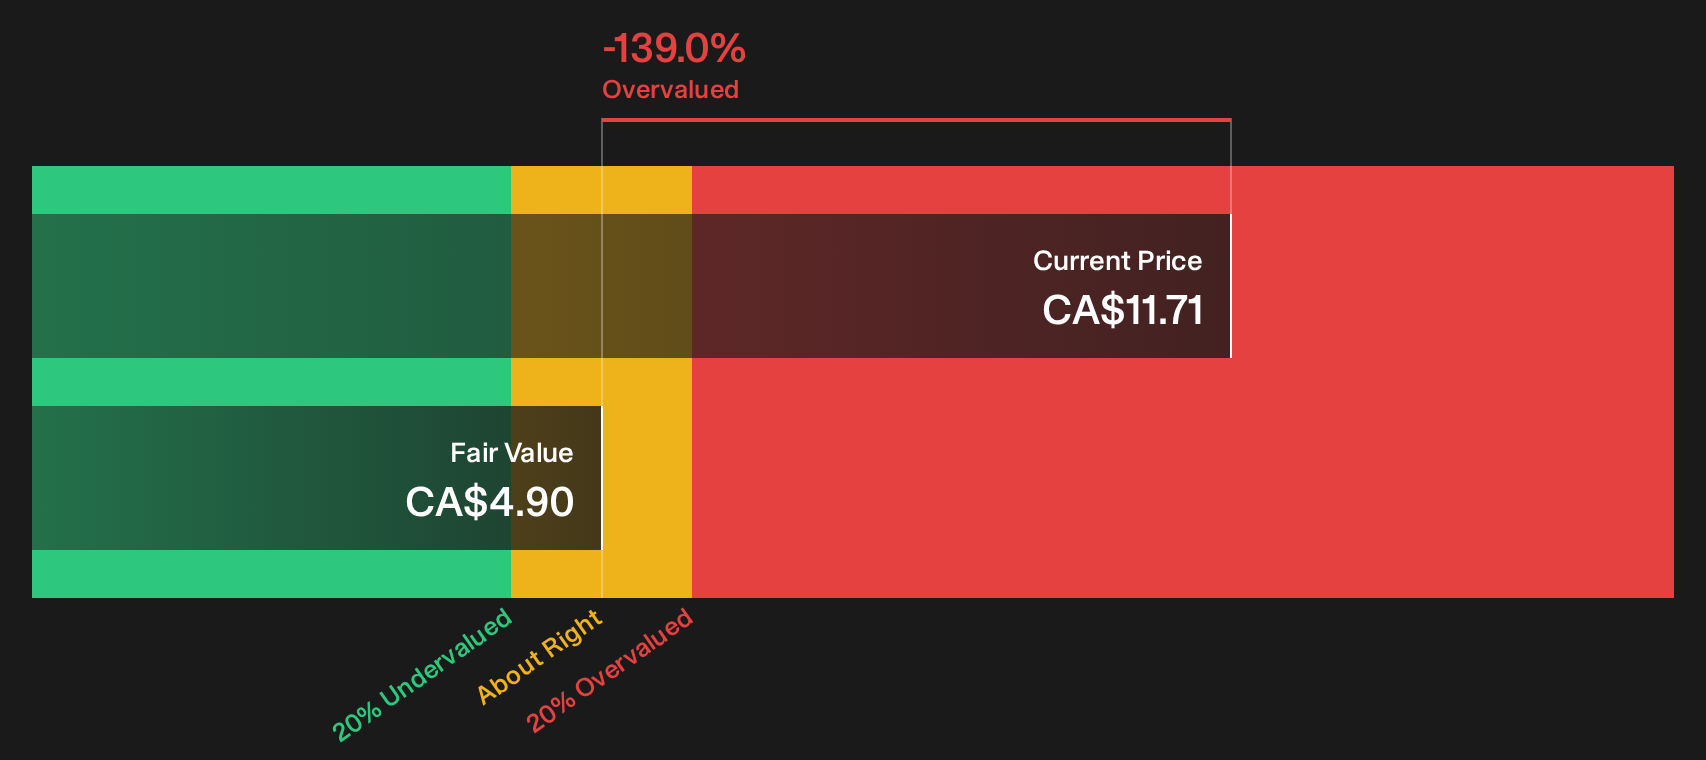
At the same time, there are clear tension points inside that fair value story. The SWS DCF model points to a future cash flow value closer to CA$4.90 per share, analysts collectively see about 29.2% upside to a CA$15.13 price target, and the stock trades on a P/E of 27.7x, which is higher than both the Canadian metals and mining industry average of 15.6x and an estimated fair P/E of 17.7x. Those markers suggest the market is already paying up for profitability, 33.1% current and 24% forecast Return on Equity, and faster than market revenue growth, even as the narrative fair value sits far above all three.
For readers trying to reconcile those gaps, the key is that the most popular narrative leans into long dated optionality at Cordero and the potential to compound Porcupine output and Kidd infrastructure. The DCF output and P/E based comparatives reflect more conservative assumptions around future free cash flow and peer pricing. How that tension resolves over time will likely depend on whether Discovery Mining can convert its large resource base into sustained, high quality earnings without heavy dilution or persistent cost pressure.
Result: Fair Value of CA$70.00 (UNDERVALUED)
Still, the narrative around Discovery Mining could crack if Porcupine costs stay elevated, or if Cordero’s large capex and Mexico risk start to outweigh the upside story.
Find out about the key risks to this Discovery Mining narrative.
Another View: What The SWS DCF Model Says About Discovery Mining
The popular CA$70.00 fair value on Discovery Mining leans on long dated project potential. The SWS DCF model tells a very different story. On those cash flow assumptions the estimated value sits around CA$4.90 per share, which frames the current CA$11.71 price as expensive rather than cheap.
Our DCF output leans on more restrained cash generation and treats a lot of the Porcupine, Cordero and Kidd upside as unproven. For readers, the gap between CA$4.90 and CA$70.00 is really a question: How much of Discovery Mining’s future are you comfortable paying for today based on cash flows rather than narratives?
To see exactly how those cash flows are modeled, and where the pressure points sit, it is worth stepping through the SWS DCF approach in full Look into how the SWS DCF model arrives at its fair value..
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Discovery Mining for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 9 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted about whether Discovery Mining still suits your risk tolerance after all this data? Move quickly, review the underlying numbers, and weigh both the downside flags and upside potential by starting with 3 key rewards and 2 important warning signs.
Looking for more Discovery Mining style ideas?
If Discovery Mining has sharpened your focus on opportunities, do not stop here. Use the Simply Wall Street Screener to hunt for fresh, data driven ideas before others spot them.
- Target potential upside by reviewing a curated set of companies that combine quality fundamentals with attractive pricing through the 9 high quality undervalued stocks.
- Strengthen your income stream by zeroing in on businesses offering higher yields and resilient payouts via the 3 dividend fortresses.
- Dial back portfolio risk by concentrating on financially robust candidates in the 7 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com