
3 British Founder Led Stocks With Earnings Growth Over 13%
Rising government borrowing costs across Europe are putting pressure on listed businesses, especially those reliant on cheap debt and short term sentiment. Founder led British companies with high insider ownership and solid balance sheets can offer a different anchor. Leaders with real skin in the game often take a long view on capital allocation. This article highlights three such stocks from our high conviction founder universe.
The three founder led British businesses covered below are just a sample, with the full screen surfacing 5 more companies with similar alignment between insiders and outside shareholders that are not discussed here.
If you want to identify and analyze the wider opportunity set built around this theme, go straight to the Top Founder-Led Companies screener.
Fevertree Drinks (AIM:FEVR)
Fevertree Drinks develops and sells premium mixer and soft drinks under the Fever Tree brand, with founders retaining meaningful influence that fits a legacy focused, founder led theme. The business has a market value of about £966 million.
For investors interested in founder led consumer brands, Fevertree Drinks offers a useful test case for how long term owner operators handle category change and shifting tastes at scale.
"Although Fevertree Drinks is broadening its range beyond tonic and reports that the wider portfolio now represents nearly half of group sales, a further shift in consumer taste away from mixers could leave the company with high exposure to flavours that fail to scale."
The real tension for Fevertree Drinks now sits in how one quiet cost pressure interacts with that product mix shift to shape future profitability.
That quiet cost squeeze is exactly why reading the full narrative for Fevertree Drinks can help you see whether Fevertree Drinks has an underappreciated upside or just rising strain.

Computacenter (LSE:CCC)
Computacenter is a £5.82b technology services group that runs long-term IT outsourcing and managed services contracts for corporate and public clients, a direct fit for investors who want founder style stewardship anchored in multi year commitments. Its £12.05b Computer Services arm is the single revenue engine and gives scale to that contract driven model.
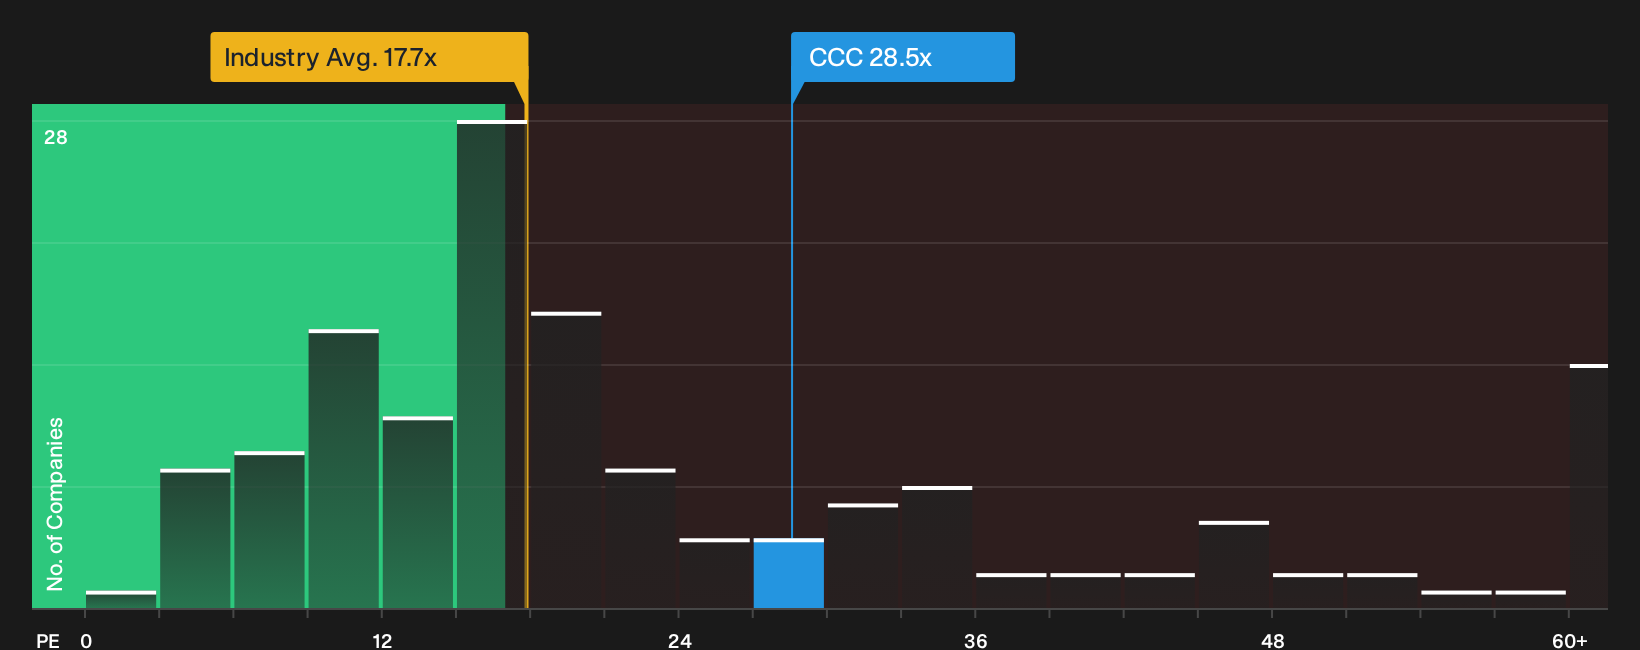
For anyone drawn to founder led discipline, Computacenter’s appeal is the combination of multi year managed services, a P/E of 28.5 and a 21.1% ROE that leans on recurring customer relationships rather than one off projects. The real test for this stewardship model comes if a change in funding pressure affects how those contracts translate into future margins.
Those margin questions are exactly why the analysis report for Computacenter can help you see whether Computacenter’s current valuation is masking pressure or setting up the next leg of growth.
Foresight Group Holdings (LSE:FSG)
Foresight Group Holdings runs a £491 million asset manager that blends renewable infrastructure with private equity and venture capital, with the most direct tie to this founder-led screener coming from its growth capital and buyout backing of owner-managed businesses.
Real Assets bring in about £115 million, while the Private Equity arm contributes roughly £50 million, so the founder and manager focused investment activities are important but not the only income stream.
Foresight Group Holdings matters for this founder-led screen because it is not just investing in infrastructure, it also channels capital into owner and manager run businesses where equity stakes are meant to keep everyone thinking in decades, not quarters.
"While consensus anticipates margin expansion from operational efficiencies and higher-margin platforms, management's explicit guidance to overshoot fundraising targets (already running 30-40% ahead in Q1 versus last year) and accelerate the business mix into higher-fee, scalable retail and institutional products signals faster-than-forecast margin recovery and EBITDA/EPS outperformance by 2029."
What really matters now is how one shift in where new capital is raised ends up feeding through to fee growth and shareholder returns.
That capital shift is exactly why reading the full narrative for Foresight Group Holdings can show how Foresight Group Holdings could turn fee mix changes into accelerating long term compounding potential.

Seeking Alternatives Before The Crowd?
Fresh ideas do not stay under the radar for long. Once momentum builds, the best setups can be gone before you react. Scan these themes and act now.
- Spot early movers in hard assets by reviewing the 36 elite gold producer stocks before momentum sends quality producers outside your preferred price range.
- Track the next wave of intelligent automation and use the 91 robotics and automation stocks while adoption trends are building, not after the market has fully caught on.
- Consider potential power bottlenecks by assessing the 43 power grid technology and infrastructure stocks while the grid upgrade story is still developing and valuations have not fully rerated.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com