
3 UK Audit And Compliance Stocks In Focus After The Manchester City Case
Heightened scrutiny of BDO over Manchester City’s alleged £900mn accounting misstatements has dragged the audit and compliance sector into the spotlight, turning routine financial plumbing into front-page risk. That disruption can reshape fees, client mandates and trust in listed professional services groups. This article walks through three UK focused audit and compliance stocks exposed to the Manchester City saga and explains how the same headlines could help or hurt your portfolio.
The three stocks in this piece are just a starting sample, since the wider screen surfaced 11 more audit and compliance groups with equally compelling narratives that are not covered here. To identify and analyze the highest conviction ideas in this corner of the market, head straight to the UK-listed and large-cap global audit & compliance service providers screener.
Mha (AIM:MHA)
Overview: Mha Plc is a UK based professional services group providing audit, accountancy, tax, corporate finance and wider business advisory support.
Operations: Mha generates £251 million from professional services, primarily in the United Kingdom at about £225 million, with smaller contributions from Ireland, mainland Europe and the Cayman Islands.
Market Cap: £343 million
Mha provides exposure to UK focused audit, tax and compliance style work at a P/E below both domestic professional services peers and the broader industry. Revenue grew to £251.36 million while dividend payments continue, even as earnings have come under pressure. Interest hinges on how one unresolved pressure on profitability shapes future confidence in those compliance led services.
That pressure point makes the valuation debate sharper, so it is worth lining up the DCF valuation analysis for Mha against those earnings trends and compliance tailwinds.
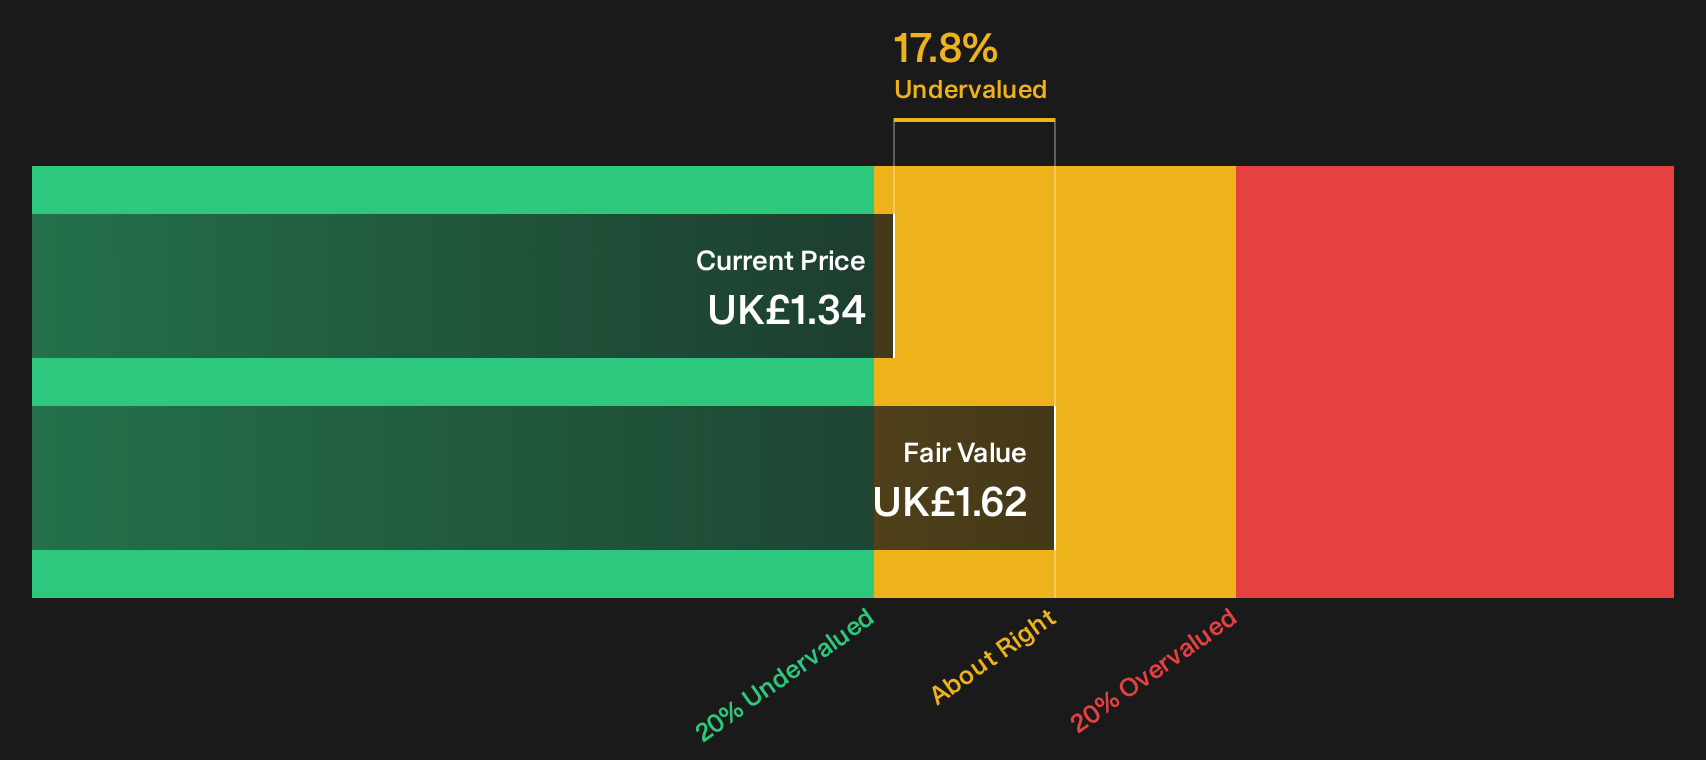
BTG Consulting (AIM:BTG)
Overview: BTG Consulting is a UK headquartered advisory group focused on restructuring, real estate and governance related financial consulting for distressed and complex situations.
Operations: BTG Consulting generates £116.8 million from Restructuring and Advisory and £51.7 million from Real Estate services, all from UK based clients.
Market Cap: £181 million
BTG Consulting provides pure UK exposure to restructuring, insolvency and real estate advisory work that is influenced by tighter reporting and governance rules. Earnings growth has been strong and the dividend yield is meaningful. However, one unresolved question is how rigorously clients will adopt more intensive advisory support, which could affect whether margins and fee rates fully reflect that regulatory backdrop.
That adoption question sits at the heart of the 5 key rewards and 1 important warning sign, where fee resilience, client behaviour and any early warning signs begin to distinguish BTG Consulting from the pack.

Christie Group (AIM:CTG)
Overview: Christie Group provides valuation, brokerage, consultancy and compliance style services to regulated sectors such as healthcare, childcare and hospitality.
Operations: Christie Group generates about £61 million from Professional & Financial Services and £11 million from Stock & Inventory Systems & Services.
Market Cap: £45.6 million
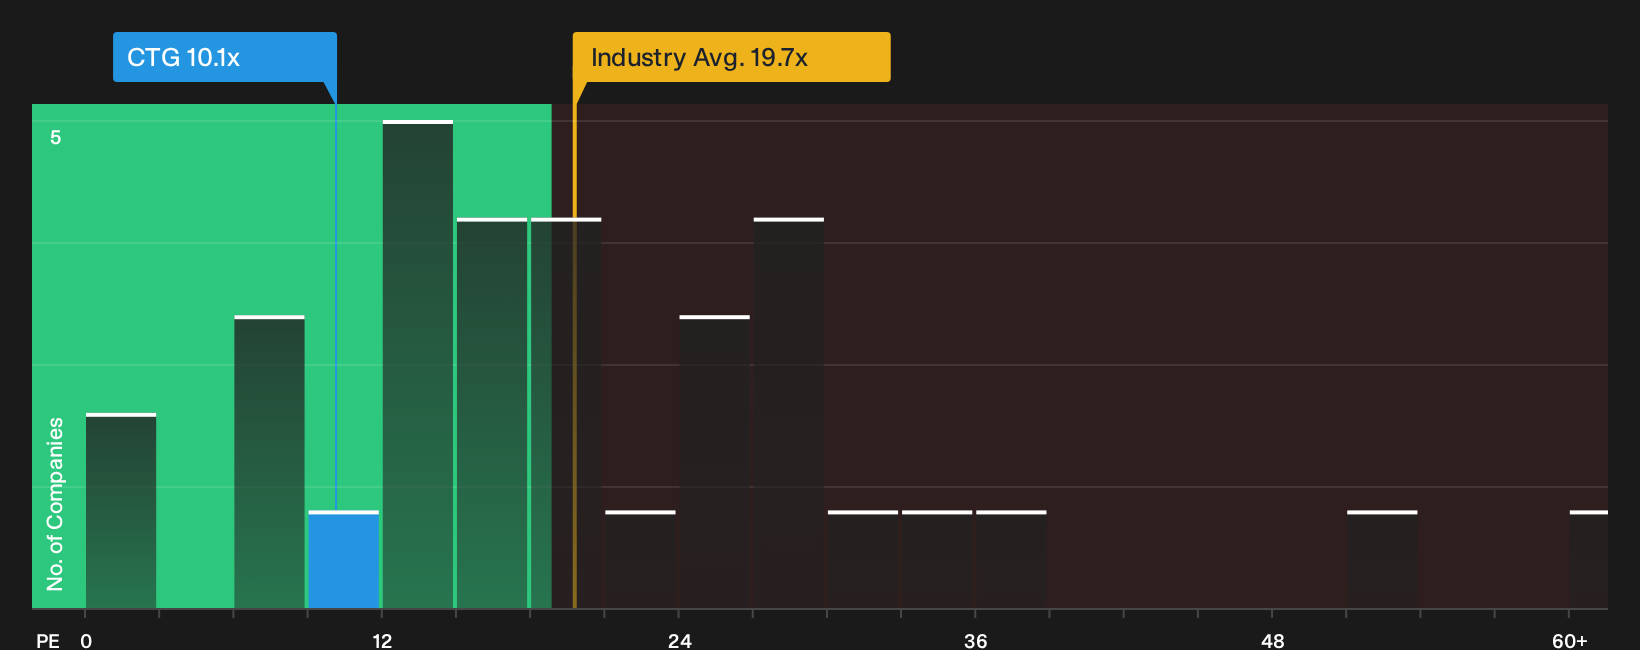
Christie Group taps the same regulatory scrutiny trend as core audit firms by focusing on valuations, transactions and compliance-linked services in tightly regulated sectors like healthcare and childcare. The stock trades on a P/E of 10.1x compared with an industry level closer to 19.7x. The company reports strong ROE and forecast revenue growth, while investors still need to judge what happens if a single key assumption about future profitability pressure shifts.
If that profitability assumption is the hinge, the analysis report for Christie Group shows where Christie Group’s valuation could be masking either resilience or pressure.
Seeking Alternatives Before The Crowd
Fresh ideas move first. Breakout stories gain momentum, laggards keep dropping and quiet compounders get caught once the crowd arrives. Scan these under the radar lists while it matters and consider them before they are widely followed.
- Spot cash generative businesses that keep their balance sheets tight and cushions in place by running the list of solid balance sheet and fundamentals (9 results).
- Hunt for early stage opportunities that already show earnings strength and disciplined finances with the curated 11 elite penny stocks with strong financials.
- Zero in on companies riding structural demand in atomic energy infrastructure through the focused 16 nuclear energy infrastructure stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com