
AI Data Center Cooling Might Change The Case For Investing In Trane Technologies (TT)
- Trane Technologies recently announced a quarterly dividend of $1.05 per share, payable on December 31, 2026, and rolled out cold climate residential heat pumps, advanced data center cooling solutions, and a multi-year HVAC partnership with Kroenke Sports & Entertainment.
- This cluster of product launches and the KSE partnership indicates that Trane Technologies is focusing on energy-efficient HVAC and AI data center cooling as long-term demand themes, rather than isolated projects.
- We will examine how Trane Technologies' investment narrative is influenced by the AI-focused thermal management launches and its broader sustainability initiatives.
Trane Technologies Investment Narrative Recap
To own Trane Technologies, you need to believe the business can turn its record US$12.1b backlog, expanding services and AI focused cooling capacity into durable earnings while holding margins together. The fresh US$1.05 quarterly dividend signals confidence in cash generation, but in the near term the real swing factor is still execution on Commercial HVAC projects, especially in the Americas.
The biggest near risk remains any slowdown or deferral in large non residential and data center builds that underpin that backlog, along with ongoing pressure from price versus inflation and regional mix. The recent announcements do not remove those issues, although they support the view that Trane Technologies is actively building around long term efficiency themes.
The 800 volt direct current cooling architecture announcement is the clearest operational link to the current AI data center narrative around Trane Technologies. Management has shown that an 800 VDC fed chiller can cut power conversion losses and deliver over 1,000 tons of cooling capacity, which directly addresses power and thermal constraints at very large sites.
For you as a shareholder, that proof of concept matters because capacity additions for AI and data centers are a key catalyst in the current thesis. The success of DC based plants could help the firm convert more of its applied systems capacity and LiquidStack and Stellar Energy capabilities into booked projects, although the same concentration increases exposure if large AI deployments are delayed.
Trane Technologies' current analyst story points to revenues of US$29.5b and earnings of US$4.7b by 2029, based on a 10.0% yearly revenue growth rate and an increase in earnings of US$1.7b from US$3.0b today.
Uncover how Trane Technologies' fair value indicates a 10% potential upside to its current price, which could narrow quickly if sentiment shifts in Trane Technologies' favor.
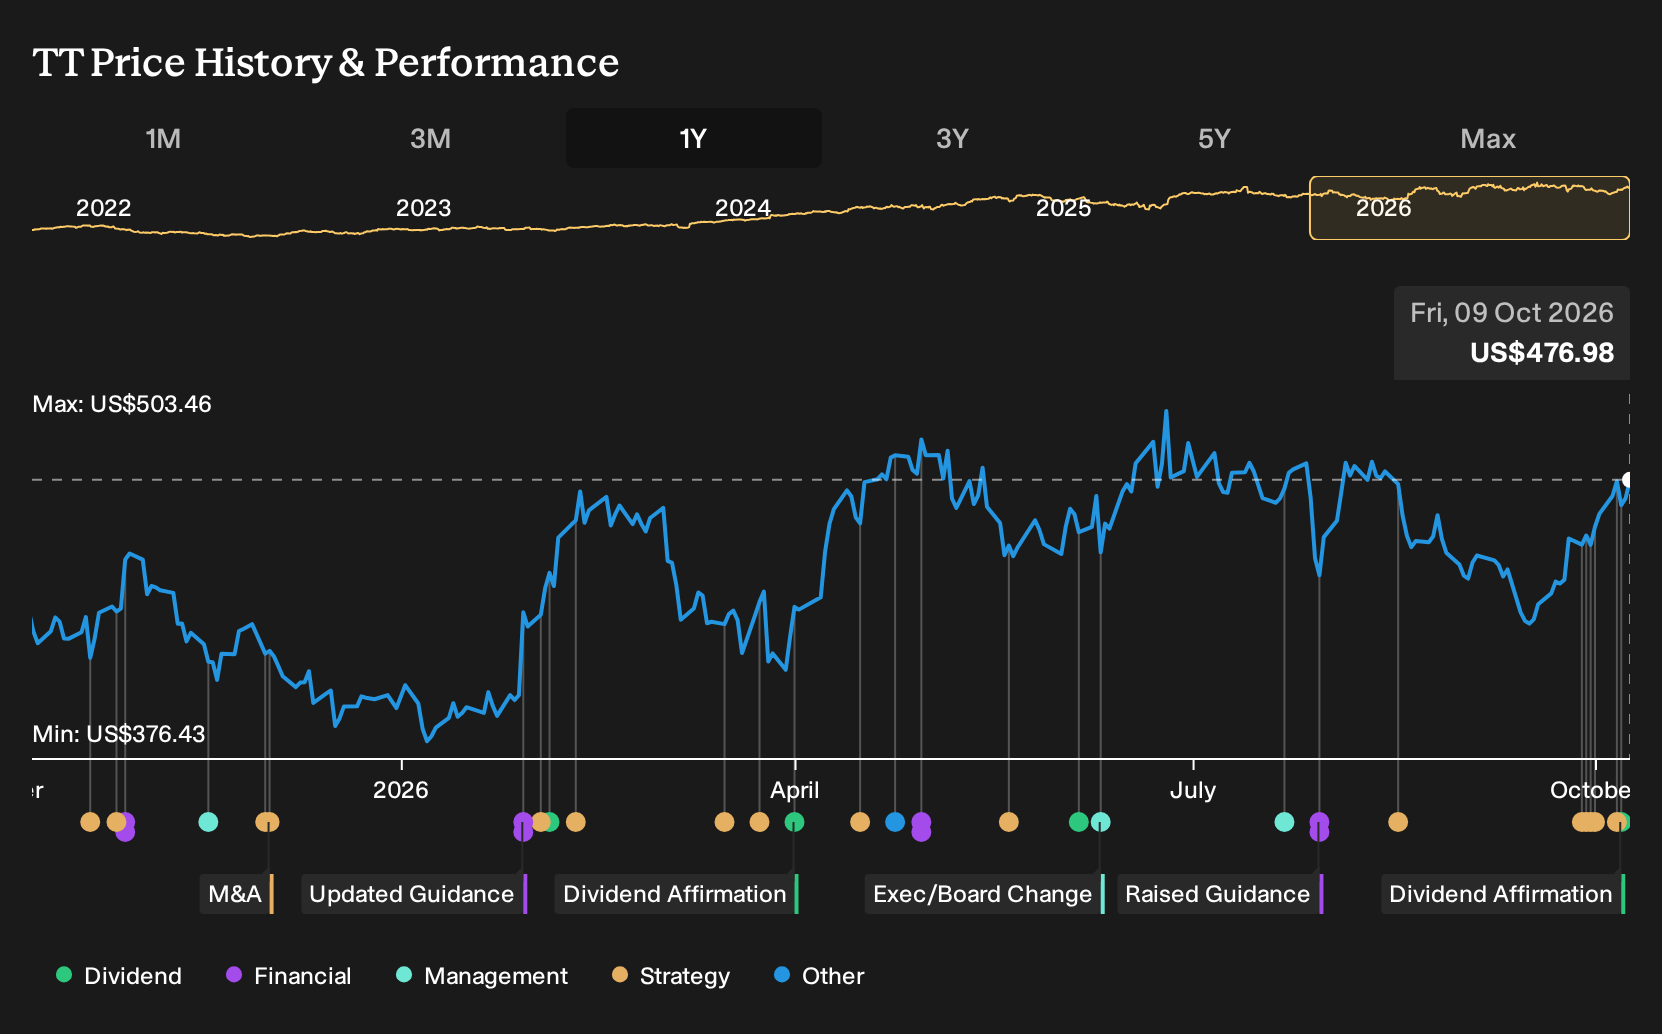
Exploring Other Perspectives
One alternate view puts the AI data center buildout itself at the center of the risk. In that storyline, Trane Technologies faces a scenario where hyperscaler spending cools and the heavy cooling buildout leaves underused capacity. The most cautious analysts were penciling in about US$28.6b of revenue and US$4.6b of earnings by 2029, before this dividend and KSE news. This shows how sharply opinions can differ. Use those more pessimistic estimates as a reference point and explore how both narratives might shift as these new announcements get fully reflected in models.
Explore 4 other Trane Technologies fair value estimates, including one that suggests there could be as much as 20% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Trane Technologies research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Trane Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Trane Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Trane Technologies?
If you want to stress test your Trane Technologies thesis, it helps to line it up against other companies with very different profiles. The Simply Wall St Screener can surface stocks with stronger income potential, cleaner balance sheets, or more misunderstood stories, depending on what you want to focus on next.
- If income reliability matters to you, scan for established payers with consistent distributions using our list of 8 dividend fortresses.
- If capital preservation comes first, filter for businesses with steadier fundamentals and fewer red flags by reviewing a 31 resilient stocks with low risk scores that might complement a position in Trane Technologies.
- If you are hunting for mispriced stories, compare Trane Technologies with a 20 high quality undiscovered gems that have solid fundamentals but limited market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com