
Compass (COMP) Faces A Fresh Lawsuit As Undervalued Narrative Gets Tested
Compass (COMP) is back under the legal microscope after a new securities class action tied to its January merger with Anywhere Real Estate, placing regulatory conduct, disclosure practices, and antitrust scrutiny in sharp focus for shareholders.
At a share price of US$9.39, Compass has seen the 30 day share price return fall 10.66% and the 90 day share price return decline 18.35%. At the same time, legal headlines around the Anywhere merger and the CRMLS dispute keep risk perceptions in focus.
Spot fresh real estate opportunities by comparing Compass against a hand picked group of list of solid balance sheet and fundamentals (25 results).The drop in Compass to US$9.39 sits at the crossroads of lawsuit driven anxiety and views on the real estate platform’s long term earning power. How much of that move reflects sentiment rather than fundamentals?
Most Popular Narrative: 39.1% Undervalued
On the most followed narrative, Compass screens as undervalued, with a fair value estimate of $15.42 against the recent $9.39 close. This puts the Anywhere merger, luxury exposure and execution track record under a brighter spotlight.
Rapid adoption and continuous improvement of Compass's AI-powered, end-to-end technology platform is increasing agent productivity, driving higher transaction volumes, improving retention, and is expected to widen margins as AI-driven process efficiencies scale throughout the organization, positively impacting revenue, EBITDA, and net margins.
See why 16 investors see Compass as 39% undervalued.
The Simply Wall St narrative applies a 9.51% discount rate to those long range cash flows, which feeds into a fair value of $15.42 per share. Against Compass at $9.39, that implies a wide gap that investors need to reconcile with the firm’s P/E of 105.4x, recent profitability and the impact of one off items on reported earnings.
That story leans heavily on Compass using its end to end software, title and escrow offering, and Christie’s International Real Estate platform to lift earnings from $67.5m on $10.56b of revenue. It also assumes benefits from the Anywhere Real Estate tie up and luxury housing exposure are durable enough to matter over a multi year horizon, despite legal and regulatory noise around commission structures.
Result: Fair Value of $15.42 (UNDERVALUED)
Still, the Compass story can change quickly if commission focused litigation reshapes broker economics, or if heavy reliance on housing transactions exposes earnings to weaker deal volumes.
Find out about the key risks to this Compass narrative.
Another View: Compass Through The Earnings Lens
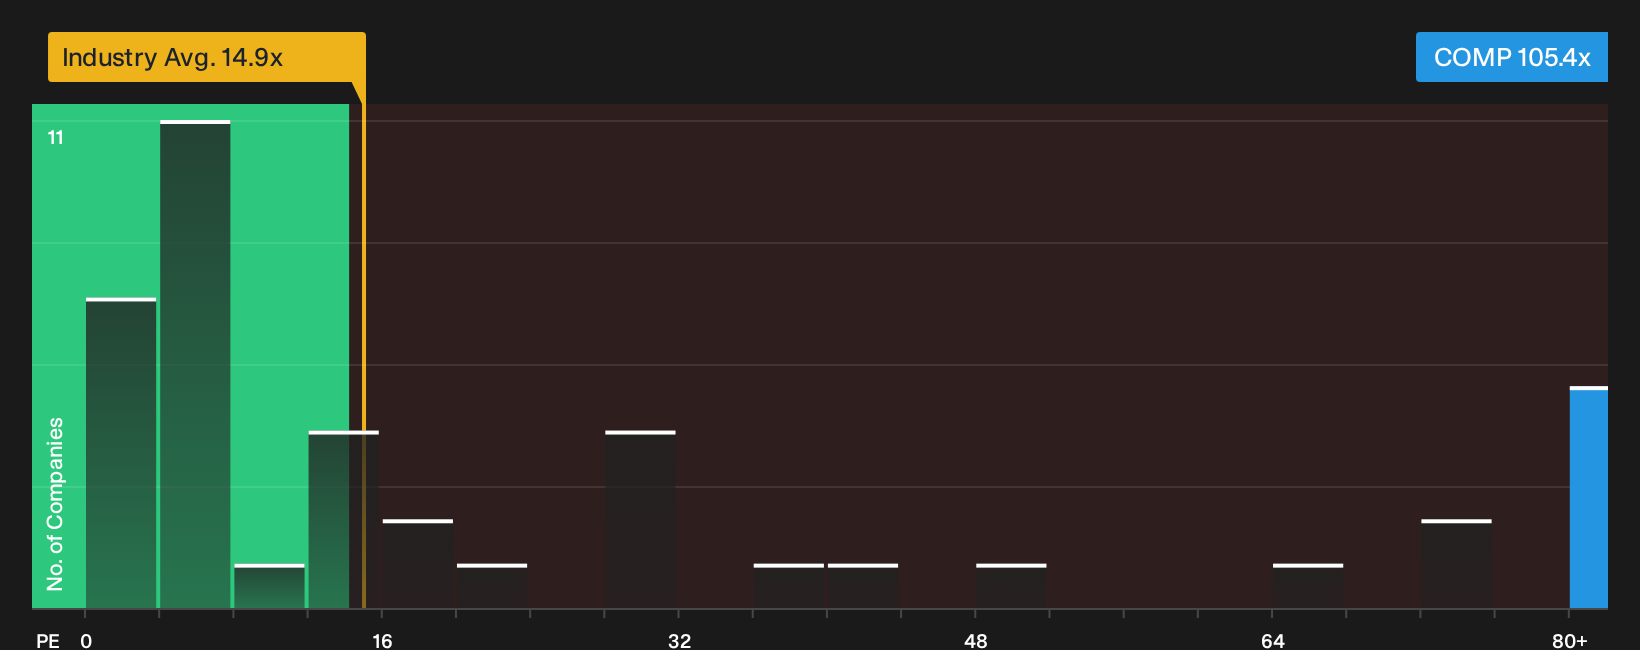
On price multiples, Compass tells a very different story. The stock trades on a P/E of 105.4x, compared with 78.3x for peers and 14.9x for the wider US Real Estate industry. Against a fair ratio of 45x, that is a steep premium. Is this a margin of safety or a valuation tightrope?
For a closer look at how that premium lines up with earnings power and sector norms, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted on Compass after all of this. Act quickly, review the data on both the legal overhang and earnings potential, then weigh the 4 key rewards and 3 important warning signs.
Looking For More Investment Ideas Beyond Compass?
If Compass leaves you on the fence, do not stop there. Use this moment to widen your watchlist and pressure test your thesis against fresh opportunities.
- Target cash rich balance sheets and steadier business models by scanning the list of solid balance sheet and fundamentals (25 results).
- Hunt for pricing gaps where quality and valuation still line up using the 20 high quality undiscovered gems.
- Lean into resilience by focusing on companies with lower risk profiles through the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com