
Mowi (OB:MOWI) Expands Salmon Capacity As Valuation Questions Linger
Mowi (OB:MOWI) has committed £6 million to a semi closed post smolt trial in Scotland, while also increasing harvest capacity organically and through the pending Nova Sea acquisition.
Mowi’s recent operational moves come after a mixed price pattern, with a 90 day share price return of 8.81%, a year to date share price decline of 16.54%, and a 1 year total shareholder return that is down 4.42%.
Scan for other seafood and protein producers that could be setting up for similar volume driven stories in our curated list of 618 high quality undiscovered gems.
Mowi’s recent share price move can be read as either a reset in sentiment or a catch up to what the operations already signal. The valuation work now needs to show which story fits better.
Price-to-Earnings of 15.8x: Is it justified for Mowi?
Mowi trades on a P/E of 15.8x, with the NOK203.80 share price sitting close to Food industry levels but well below peer averages.
The P/E ratio compares the current share price to earnings per share. For a salmon producer like Mowi, it reflects how much investors pay for each unit of profit in a sector where volumes, biological risks, and regulation all matter to earnings quality.
Mowi is assessed as good value on several fronts while carrying a P/E that screens as slightly expensive versus the European Food industry average of 15.6x. The same 15.8x multiple is described as attractive against an estimated fair P/E of 17.9x and particularly against a peer average of 26.2x, which points to scope for the market to move closer to that higher fair level if earnings quality and growth forecasts hold.
Mowi’s valuation also benefits from the SWS DCF work, which places the future cash flow value at NOK580.32 per share compared to the current NOK203.80 price. That wide gap signals a very large implied discount on the cash flow side, reinforcing the idea that the present P/E may understate what the business could justify if forecasts materialise.
Explore the SWS fair ratio for Mowi.
Result: Price-to-Earnings of 15.8x (UNDERVALUED)
Still, the picture can flip if biological issues, regulatory changes or weaker salmon pricing put pressure on Mowi’s earnings and keep that apparent discount in place.
Find out about the key risks to this Mowi narrative.
Another View on Mowi’s value
The P/E work suggests Mowi looks modestly cheap, yet the SWS DCF model points to something far more extreme. The cash flow estimate of NOK580.32 per share versus the NOK203.80 price implies a very large valuation gap that could just as easily reflect upside potential or deep scepticism about future cash generation.
For anyone weighing which signal to pay more attention to, the question is simple. Is the market correctly discounting risk, or is it mispricing a salmon producer with improving earnings quality and forecast growth?
Look into how the SWS DCF model arrives at its fair value.
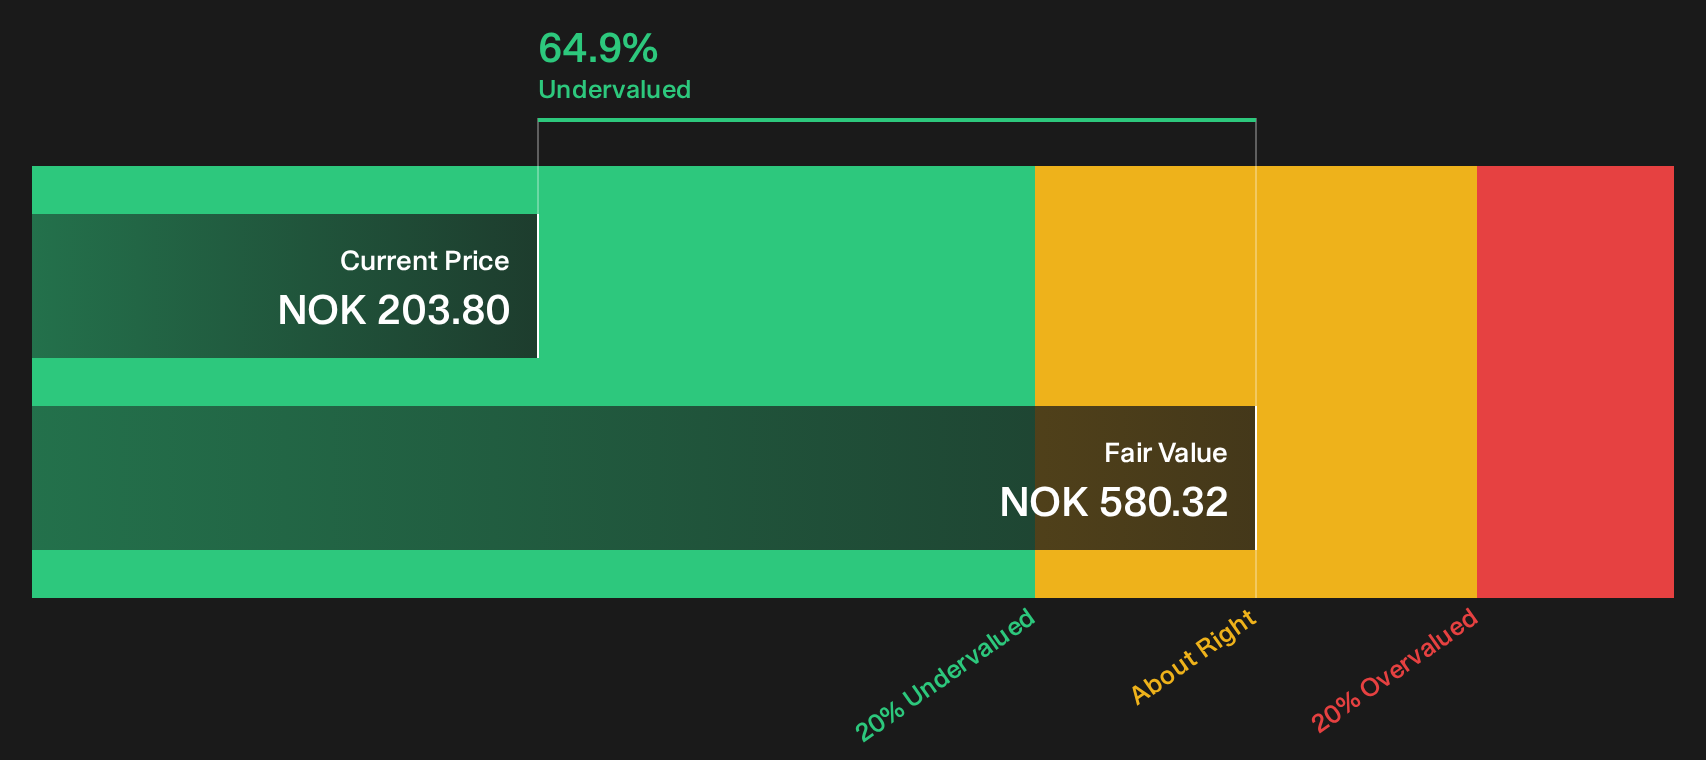
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mowi for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 178 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of discount signals and salmon sector risk feels finely balanced, move quickly to check the facts yourself and weigh both sides. To see where risk and potential reward currently stand for Mowi, start with the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Mowi?
If you want to build on what you have learned from Mowi, use the Simply Wall St screener to uncover other opportunities before the crowd spots them.
- Target stronger balance sheets by checking companies in the list of solid balance sheet and fundamentals (204 results), which pairs healthier finances with more resilient fundamentals.
- Hunt for potential value setups by scanning the 178 high quality undervalued stocks, which filters for quality businesses trading at what may be discounted prices.
- Add income angles to your watchlist by reviewing the 223 dividend fortresses, which highlights higher yielding stocks with robust payout profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com