
Diebold Nixdorf (DBD) Is Back In Focus, What Is Drawing Attention Now?
Diebold Nixdorf stock reacts to new fintech deployment with stc pay Bahrain
Diebold Nixdorf (DBD) is back in focus after stc pay Bahrain rolled out its first self-service network built on the company’s DN Series cash recyclers and software platform.
The rollout connects physical kiosks directly to stc pay Bahrain’s digital wallet and payments ecosystem, placing Diebold Nixdorf’s hardware, middleware and monitoring tools at the center of a high-traffic regional fintech project.
Despite the stc pay Bahrain rollout putting fresh attention on Diebold Nixdorf, the stock has cooled off in recent months, with the share price down 25.65% over the past quarter even as the 1-year total shareholder return sits at 15.97% and the 3-year total shareholder return is very large, anchored by a recent close at US$63.67. This suggests momentum has faded in the short term, while longer-term holders have still seen significant gains.
Scan beyond Diebold Nixdorf and find other payment and fintech infrastructure players on the move with our curated list of 92 AI infrastructure stocks.
Bulls see the stc pay Bahrain rollout as proof that Diebold Nixdorf’s platform still wins complex deals. Bears point to a 25.65% three month pullback. Which story does the current valuation lean toward?
Most Popular Narrative: 35% Undervalued
Analysts following Diebold Nixdorf see a fair value of $98.33 per share, well above the recent $63.67 close, so the current pullback is being weighed against a thesis built on contract execution, backlog conversion and cost discipline.
Localized and scaled manufacturing, including added production lines in Paderborn without higher operating costs, footprint reductions with higher capacity in Brazil and record teller cash recycler output in North Canton, is combining with the fit-for-purpose platform in Asia Pacific to support efficient fulfillment of backlog in regions like India and Latin America while reinforcing product gross margin and cash conversion from the US$814 million order book.
See why 3 investors see Diebold Nixdorf as 35% undervalued.
Result: Fair Value of $98.33 (UNDERVALUED)
Still, the story around Diebold Nixdorf can change quickly if service margin pressure lingers or if the US$814 million backlog takes longer to convert into cash.
Find out about the key risks to this Diebold Nixdorf narrative.
Another View: What Diebold Nixdorf’s P/E Is Saying
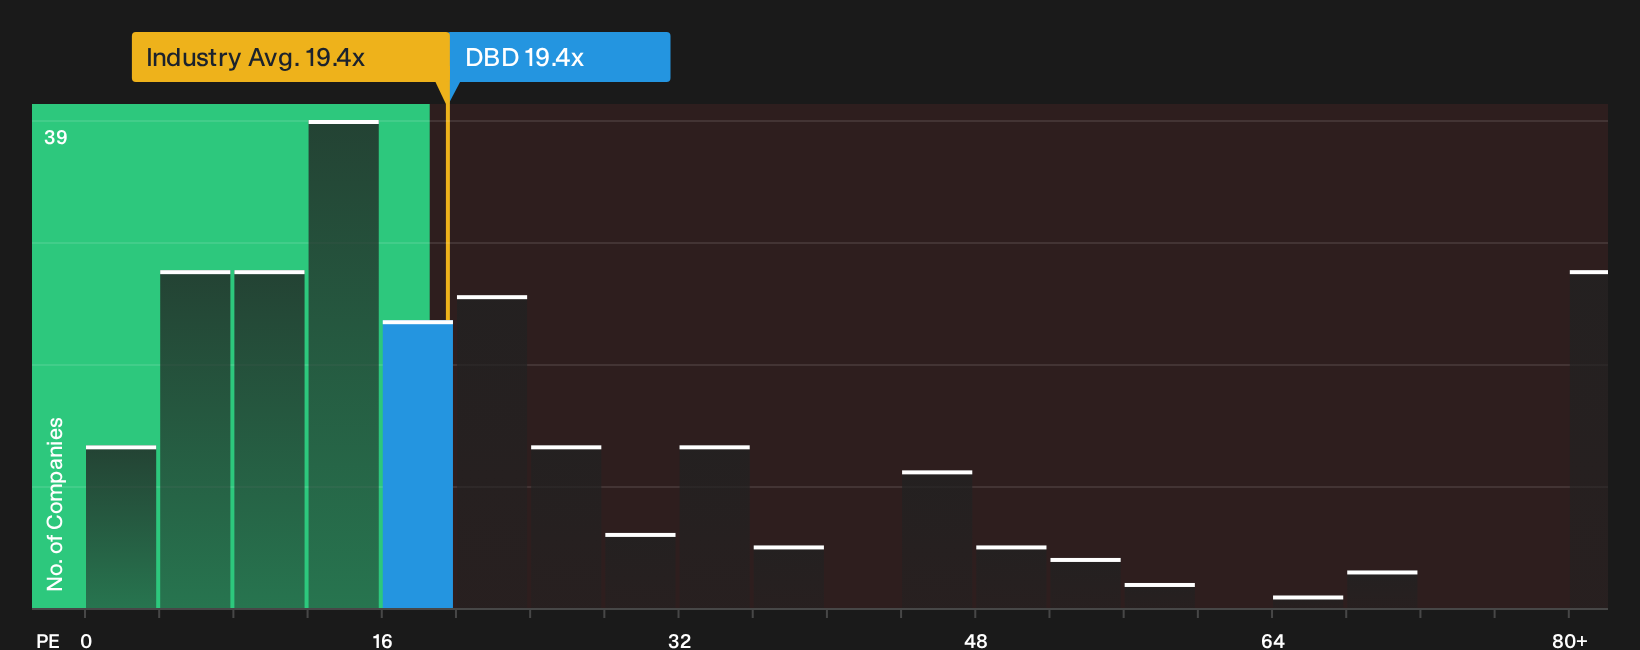
The fair value narrative leans on future cash flows and analyst targets, yet the simple P/E snapshot tells a different story. Diebold Nixdorf trades on 19.4x earnings, roughly in line with the Global Tech average of 19.4x. Its fair ratio is a much higher 42.1x, which suggests the market could re-rate the multiple over time or keep treating the stock cautiously if expectations change. Which way do you think that gap closes?
For a closer look at how this earnings multiple stacks up against peers and the fair ratio, check the valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages in the Diebold Nixdorf story can create noise, so consider acting promptly, review the numbers yourself and weigh both sides through 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Diebold Nixdorf?
If Diebold Nixdorf has your attention, do not stop there. Broader opportunities often show up where strong balance sheets, mispriced value and reliable income intersect.
- Target resilient balance sheets and cleaner fundamentals before the crowd by scanning the list of solid balance sheet and fundamentals (25 results).
- Hunt for quality businesses trading below their implied worth by working through the 29 high quality undervalued stocks.
- Build a payout focused watchlist that aims for income strength using the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com