
Is Deep Source Holdings (SEHK:990) A Bargain After Its 10 Year 67MW Malaysia Deal?
Deep Source Holdings (SEHK:990) drew fresh attention after subsidiary DeepSource (PN) Sdn. Bhd. signed a 10 year data centre colocation services agreement in Malaysia covering 67MW of IT capacity.
Recent trading suggests interest is picking up, with a 7 day share price return of 7.34% and a 90 day gain of 6.36% for Deep Source Holdings, even though the year to date share price return is down 18.75% and the 1 year total shareholder return has declined 19.86%. This points to improving short term momentum against a weaker longer term record.
Scan how Deep Source Holdings compares with other data and infrastructure plays by reviewing the hand picked 92 AI infrastructure stocks now shaping the next wave of capacity build outs.
Deep Source Holdings has just stitched together a long dated colocation deal while the share price is still working off a weak one year record. Does that skew the risk reward toward buyers or sellers at this valuation?
Preferred P/E of 10.8x: Is it justified for Deep Source Holdings?
On simple earnings math, Deep Source Holdings trades on a P/E of 10.8x, which sits below the Hong Kong Trade Distributors industry average of 11.5x yet above the peer group at 6x. This means the market is paying more than some direct comparables for each dollar of profit while still not stretching to the broader sector level.
The P/E multiple tells you how many dollars investors are currently willing to pay for each dollar of earnings. This matters for a group that mixes bulk commodity trading, financial services and now data centre exposure, because profit can move with volumes and spreads. For Deep Source Holdings, that 10.8x figure is being applied to earnings that recently showed very large year on year growth from a low base and improved net profit margins. This raises the question of how repeatable that profit profile is.
One way to interpret this setup is that the market is offering a discount to the wider Trade Distributors industry while still attaching a premium to the closer peer set. This may reflect caution around the mixed 5 year earnings track record, where profit declined on average even though the latest year rebounded sharply. Investors are effectively paying less than the industry for current earnings and also less than the SWS DCF model suggests, since the shares trade around HK$0.59 compared with an estimated future cash flow value of HK$1.22. However, they are still accepting a clear premium to the 6x peer average, which could be seen as a higher bar for the business to clear.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 10.8x (ABOUT RIGHT).
Still, the concentration in distribution, trading and processing revenue, alongside a 5 year total shareholder return that fell 35.66%, could pressure Deep Source Holdings if conditions tighten.
Find out about the key risks to this Deep Source Holdings narrative.
Another View on Deep Source Holdings
The P/E story for Deep Source Holdings looks balanced on the surface, yet the SWS DCF model points to something different. With the share price around HK$0.59 and an estimated future cash flow value of HK$1.22, the model suggests the stock is materially undervalued. Which signal do you treat as more important?
Look into how the SWS DCF model arrives at its fair value.
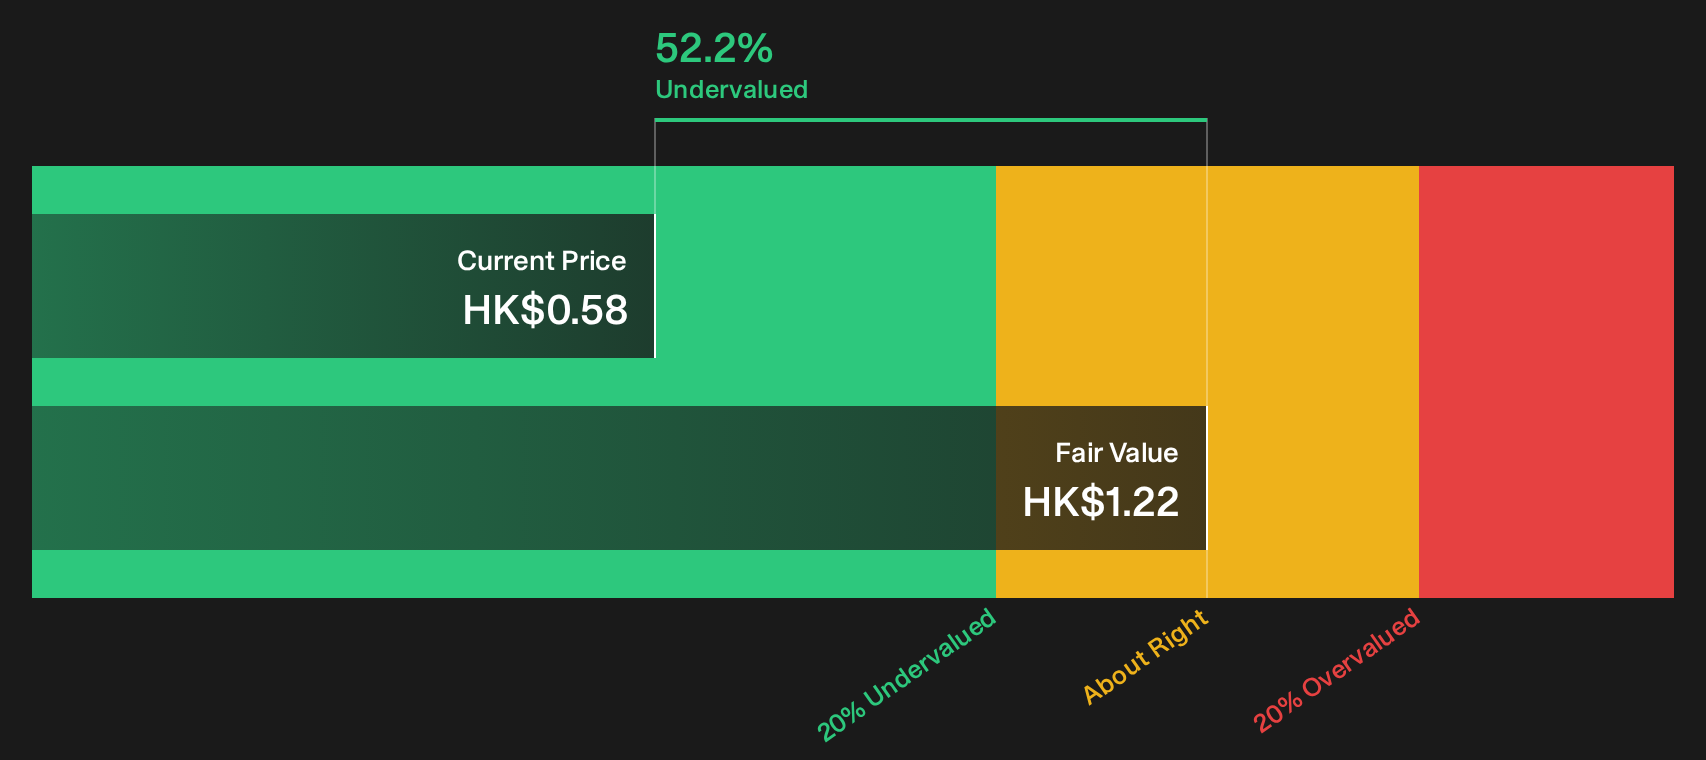
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Deep Source Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 178 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Deep Source Holdings often create the most interesting setups, especially when both risks and rewards are clearly on the table. If you want to move quickly and anchor your own view in the underlying data rather than the headline, start with the balance of 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Deep Source Holdings?
If Deep Source Holdings has your attention, do not stop at one ticker. Cast the net wider and pressure test your thesis against other opportunities.
- Target more potential upside by scanning companies that combine quality fundamentals with share prices that may lag their underlying value through the 178 high quality undervalued stocks.
- Build a steadier income stream by focusing on businesses that pair higher yields with resilient payout profiles in the 223 dividend fortresses.
- Dial down portfolio stress by concentrating on businesses that carry sturdier finances and cleaner balance sheets inside the list of solid balance sheet and fundamentals (204 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com